
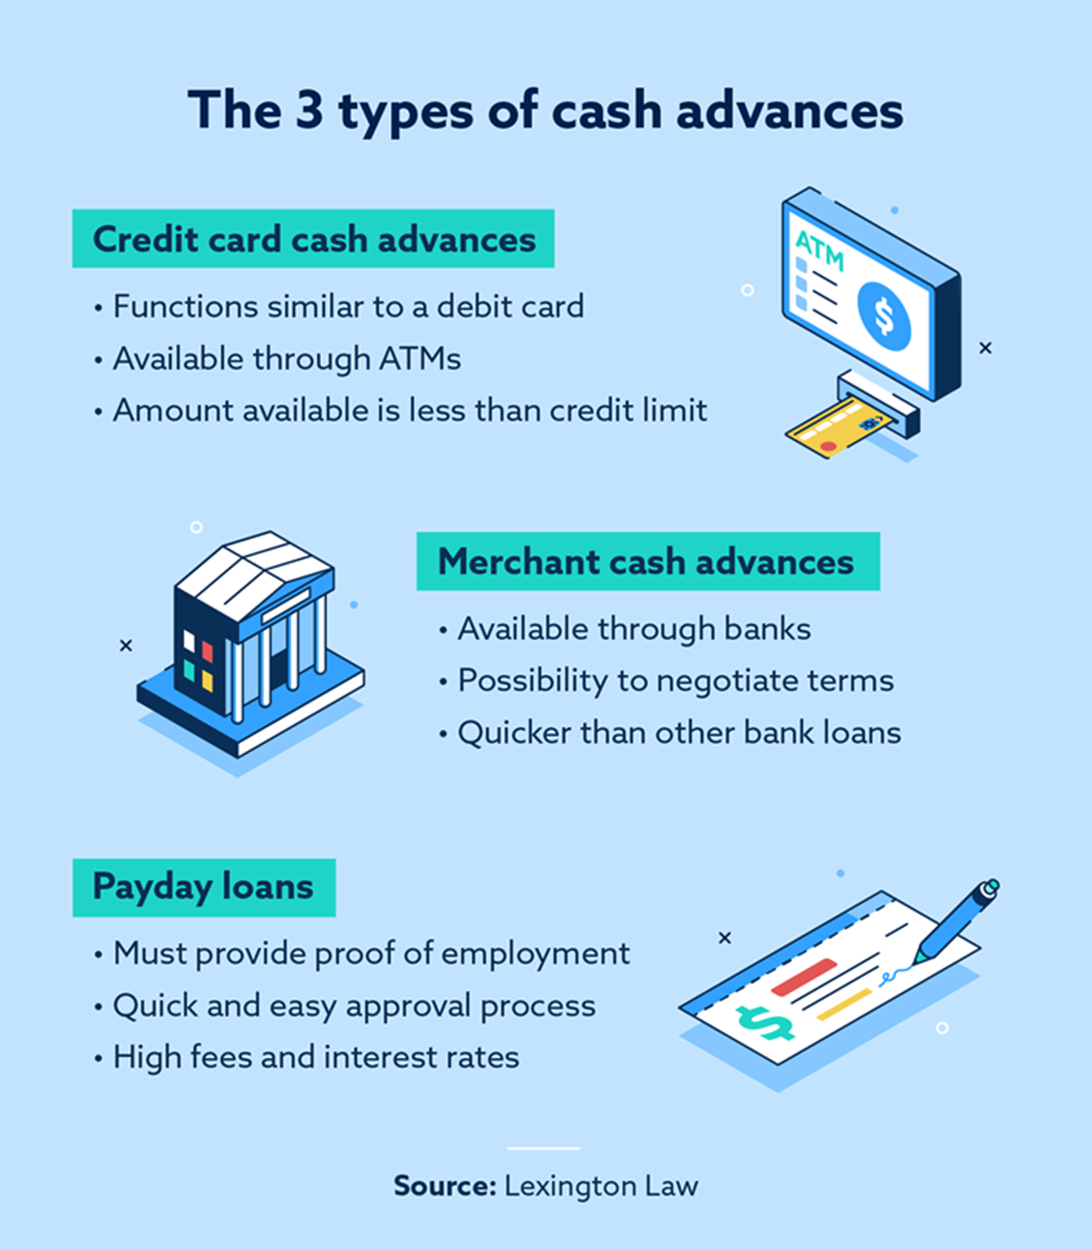
A cash advance on a credit card represents a unique financial transaction, diverging significantly from a standard purchase. At its core, it allows a cardholder to withdraw cash, typically from an ATM, bank, or via a convenience check, using their credit card. While seemingly straightforward on the surface, the underlying technological infrastructure, algorithmic processes, and innovative security measures that facilitate and govern these transactions are complex and sophisticated, placing them firmly within the realm of modern financial technology and innovation. This function relies on a vast network of interconnected digital systems, making it a prime example of how technology underpins contemporary financial services.
The Core Mechanism: Bridging Digital Finance
The ability to obtain a cash advance is not merely a simple withdrawal; it is a testament to the robust and resilient digital frameworks that define modern banking and credit. When a cardholder initiates a cash advance, they are engaging with a highly automated system designed to evaluate, approve, and disburse funds instantaneously. This process involves multiple layers of authentication, data exchange, and algorithmic decision-making, all executed in mere seconds.
Algorithmic Underpinnings and Risk Assessment
Behind every cash advance request lies a sophisticated set of algorithms that the issuing bank or financial institution employs. These algorithms are tasked with evaluating a myriad of factors in real-time to determine eligibility and approve the transaction. Key considerations include the cardholder’s available credit limit, their credit utilization ratio, past payment history, and any specific cash advance limits imposed on the account. The system rapidly processes this data, cross-referencing it with internal risk models to assess the likelihood of repayment. This algorithmic risk assessment is a critical innovative component, enabling financial institutions to manage exposure while offering immediate liquidity to customers. Furthermore, these algorithms are constantly updated and refined, often incorporating machine learning techniques to adapt to evolving fraud patterns and economic indicators, thereby enhancing their predictive accuracy and overall system security. The integration of predictive analytics ensures that decisions are not only swift but also informed by comprehensive data analysis, optimizing both user experience and institutional stability.
The Immediate Transaction: Digital Pathways
Once approved by the underlying algorithms, the actual transfer of funds for a cash advance relies on secure and efficient digital pathways. Whether at an ATM or a bank teller, the transaction initiates a series of encrypted communications between the point of access, the card network (e.g., Visa, Mastercard), and the issuing bank. Data packets containing transaction details, cardholder identification, and authorization requests traverse secure networks, employing advanced encryption standards to prevent interception and manipulation. For ATM transactions, EMV chip technology plays a crucial role, generating dynamic transaction data to enhance security and reduce cloning risks. The entire process, from card insertion to cash disbursement, leverages real-time data processing and robust network protocols, reflecting significant innovations in secure, rapid financial transfers. These digital pathways are designed for high availability and low latency, ensuring that users can access funds reliably, regardless of geographical location or time of day.
Beyond the Basics: Understanding the Technical Implications
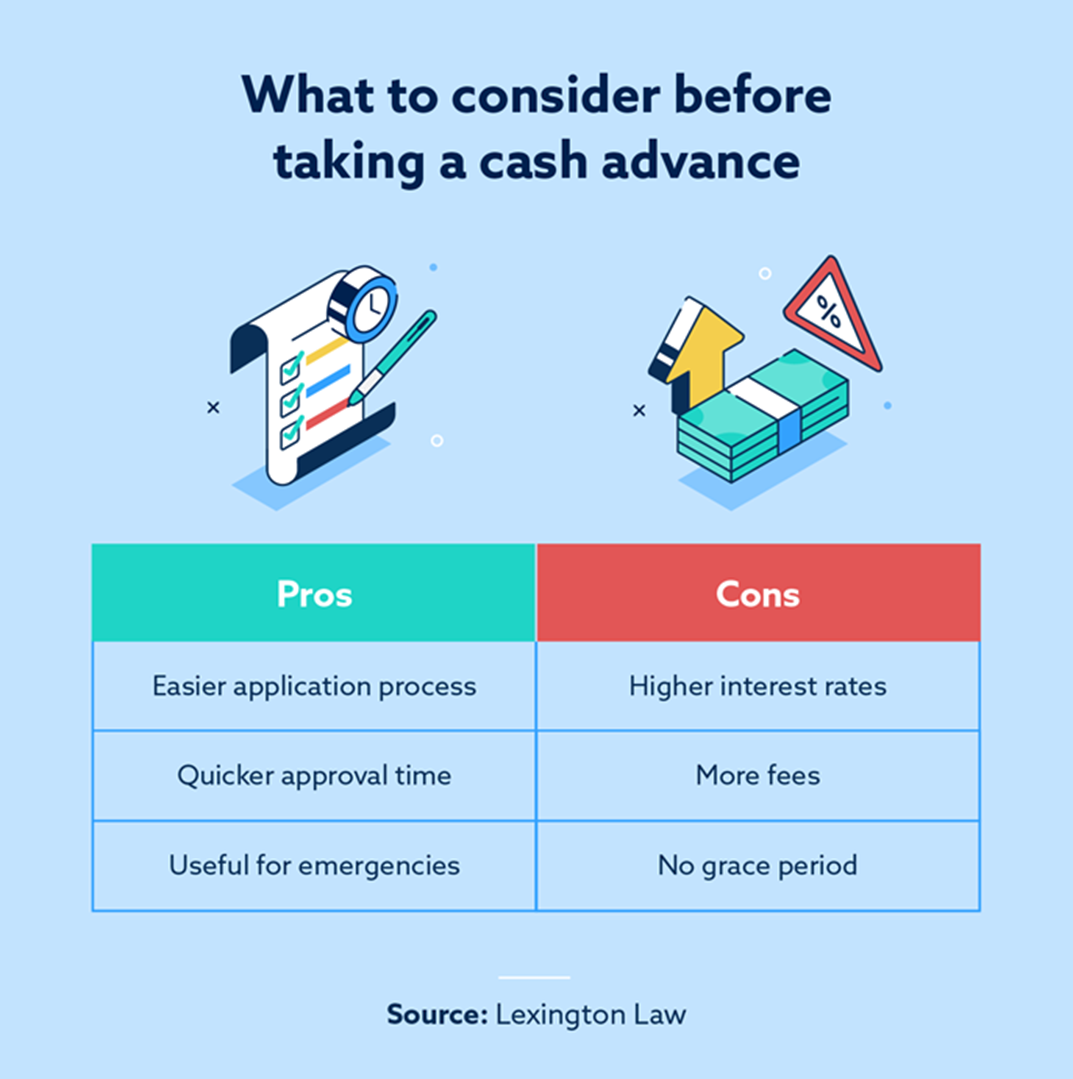
While a cash advance offers immediate access to funds, its technical implications extend far beyond the initial transaction. Unlike standard credit card purchases, which often come with a grace period, cash advances typically accrue interest immediately from the transaction date. This distinction is governed by specific financial algorithms and system configurations that treat cash advances differently within the credit card’s operational framework. Understanding these technical nuances is crucial for both cardholders and financial professionals.
Interest Calculation: Complex Financial Algorithms
The immediate accrual of interest on cash advances is a programmed feature within the credit card management system. Unlike purchase interest, which may be waived if the balance is paid in full by the due date, cash advance interest begins from day one. This requires specialized algorithms to calculate daily interest charges based on the outstanding cash advance balance and the predetermined Annual Percentage Rate (APR) for cash advances, which is often higher than the purchase APR. These algorithms must accurately track the transaction date, the amount, and then apply compound interest calculations over time, integrating with the cardholder’s billing cycle. The precision of these financial algorithms is paramount, ensuring accurate billing and compliance with regulatory standards. Innovations in these systems include more dynamic interest rate applications, potentially tied to real-time market conditions or individual credit risk assessments, though these are less common for basic cash advances. The technological complexity here ensures that every fractional day of interest is accounted for, providing financial institutions with their intended return on providing immediate liquidity.
Fee Structures and Their Automated Application
In addition to immediate interest, cash advances are almost invariably subject to a cash advance fee, typically a percentage of the amount withdrawn or a fixed minimum fee, whichever is greater. The automated application of these fees is another layer of technological sophistication. When a cash advance transaction is processed, the system automatically identifies it as such and applies the relevant fee based on predefined parameters stored within the cardholder’s account profile and the card’s terms and conditions. This automated fee calculation and application prevent manual errors and ensure consistency across millions of transactions. The innovation lies in the system’s ability to categorize transaction types instantly and apply complex, conditional fee structures without human intervention, maintaining the integrity and profitability of the cash advance service. These systems must also integrate with reporting frameworks to ensure transparency and compliance, automatically generating statements that clearly delineate cash advance fees and interest.
Security Protocols and Fraud Prevention
The digital nature of cash advances inherently exposes them to various security threats, making advanced security protocols and fraud prevention technologies indispensable. Protecting both the cardholder and the financial institution from unauthorized access, fraudulent transactions, and data breaches is a continuous process of innovation in financial technology.
Real-time Monitoring and Anomaly Detection
Financial institutions deploy sophisticated, AI-driven real-time monitoring systems to detect and prevent fraudulent cash advances. These systems continuously analyze transaction patterns, spending habits, geographical locations, and device information for every cardholder. If a transaction deviates significantly from the established norm—for example, a large cash advance requested from an unusual location or at an atypical time—the system flags it as suspicious. Machine learning algorithms, trained on vast datasets of legitimate and fraudulent transactions, are at the forefront of this innovation. They can identify subtle patterns and correlations that human analysts might miss, dramatically reducing the window for successful fraud. Upon detection of an anomaly, these systems can automatically decline the transaction, issue an alert to the cardholder, or escalate the case to a human fraud analyst for immediate review, showcasing a proactive approach to security that leverages cutting-edge technology. The speed of these systems is critical; they must process and analyze millions of transactions per second to be effective against rapidly evolving cyber threats.
The Evolution of Digital Lending: Future Innovations
The technology behind cash advances continues to evolve, driven by advancements in artificial intelligence, machine learning, and distributed ledger technologies. Future innovations aim to enhance security, personalize offerings, and integrate more seamlessly with broader digital financial ecosystems.
AI and Machine Learning in Credit Decisions
The role of AI and machine learning in credit decisions is expanding beyond just fraud detection. These technologies are being harnessed to create more nuanced and personalized cash advance offers. By analyzing a broader spectrum of data—including non-traditional credit data, if permissible and ethically sourced—AI can develop more accurate risk profiles, potentially leading to customized cash advance limits, interest rates, or even fee structures tailored to an individual’s financial behavior and needs. This represents a significant innovation in personalized lending, moving away from one-size-fits-all approaches. Furthermore, AI can predict the likelihood of default with greater accuracy, allowing institutions to adjust their lending strategies dynamically and optimize their portfolios while still serving eligible customers. The goal is to create a more efficient, equitable, and adaptable lending environment.

Blockchain and Decentralized Finance Potential
Looking further into the future, blockchain technology and decentralized finance (DeFi) principles hold transformative potential for cash advance mechanisms. While still nascent in mainstream credit card operations, distributed ledger technology could offer enhanced transparency, immutability of transaction records, and potentially lower transaction costs. Smart contracts could automate the terms and conditions of a cash advance, from disbursement to interest calculation and repayment, ensuring programmatic enforcement without intermediaries. Though significant regulatory and infrastructural hurdles remain, the inherent security and auditability of blockchain could redefine how cash advances are processed and secured in a future where financial innovation continues to push boundaries. This paradigm shift could lead to more open, programmable financial services, fundamentally altering the existing credit card ecosystem and the technical underpinnings of immediate liquidity solutions.