
The Solo 401(k), also known as an Individual 401(k) or Uni-401(k), represents a robust and often overlooked retirement savings vehicle specifically designed for self-employed individuals and small business owners with no full-time employees other than themselves and/or their spouse. It combines the features of a traditional 401(k) with the flexibility needed by independent contractors, freelancers, and sole proprietors, offering significant tax advantages and high contribution limits. For those navigating the entrepreneurial landscape, understanding the mechanics and benefits of a Solo 401(k) is paramount to building substantial retirement security.
Understanding the Solo 401(k): A Powerful Retirement Solution
At its core, a Solo 401(k) is a qualified retirement plan that includes both an employee contribution and an employer contribution component. This dual-role structure is what makes it uniquely powerful for self-employed individuals, as they act as both the employee and the employer. This allows for significantly higher contribution limits compared to other self-employed retirement plans like a SEP IRA or SIMPLE IRA, while also offering the same tax-deferred growth benefits.

The “employee” portion of the contribution functions much like a traditional 401(k) in a corporate setting. You, as the self-employed individual, can elect to contribute a portion of your compensation (typically up to 100% of your net adjusted self-employment income, or gross W-2 income if incorporated) up to an annual limit set by the IRS. These contributions can be made on a pre-tax (traditional) basis, reducing your current taxable income, or as Roth contributions (if the plan allows), meaning contributions are made with after-tax dollars but qualified withdrawals in retirement are tax-free.
The “employer” portion is where the Solo 401(k) truly shines. As the employer, you can make a profit-sharing contribution to your own plan. This employer contribution is typically limited to 25% of your gross W-2 wages (if incorporated) or 20% of your net adjusted self-employment income (if unincorporated). The combination of these two contribution types allows for a substantial amount of money to be stashed away for retirement each year, far exceeding the limits of individual retirement accounts.
Beyond contributions, a Solo 401(k) offers several advantageous features. It typically allows for loan provisions, enabling participants to borrow from their vested account balance, similar to a corporate 401(k). This can provide a flexible source of funds for various needs, though careful consideration of repayment terms and potential tax implications is necessary. Furthermore, like other qualified retirement plans, a Solo 401(k) can often accept rollovers from previous employer-sponsored plans (like old 401(k)s or 403(b)s) and traditional IRAs, consolidating retirement assets into a single, high-contribution vehicle.
Eligibility and Contribution Limits
Eligibility for a Solo 401(k) is straightforward: you must have self-employment income, and your business cannot have any full-time employees (excluding yourself and your spouse, if your spouse is also an employee of the business). This makes it ideal for consultants, freelancers, independent contractors, small business owners, and those with significant side hustles. Even if you work a full-time job and contribute to an employer’s 401(k), you can still establish a Solo 401(k) for any self-employment income you earn, leveraging its additional contribution capacity.
The contribution limits are what make the Solo 401(k) exceptionally attractive. For a given tax year, the total contributions (employee plus employer) cannot exceed a certain dollar limit, which is adjusted annually for inflation by the IRS. For example, for 2024, the total contribution limit is $69,000, or $76,500 if you are age 50 or older and qualify for catch-up contributions.
Let’s break down how this works:
- Employee Contributions: You can contribute up to 100% of your adjusted net earnings from self-employment, or your W-2 wages, up to the maximum elective deferral limit ($23,000 for 2024, or $30,500 if age 50 or older). These can be pre-tax or Roth contributions, depending on the plan’s provisions.
- Employer Contributions: Your business can contribute up to 25% of your gross W-2 wages, or approximately 20% of your net adjusted self-employment income (after deducting one-half of self-employment taxes and the employer contributions themselves for unincorporated businesses).
The beauty lies in combining these two. For instance, if you’re a sole proprietor with significant net earnings, you can max out your employee contribution and then contribute a substantial employer profit-sharing portion, often reaching the overall annual limit. This dual contribution mechanism is a major differentiator from other self-employed retirement plans.
Key Advantages for Self-Employed Individuals
The Solo 401(k) offers several compelling advantages that make it a superior choice for many self-employed individuals compared to other retirement savings options:

High Contribution Limits
As discussed, the ability to contribute as both an employee and an employer allows for significantly higher annual contributions than an IRA, a SEP IRA, or a SIMPLE IRA. This accelerated savings potential is crucial for entrepreneurs who may have started saving later or desire to accumulate wealth more rapidly.
Flexibility and Investment Control
Unlike many corporate 401(k)s with limited investment options, Solo 401(k) plans often provide broad investment flexibility. Account holders can typically invest in a wide range of assets, including stocks, bonds, mutual funds, exchange-traded funds (ETFs), and sometimes even real estate or other alternative investments, depending on the custodian. This control allows individuals to tailor their investment strategy to their risk tolerance and financial goals.
Loan Provision Availability
Many Solo 401(k) plans allow participants to take a loan from their account, typically up to 50% of the vested balance or $50,000, whichever is less. While borrowing from retirement savings should be approached with caution, this feature can provide an emergency funding source without triggering taxes or penalties, provided the loan is repaid according to IRS rules.
Roth Contribution Option
The availability of a Roth Solo 401(k) option allows individuals to make after-tax contributions that grow tax-free and can be withdrawn tax-free in retirement (subject to certain conditions). This provides valuable tax diversification, particularly for those who anticipate being in a higher tax bracket during retirement.
Streamlined Administration
Compared to complex corporate 401(k) plans, Solo 401(k) administration is relatively simple. For most plans, as long as the account balance doesn’t exceed $250,000 by the end of the year, there are no annual IRS Form 5500 filings required. Once the assets exceed $250,000, a simple informational Form 5500-EZ must be filed annually, which is generally not burdensome.
Setting Up and Administering Your Solo 401(k)
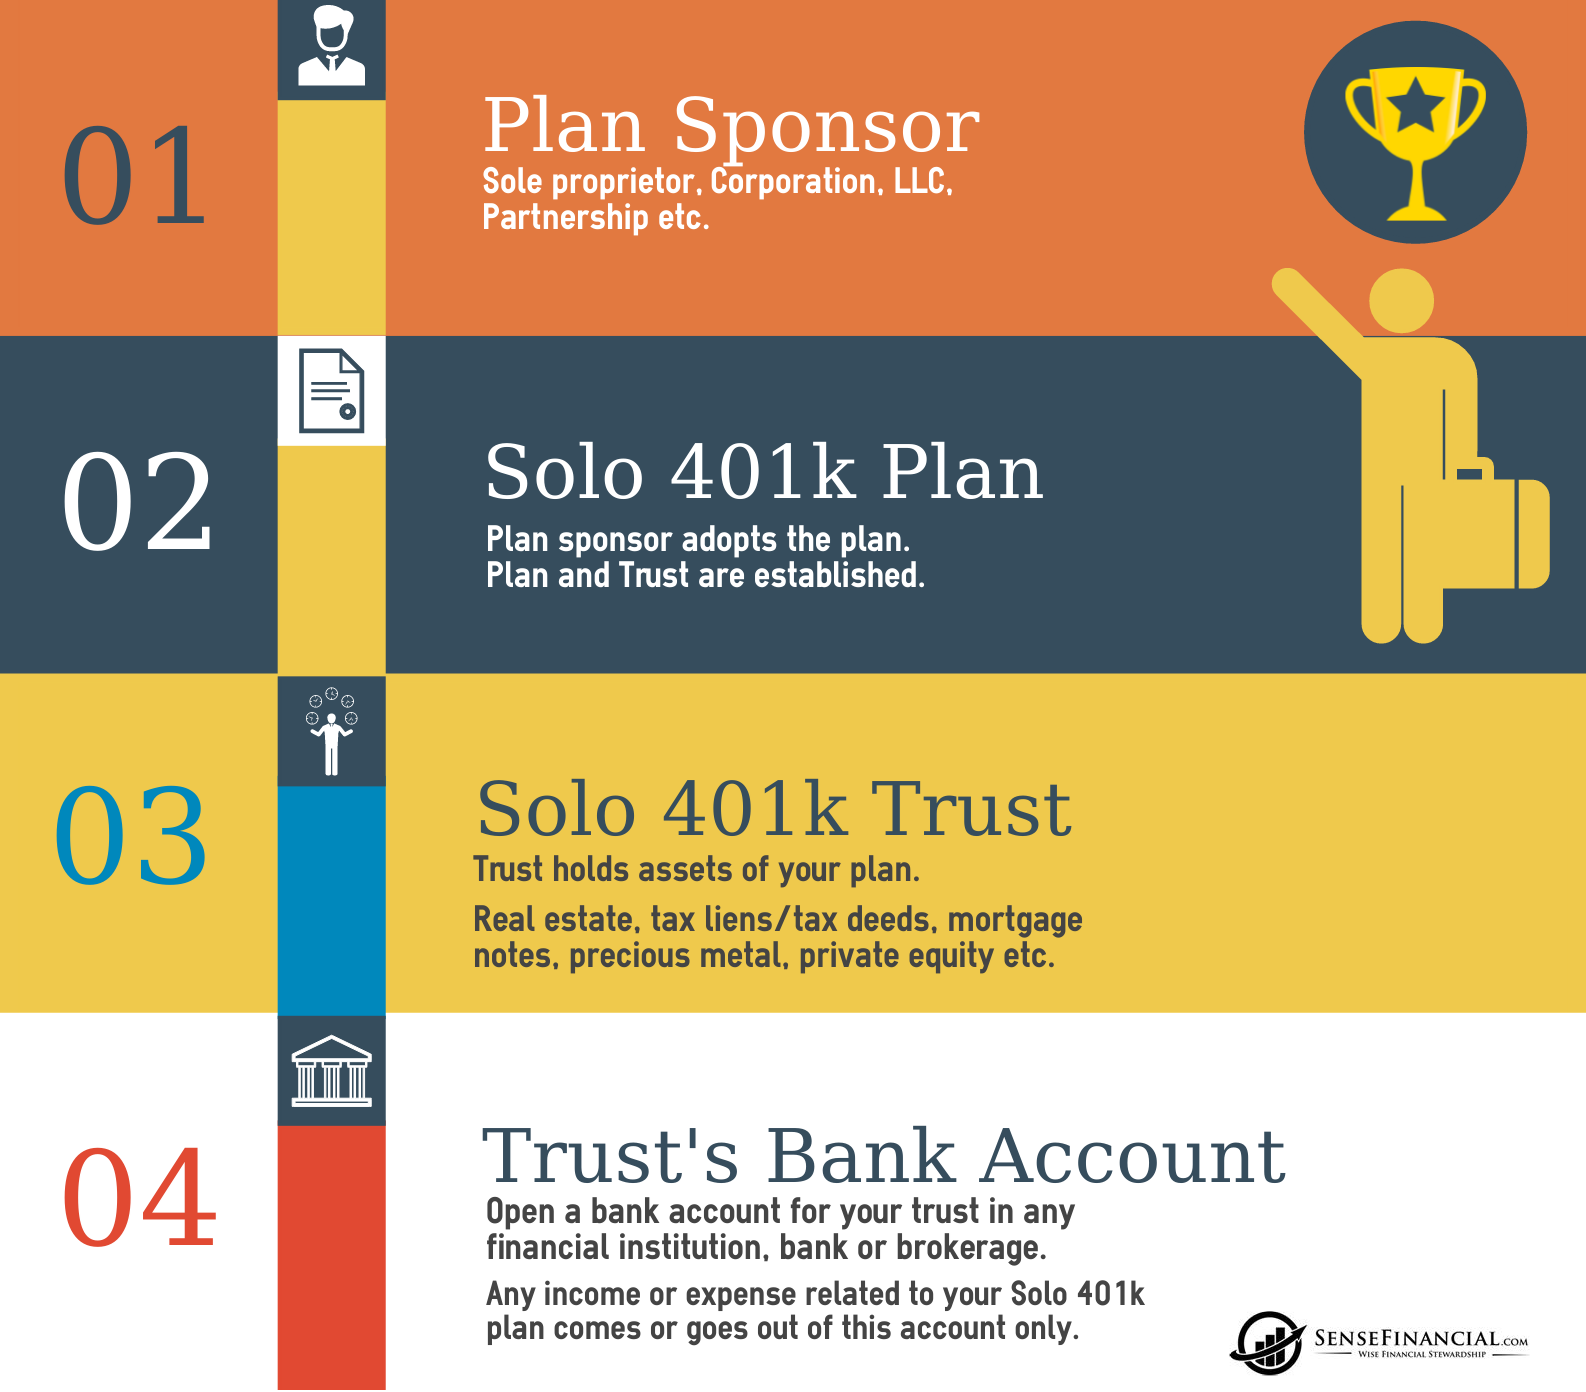
Setting up a Solo 401(k) typically involves a few key steps. First, you need to open a plan with a financial institution that offers Solo 401(k)s. Many brokerage firms, mutual fund companies, and specialized Solo 401(k) providers offer these plans. You’ll generally need to complete plan adoption agreements and custodial agreements. Some providers may also require you to establish your business as a legal entity, though many plans are suitable for sole proprietors operating under their Social Security number (with an EIN being helpful).
Once the plan is established, you will open specific investment accounts within the plan (e.g., a brokerage account for stocks and ETFs, or a mutual fund account). You then determine your contributions for the year, ensuring you stay within the IRS limits. Employee contributions for the previous tax year generally must be made by the tax filing deadline (typically April 15th), while employer contributions can be made up to the extended due date of your tax return (e.g., October 15th).
Administering the plan mostly involves managing your investments and tracking contributions. As mentioned, for balances under $250,000, there are minimal annual reporting requirements. If your balance exceeds $250,000, you will need to file Form 5500-EZ, which is a relatively straightforward informational return. Keeping good records of your self-employment income and contributions is essential for tax purposes.
Comparing Solo 401(k) with Other Retirement Plans
While the Solo 401(k) is a powerful tool, it’s helpful to understand how it stacks up against other retirement options for the self-employed:
Solo 401(k) vs. SEP IRA
A SEP IRA (Simplified Employee Pension) is another popular choice for the self-employed. It is simpler to set up and administer than a Solo 401(k), as it only involves employer contributions. However, its main drawback is that it only allows employer contributions, capped at 25% of compensation (or 20% of net self-employment income), up to the same overall limit as the Solo 401(k) ($69,000 for 2024). A Solo 401(k) allows both employee and employer contributions, often enabling individuals with lower net self-employment income to contribute more overall by maximizing the employee deferral portion. A Solo 401(k) also offers loan provisions and the Roth option, which SEP IRAs do not.
Solo 401(k) vs. SIMPLE IRA
A SIMPLE IRA (Savings Incentive Match Plan for Employees) is suitable for businesses with up to 100 employees. For the self-employed, it also has lower contribution limits than a Solo 401(k). Employee contributions are limited (e.g., $16,000 for 2024, plus catch-up), and the employer must match a percentage of contributions or make a fixed contribution. The Solo 401(k) offers significantly higher contribution potential and more flexibility.
Solo 401(k) vs. Traditional/Roth IRA
Traditional and Roth IRAs are individual retirement accounts with much lower contribution limits (e.g., $7,000 for 2024, plus catch-up for those 50 and over). While they offer tax benefits and investment flexibility, they simply cannot match the high savings potential of a Solo 401(k). An IRA can be a good supplement, but not a replacement, for a Solo 401(k) if you have substantial self-employment income.
In conclusion, the Solo 401(k) stands out as an exceptionally effective retirement planning tool for self-employed individuals and small business owners without employees. Its high contribution limits, combined with tax advantages, investment flexibility, and optional features like Roth contributions and loan provisions, make it a cornerstone for building robust financial security in the entrepreneurial journey.