
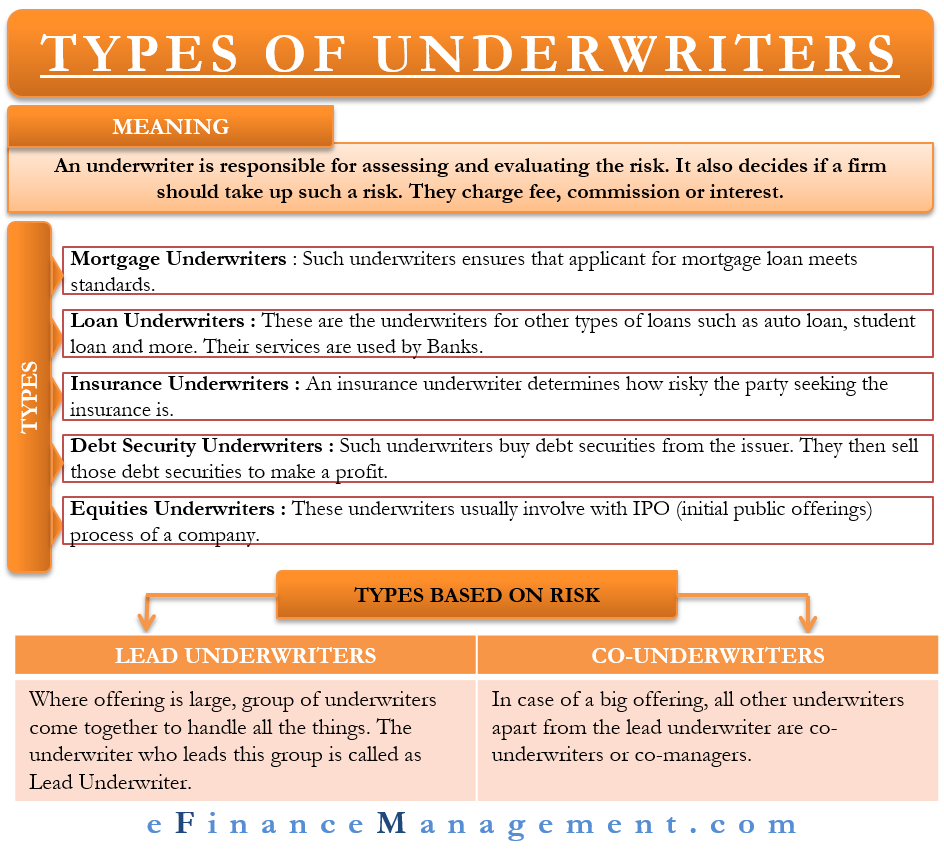
In the rapidly evolving landscape of unmanned aerial vehicles (UAVs), commonly known as drones, the role of underwriters has become indispensable, particularly within the domain of Tech & Innovation. As drones transition from niche hobbyist gadgets to critical tools for industries ranging from logistics and agriculture to infrastructure inspection and public safety, the complexities and risks associated with their advanced technologies and operations escalate. Underwriters are the specialized professionals who assess these risks, evaluate potential liabilities, and determine the terms and premiums for insurance policies, effectively enabling the growth and adoption of innovative drone solutions. Their expertise helps to mitigate financial exposure for manufacturers, operators, and service providers navigating the cutting-edge of drone technology.

The Evolving Role of Underwriters in Drone Technology
The drone industry, characterized by its rapid advancements in artificial intelligence (AI), autonomous flight capabilities, sophisticated sensor payloads, and complex operational procedures, presents a unique challenge for traditional risk assessment models. Underwriters operating in this space must possess not only a deep understanding of insurance principles but also a keen insight into the technological nuances of drones. They are the gatekeepers, ensuring that the financial risks inherent in deploying groundbreaking drone innovations are adequately managed and accounted for. Without their specialized analysis, the adoption of new drone applications would face significant hurdles due to unquantified and uninsurable liabilities.
Assessing Risk in a Dynamic Landscape
The dynamic nature of drone technology means that risk profiles are constantly shifting. New hardware designs, software updates, enhanced battery chemistries, and novel operational concepts continually alter the spectrum of potential failures and incidents. For underwriters, this necessitates an iterative and flexible approach to risk assessment. They scrutinize every aspect, from the drone’s manufacturing quality and flight performance specifications to its intended use environment, pilot training protocols, and adherence to emerging regulatory frameworks.
Key areas of focus for underwriters when assessing drone innovation include:
- Hardware Integrity: Evaluating the reliability of airframes, propulsion systems, and critical components, especially those that are novel or proprietary.
- Software Reliability: Analyzing the robustness of flight control systems, navigation algorithms, and AI models for autonomous operations, looking for potential vulnerabilities or bugs.
- Operational Scenarios: Understanding the specific risks associated with particular applications, such as flying beyond visual line of sight (BVLOS), operations over populated areas, or flights in challenging environmental conditions.
- Data Handling: Assessing risks related to data breaches, privacy violations, or errors in data collected through remote sensing, mapping, or surveillance activities.
Key Considerations for Drone Insurance
Underwriters craft policies that address a multifaceted array of potential incidents. These typically include:
- Hull Insurance: Covering physical damage to the drone itself, often extended to include payload components like high-resolution cameras, LiDAR systems, or thermal imaging sensors. For innovative drone designs, assessing the cost of replacement or repair for custom parts becomes a crucial task.
- Third-Party Liability: Protecting against claims arising from property damage or bodily injury to third parties caused by drone operations. This is particularly complex for autonomous systems where the “operator” might be an AI, raising questions of causality and responsibility.
- Payload Liability: Specific coverage for damage or malfunction of specialized equipment carried by the drone, which can be immensely expensive, such as scientific instruments or high-end cinematic cameras.
- Cyber Liability: A rapidly growing area, addressing risks associated with hacking, data breaches, or system interference, especially pertinent for drones involved in critical infrastructure inspection, sensitive data collection, or autonomous delivery systems.
- Non-Owned Drone Liability: For organizations that use third-party drone services, underwriters help assess the liability risks associated with those external operations.
Underwriting for Advanced Drone Innovations
The frontier of drone technology, encompassing AI-powered flight, sophisticated remote sensing, and complex autonomous missions, significantly amplifies the challenge for underwriters. These innovations introduce new categories of risk that traditional insurance models were not designed to cover, requiring pioneering approaches to risk assessment and policy development.
Autonomous Flight and AI Integration
The promise of fully autonomous drones, capable of navigating complex environments and making real-time decisions without direct human intervention, is a cornerstone of future drone innovation. However, this also presents one of the most significant underwriting challenges. When an AI system is responsible for flight path optimization, obstacle avoidance, or payload deployment, the question of fault in the event of an incident becomes intricate. Underwriters must delve into the methodologies behind AI development, validation, and testing. They assess factors such as:
- Algorithm Robustness: The maturity and proven reliability of the AI algorithms, including machine learning models used for perception and decision-making.
- Failsafe Mechanisms: The presence and effectiveness of redundant systems and protocols designed to take over in case of AI malfunction or unexpected scenarios.
- Human Oversight: The level of human supervision, even in autonomous operations, and the ability for human intervention when necessary.
- Cybersecurity of AI Systems: The potential for external interference with autonomous decision-making processes, which could lead to malicious or accidental incidents.
The shift from human-piloted flight to AI-driven autonomy necessitates a re-evaluation of liability frameworks. Underwriters are instrumental in shaping policies that allocate risk fairly between software developers, drone manufacturers, and operational entities, driving best practices in AI safety and accountability within the drone sector.
Data Security and Remote Sensing Liabilities
Drones equipped with advanced sensors for remote sensing, mapping, and surveillance collect vast amounts of data, often of a sensitive nature. This includes high-resolution imagery, thermal data, LiDAR point clouds, and even chemical signatures. The innovation in sensor technology opens new possibilities but also introduces substantial data-related risks. Underwriters evaluate:
- Data Privacy Compliance: Adherence to data protection regulations (e.g., GDPR, CCPA) when collecting, storing, and processing personally identifiable information or proprietary data.
- Cybersecurity Protocols: The robustness of systems protecting collected data from unauthorized access, modification, or deletion, both during transmission and storage.
- Data Accuracy and Misinterpretation: The potential for financial loss or legal action stemming from inaccurate data provided by drone-based remote sensing, leading to incorrect business decisions or legal disputes.
- Liability for Data Usage: The risks associated with how the collected data is subsequently used, especially in fields like urban planning, resource management, or legal evidence gathering.
As drone innovation expands into critical data acquisition, underwriters play a vital role in ensuring that robust data security measures and clear liability frameworks are in place, protecting all parties involved from the potential repercussions of data mismanagement.
Navigating Regulatory and Technological Hurdles
The intersection of rapidly advancing drone technology and evolving regulatory frameworks creates a complex environment that underwriters must continuously monitor and interpret. Their ability to assess risk is directly influenced by the current legal landscape, which often struggles to keep pace with technological innovation.
The Impact of Evolving Standards
Drone regulations are dynamic, with aviation authorities worldwide (e.g., FAA in the US, EASA in Europe) constantly refining rules for drone operations, certification, and airworthiness. These changes directly affect the risk profile of drone activities. Underwriters must stay abreast of:
- Certification Requirements: New standards for drone hardware, software, and operational procedures, which indicate a baseline of safety and reliability.
- Operational Limitations: Evolving rules on flight altitudes, distances, operating over people, or BVLOS operations, which dictate the exposure level.
- Pilot and Operator Licensing: Changes in requirements for drone pilots and operational entities, influencing the competency and professionalism of operators.
For innovative drone applications, particularly those pushing the boundaries of what is currently allowed (e.g., urban air mobility, autonomous package delivery), underwriters often work with clients to ensure their proposed operations align with existing or anticipated regulations, or to structure policies that account for the unique regulatory risks of experimental flights.
Future Trends in Drone Underwriting
Looking ahead, the role of underwriters in the drone sector will become even more specialized and critical. The continued integration of AI, the expansion of autonomous fleets, and the development of new applications like drone-based search and rescue or sophisticated environmental monitoring will demand ever-more nuanced risk assessment. Predictive analytics, leveraging vast datasets of drone flight logs, incident reports, and operational parameters, will likely become a powerful tool for underwriters to anticipate and quantify risks with greater precision. Furthermore, as the industry matures, standardization efforts in drone technology and operations will provide underwriters with more consistent benchmarks for evaluating risk, fostering greater insurance availability and affordability, and ultimately accelerating the safe adoption of groundbreaking drone innovations.