
In the rapidly evolving landscape of financial technology, where artificial intelligence and data analytics are reshaping every facet of banking and lending, the term “conditionally approved” has taken on nuanced significance for loan applicants. Far from being a mere placeholder, it represents a critical stage in the modern loan acquisition process, indicating that while a preliminary assessment is favorable, the final green light hinges on the fulfillment of specific criteria. Understanding this pivotal status is crucial for borrowers navigating an increasingly automated yet still rigorous financial system.
The Intersection of Technology and Initial Loan Assessments
The journey to securing a loan has been dramatically transformed by advancements in technology and innovation. Gone are the days of purely manual reviews that could stretch for weeks before even an initial indication of approval or denial. Today, FinTech platforms and traditional lenders alike leverage sophisticated algorithms, machine learning, and vast datasets to conduct preliminary risk assessments with unprecedented speed and accuracy. This technological leap is precisely why “conditionally approved” has become so common.
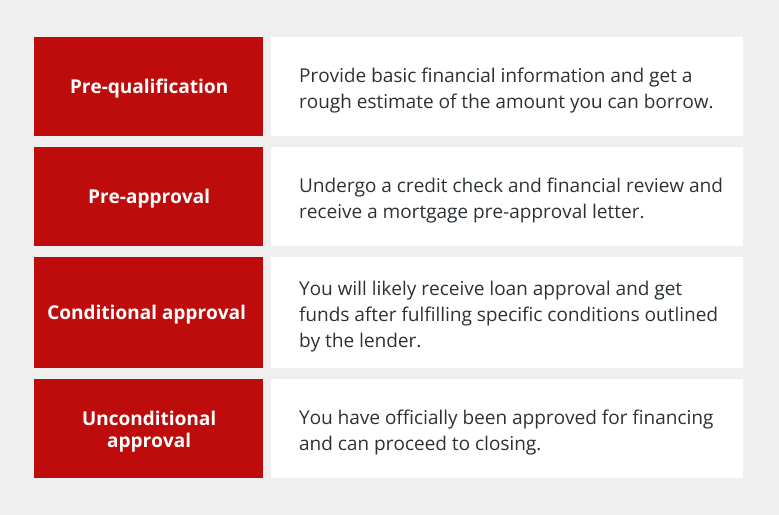
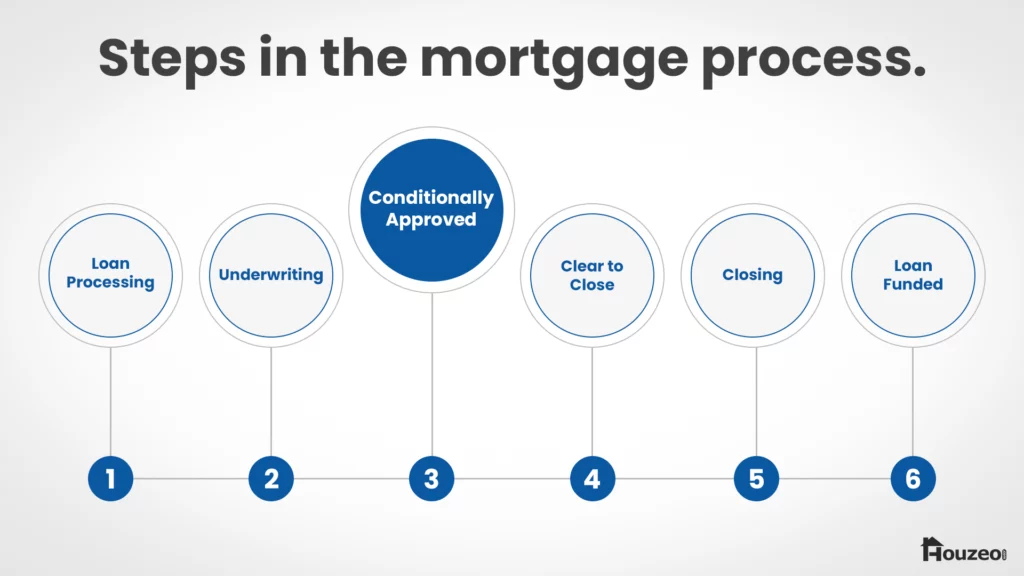
When a loan application receives conditional approval, it signifies that the applicant has met the initial, high-level eligibility criteria as determined by automated systems. These systems rapidly analyze credit scores, income data, debt-to-income ratios, and other critical financial indicators against predefined risk models. An AI-powered underwriting engine can sift through thousands of data points in moments, comparing the applicant’s profile to historical lending patterns and default rates. If the applicant’s profile aligns favorably with the lender’s risk appetite at this preliminary stage, a conditional approval is issued. This doesn’t mean the loan is guaranteed, but rather that the initial technological vetting has passed, moving the application forward to a more detailed, often human-assisted, verification phase. It’s an innovative step that significantly accelerates the early stages of loan processing, offering borrowers quicker feedback than ever before.
Navigating the Path from Conditional to Full Approval
A conditional approval is not an endpoint but a gateway, signaling that the lender is serious about extending credit, provided the applicant can satisfy a set of outstanding requirements. These conditions are typically designed to verify the information initially submitted, mitigate potential risks identified by automated systems, or fulfill regulatory obligations.
Common Conditions and Their Purpose
The specific conditions for final approval vary widely depending on the type of loan (mortgage, personal loan, auto loan, business loan) and the lender’s policies. However, some common requests include:
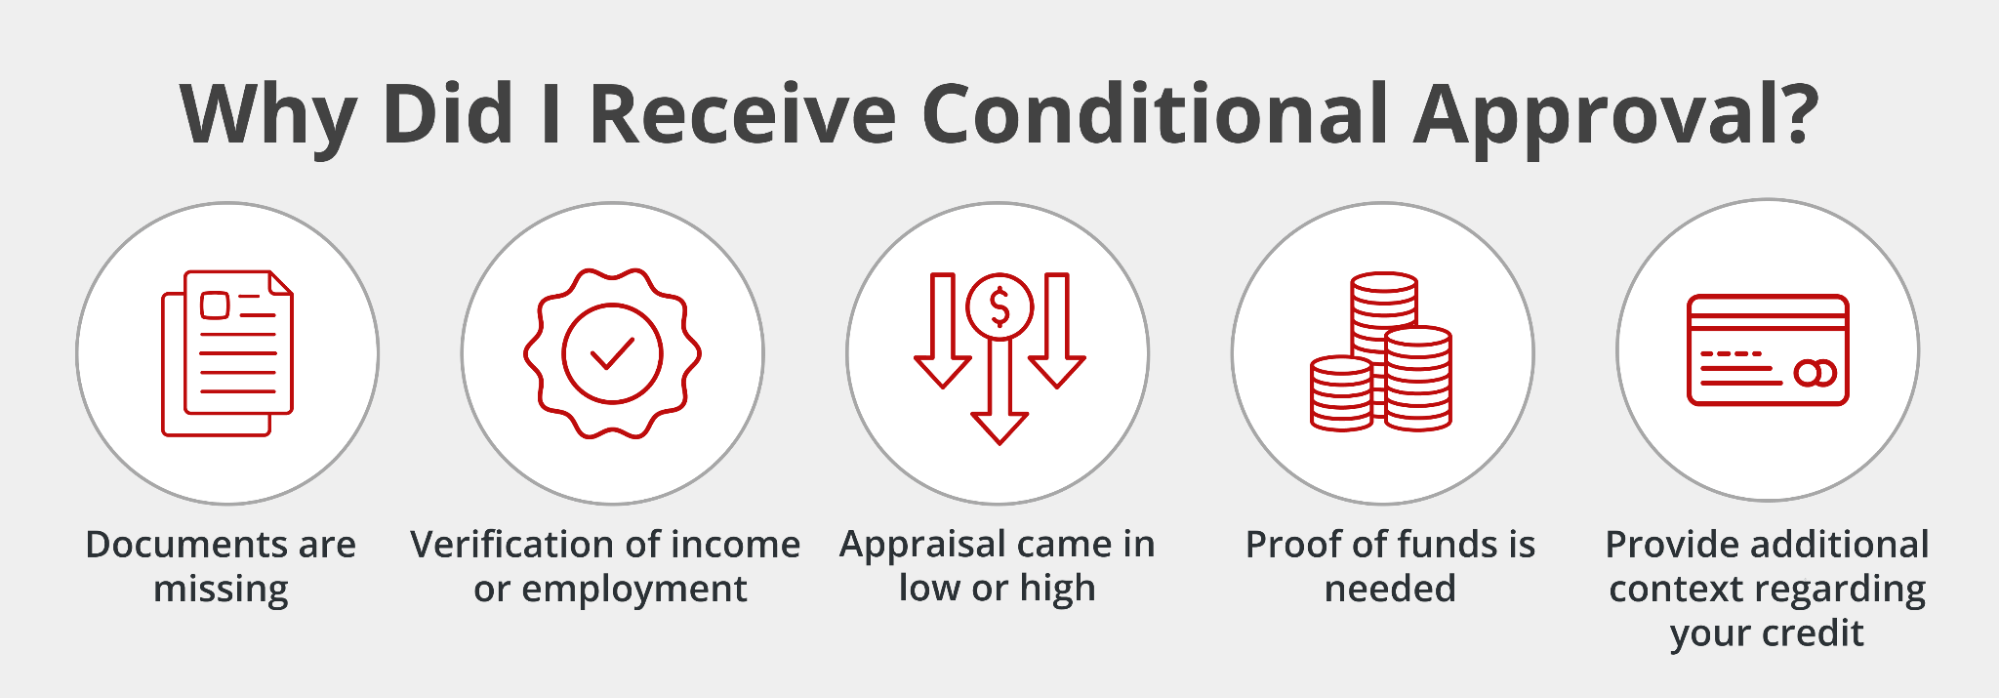
- Documentation Verification: Lenders will almost always require official documentation to verify income, employment history, assets, and liabilities. This might include recent pay stubs, W-2 forms, tax returns, bank statements, and investment account statements. While AI can quickly process initial digital submissions, the subsequent human review ensures authenticity and accuracy, guarding against fraud.
- Property Appraisal and Inspection (for secured loans): For mortgages or other loans secured by real estate, an independent appraisal is mandatory to confirm the property’s market value. This ensures the loan amount is commensurate with the collateral, protecting the lender’s investment. Similarly, inspections confirm the property is structurally sound and free from major defects that could impact its value.
- Credit Report Updates or Explanations: Sometimes, the initial credit pull might be a soft inquiry, or the lender may require a more recent hard inquiry. If new derogatory information appears or if there are discrepancies, the lender may ask for explanations or updated reports.
- Proof of Down Payment/Reserves: Especially for large loans like mortgages, lenders want to ensure the borrower has the necessary funds for a down payment and sufficient reserves after closing. This demonstrates financial stability and commitment.
- Satisfaction of Outstanding Debts: In some cases, conditional approval might be contingent on the borrower paying off a specific debt or closing a credit line to improve their debt-to-income ratio or overall credit profile.
- Insurance Verification: For secured loans, proof of adequate insurance (e.g., homeowner’s insurance for a mortgage, comprehensive insurance for an auto loan) is a standard requirement to protect both the borrower and the lender from unforeseen events.
The fulfillment of these conditions is where the technological advantages of initial screening are complemented by thorough human due diligence. While AI can flag potential issues, the detailed verification process often still requires human eyes to review complex documents, communicate with applicants, and make qualitative judgments. This hybrid approach – leveraging technology for speed and efficiency, combined with human oversight for complexity and compliance – represents the current state of innovation in lending.
Innovation in Risk Assessment and Due Diligence
The underlying innovation behind conditional approvals lies in the sophisticated risk assessment models employed by lenders. These models, often powered by machine learning and big data analytics, continuously evolve to identify risk factors more accurately and efficiently. For example, behavioral economics, predictive analytics, and alternative data sources (with proper consent and privacy considerations) are increasingly integrated into the initial screening process. This allows for a more comprehensive, real-time assessment of an applicant’s financial health and likelihood of repayment.
However, even with advanced algorithms, uncertainties remain. A conditionally approved status means that while the quantitative data looks good, there are still qualitative aspects or verification steps that need to be completed. For instance, an AI might flag an unusual income pattern, leading to a condition requiring further documentation to explain the anomaly. Or, for self-employed individuals, the algorithm might assess their stated income as plausible, but the lender still requires tax returns to legally verify it. This dynamic interplay between automated decision-making and human verification exemplifies intelligent innovation in action. It allows lenders to quickly identify viable candidates, reduce processing times, and minimize resources spent on applications unlikely to succeed, while still performing necessary risk mitigation before final approval.
Future Outlook: Hyper-Personalized Lending and Instant Approvals
The concept of conditional approval is likely to continue evolving with further technological advancements. The trajectory of FinTech innovation points towards even more streamlined processes, potentially leading to truly instant approvals for a wider range of applicants. This future state would involve:
- Enhanced Data Integration: With explicit user consent, lenders could access real-time financial data directly from banks, payroll providers, and other institutions. This would virtually eliminate the need for manual document submission and verification, making conditional approvals almost instantaneous, followed by rapid, automated final checks.
- Sophisticated Predictive Analytics: AI models will become even more adept at predicting future financial behavior, incorporating a broader spectrum of data points and contextual information. This could reduce the number of conditions required for many applicants, as the risk profile becomes clearer upfront.
- Blockchain for Verification: Distributed ledger technology (blockchain) could revolutionize identity and document verification. Self-sovereign digital identities and verifiable credentials stored on a blockchain could provide immutable and instantly verifiable proof of income, employment, and assets, making the conditional approval phase nearly seamless.
- Hyper-Personalized Loan Products: As AI understands individual financial profiles with greater granularity, loan products could become hyper-personalized, tailored to specific needs and risk tolerances, with dynamic pricing and terms, reducing the need for extensive back-and-forth during the approval process.
In this future, “conditionally approved” might shift from requiring active documentation submission to a status where conditions are verified automatically in the background, making the transition to full approval almost invisible to the borrower. However, the fundamental principle of verifying information before committing funds will remain a cornerstone of responsible lending, regardless of how advanced the underlying technology becomes.
In conclusion, a conditional loan approval is a clear indicator of progress in financial services, showcasing how technology has accelerated the initial assessment phase while maintaining necessary safeguards. It empowers borrowers with faster feedback and sets clear expectations for the final steps, representing a vital bridge between initial application and ultimate financial access in the tech-driven lending era.