
In the vast landscape of global financial technology, Visa and Mastercard stand as two titans, omnipresent symbols of modern commerce. While often perceived as direct competitors offering identical services, the nuanced differences between these two payment processing giants lie deep within their technological infrastructure, strategic innovations, and the evolving digital ecosystems they cultivate. Understanding these distinctions requires looking beyond the plastic in your wallet and delving into the intricate networks and cutting-edge technologies that empower billions of transactions daily.
The Core Technological Model: Payment Networks and Transaction Processing
At their fundamental level, both Visa and Mastercard operate as payment networks. This is a crucial distinction: they are not banks, nor do they issue credit cards directly. Instead, they serve as the intermediaries, the sophisticated technological backbone that facilitates communication and data exchange between issuing banks (the institutions that lend you money and provide the card) and acquiring banks (the banks that process payments for merchants). This intermediary role is where their technological prowess truly shines, enabling seamless, secure, and rapid global transactions.
Architecture of Global Transaction Processing
Both VisaNet and Mastercard’s network are proprietary, highly complex, and distributed systems designed for immense scale and redundancy. When you swipe, tap, or input your card details, the request travels through a multi-stage process:
- Point of Sale (POS) Interaction: The transaction begins at a merchant’s terminal, which captures the card data.
- Acquirer Processing: The merchant’s acquiring bank receives the transaction details and routes them to the appropriate payment network (Visa or Mastercard).
- Network Routing: This is where VisaNet or Mastercard’s network comes into play. Their advanced routing algorithms identify the issuing bank based on the card’s Bank Identification Number (BIN) and securely transmit the authorization request. This process involves sophisticated data packets, encryption, and real-time decision-making engines.
- Issuer Authorization: The issuing bank receives the request, verifies the cardholder’s account, checks for sufficient funds/credit, and assesses fraud risk using its own proprietary systems and often AI-driven analytics. A response (approved or declined) is generated.
- Network Communication Back: The authorization response is routed back through the Visa or Mastercard network to the acquiring bank and finally to the merchant’s POS terminal.
This entire sequence, involving multiple parties and vast geographical distances, typically occurs within mere seconds, a testament to the high-speed networking and processing power engineered by both companies. While the high-level steps are similar, the specific network architectures, routing protocols, and proprietary software that underpin VisaNet and Mastercard’s network represent distinct technological implementations.
Data Management and Network Infrastructure
The sheer volume of data processed by Visa and Mastercard is staggering. Each company manages data centers globally, interconnected by high-capacity, fault-tolerant networks. These infrastructures are designed not only for speed but also for resilience, ensuring continuous operation even in the face of outages or cyber threats. They employ advanced load balancing, automated failover mechanisms, and redundant systems across multiple regions to guarantee uptime and transaction integrity. The innovative use of distributed ledger technologies, though not fully blockchain in the cryptocurrency sense, is also being explored and integrated for enhanced transparency and efficiency in certain B2B applications, demonstrating their ongoing commitment to leveraging cutting-edge data management solutions.
Technological Innovations in Security and Fraud Prevention
Security is paramount in financial transactions, and both Visa and Mastercard have been at the forefront of developing and implementing innovative technologies to protect consumers and merchants from fraud. Their competitive drive for superior security has led to continuous advancements that have fundamentally reshaped digital payments.
EMV Chip Technology and Tokenization
The rollout of EMV (Europay, Mastercard, and Visa) chip technology was a monumental collaborative innovation in payment security. Unlike magnetic stripes, which carry static data, EMV chips generate unique cryptograms for each transaction, making card cloning significantly more difficult. Both networks actively drove the adoption of this standard globally.
Building on EMV, tokenization represents another leap in security, championed by both companies. When a card is registered for online purchases or digital wallets, the actual 16-digit Primary Account Number (PAN) is replaced with a unique, randomly generated “token.” This token is useless if intercepted, as it cannot be reverse-engineered to reveal the original card number. Visa’s Visa Token Service (VTS) and Mastercard’s Digital Enablement Service (MDES) are their respective proprietary platforms that enable this secure tokenization, allowing for secure storage of payment credentials on devices and in the cloud, thus drastically reducing the risk of data breaches.
AI and Machine Learning in Fraud Detection
Both Visa and Mastercard invest heavily in artificial intelligence and machine learning to combat fraud in real-time. Their systems analyze billions of data points—transaction patterns, geographic locations, merchant categories, purchase history, and device fingerprints—to identify anomalous behavior indicative of fraud.
- Visa’s Advanced Authorization (VAA): Leverages AI to analyze over 500 unique risk attributes in milliseconds, providing an authorization score to the issuing bank. This allows banks to make more informed decisions, reducing false positives while catching more fraudulent transactions.
- Mastercard’s Decision Intelligence™: Employs sophisticated AI algorithms to evaluate transactions, going beyond traditional rule-based systems to learn and adapt to new fraud patterns. It provides real-time scoring and insights to issuers, enhancing their ability to approve legitimate purchases and decline fraudulent ones.
These AI-driven systems are constantly learning and evolving, adapting to new fraud techniques and making the payment ecosystem increasingly secure. Their development represents a significant technological arms race against cybercriminals, where advanced algorithms provide a crucial advantage.
Contactless Payment Technologies
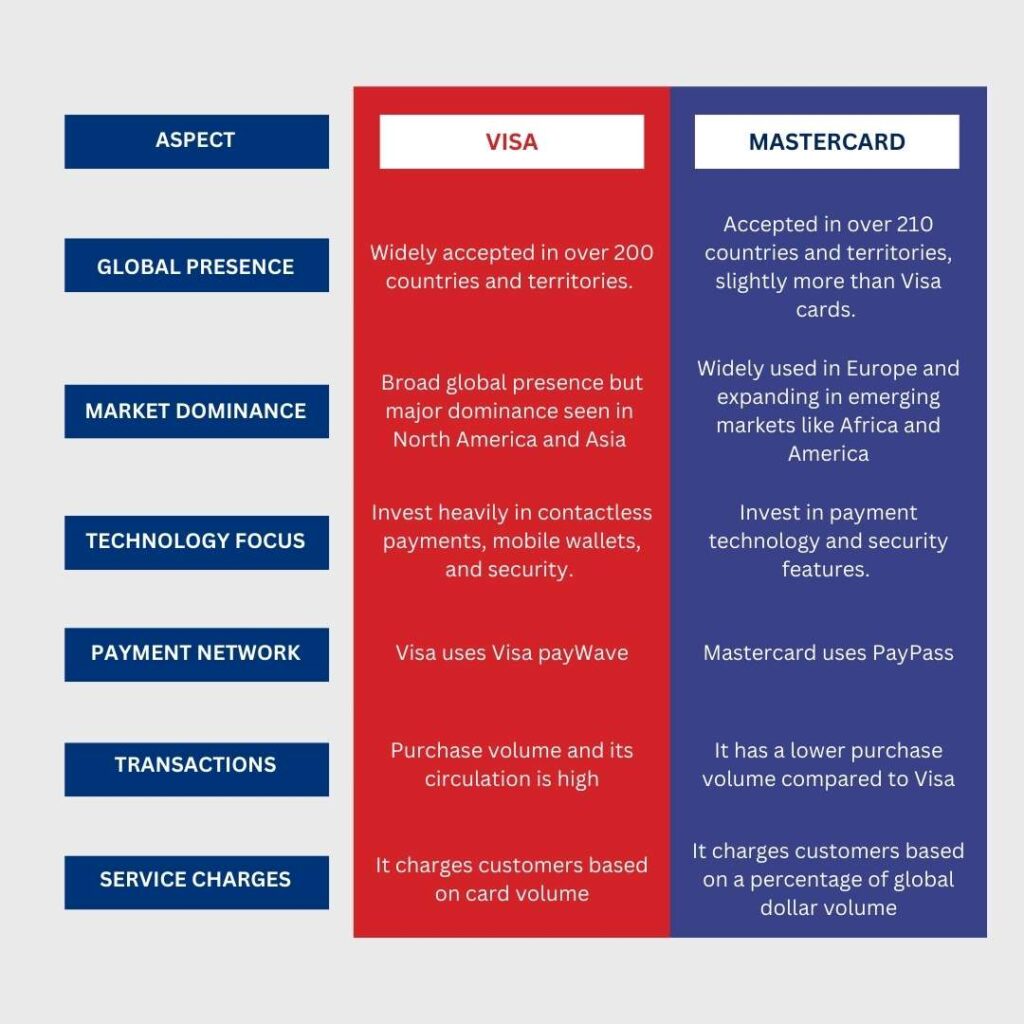
The widespread adoption of contactless payments (tap-to-pay) is another area where Visa and Mastercard have innovated through Near Field Communication (NFC) technology. While NFC is a standard, both companies have developed their proprietary frameworks (e.g., Visa payWave, Mastercard PayPass) that integrate with this technology, ensuring secure and rapid transactions with a simple tap. These systems encrypt data packets during transmission and often utilize tokenization, offering a seamless and secure alternative to traditional swipe or chip-and-PIN methods. Their continued investment in developing and standardizing these technologies has been critical to the global shift towards quicker, more convenient payment experiences.

The Ecosystem of Digital Payments and Financial Technology
Beyond direct card transactions, Visa and Mastercard are deeply embedded in the broader financial technology (Fintech) ecosystem. Their platforms and APIs are central to a myriad of digital payment solutions, powering innovation across banking, e-commerce, and mobile payments.
API Integration and Fintech Partnerships
Both companies offer extensive developer platforms with APIs (Application Programming Interfaces) that allow third-party developers, fintech startups, and banks to integrate their payment functionalities into new applications and services. This open approach fosters innovation:
- Visa Developer Platform: Provides access to a wide range of APIs for payment processing, data analytics, loyalty programs, and risk management. This enables developers to build new payment solutions, from embedded finance to innovative digital wallets.
- Mastercard Developers: Offers similar API access, focusing on areas like open banking, payment processing, data services, and security. Their emphasis on open banking, in particular, showcases a strategic move towards data-driven financial services, allowing consumers to securely share their financial data with third parties to access personalized products.
These platforms are not just technical interfaces; they represent a strategic commitment to being foundational technology providers for the next generation of financial services.
Blockchain and Future Payment Systems
While not directly using public blockchains for their core payment processing, both Visa and Mastercard are actively exploring and investing in blockchain technology for specific applications.
- Visa B2B Connect: A non-card-based network leveraging distributed ledger technology (DLT) to facilitate high-value international payments between banks. It aims to streamline cross-border transactions, reducing settlement times and increasing transparency.
- Mastercard’s blockchain patents and partnerships: Mastercard has numerous patents related to blockchain technology and has partnered with various blockchain companies to explore use cases in supply chain finance, digital identity verification, and central bank digital currencies (CBDCs).
These initiatives highlight their strategic foresight in leveraging nascent technologies to enhance efficiency, reduce costs, and improve security in specific segments of the global payment landscape, rather than merely replacing their existing, highly robust core networks.
Data Analytics for Personalized Services
The vast amounts of transaction data collected by Visa and Mastercard, processed through their advanced analytical platforms, provide invaluable insights. While adhering strictly to privacy regulations, these insights enable them to offer sophisticated analytical tools to their issuing banks and merchants. This data allows for:
- Targeted Loyalty Programs: Issuers can design more effective rewards programs based on cardholder spending patterns.
- Merchant Insights: Businesses can understand customer demographics and purchasing behavior to optimize sales and marketing strategies.
- Risk Management Optimization: Enhanced data analytics further refines fraud detection and credit risk assessment.
This utilization of big data and advanced analytics transforms raw transaction information into actionable intelligence, driving innovation in customer experience and business efficiency across the financial ecosystem.
Competitive Landscape and Market Penetration Driven by Technology
While both Visa and Mastercard operate globally and offer similar functionalities to consumers, their distinct technological strategies and partnerships influence their competitive positioning and market penetration. The subtle differences in their network efficiencies, security innovations, and partnership ecosystems contribute to their global acceptance and growth trajectories.
Global Reach and Acceptance
Both networks boast immense global acceptance. However, subtle differences exist in their market strength in various regions, often influenced by historical market entry, strategic alliances, and specific technological adaptations for local payment habits. For instance, one network might have a stronger presence in certain developing markets due to earlier investment in localized payment solutions or specific mobile payment integrations. Their ongoing technological investments in supporting diverse payment methods—from traditional cards to QR codes and mobile wallets—are critical for maintaining and expanding this global reach.
Strategic Partnerships and Digital Wallets
The competitive battleground has increasingly shifted to digital wallets (e.g., Apple Pay, Google Pay, Samsung Pay) and embedded payment solutions. Both Visa and Mastercard actively partner with technology giants and fintech innovators to ensure their networks are the preferred rails for these emerging payment methods. Their tokenization services (VTS and MDES) are foundational to the security and seamlessness of these digital wallet integrations. The continuous innovation in their underlying technology allows them to adapt quickly to new form factors and digital platforms, ensuring their relevance in an increasingly cashless and mobile-first world.
Innovation in Commercial and Business Solutions
Beyond consumer credit cards, both companies offer a suite of technological solutions for businesses. This includes commercial cards, expense management platforms, and B2B payment services. They are investing in innovations such as virtual cards, which generate single-use card numbers for specific transactions, enhancing security and control for corporate spending. Their platforms also offer sophisticated data reporting and integration capabilities, helping businesses streamline operations and manage financial flows more efficiently, showcasing their broader impact as enterprise technology providers.
The Evolving Role in a Cashless Society
Ultimately, the differences between Visa and Mastercard, while subtle to the average consumer, are profound from a technological and strategic standpoint. Both are relentless innovators, constantly pushing the boundaries of what’s possible in payment processing, security, and financial inclusion. Their ongoing investment in AI, DLT, API platforms, and seamless user experiences underscores their shared mission to facilitate the global shift towards a cashless society, making transactions faster, more secure, and universally accessible. Their technological competition ultimately benefits consumers and businesses alike, driving an ever-evolving landscape of financial innovation.