
Understanding Required Minimum Distributions (RMDs) in the Digital Age
Navigating the complexities of retirement savings is a critical component of long-term financial planning, and for many, understanding Required Minimum Distributions (RMDs) from tax-deferred accounts like 401(k)s is paramount. RMDs represent the minimum amounts that account holders must withdraw from their traditional IRAs, 401(k)s, 403(b)s, and other employer-sponsored retirement plans once they reach a specific age. The primary purpose behind these mandatory withdrawals is for the IRS to begin collecting tax revenue on funds that have grown tax-deferred for decades. Failure to take an RMD, or withdrawing less than the required amount, can result in significant penalties, historically up to 50% of the undistributed amount, though the SECURE Act 2.0 has reduced this to 25%, and potentially 10% if corrected promptly.
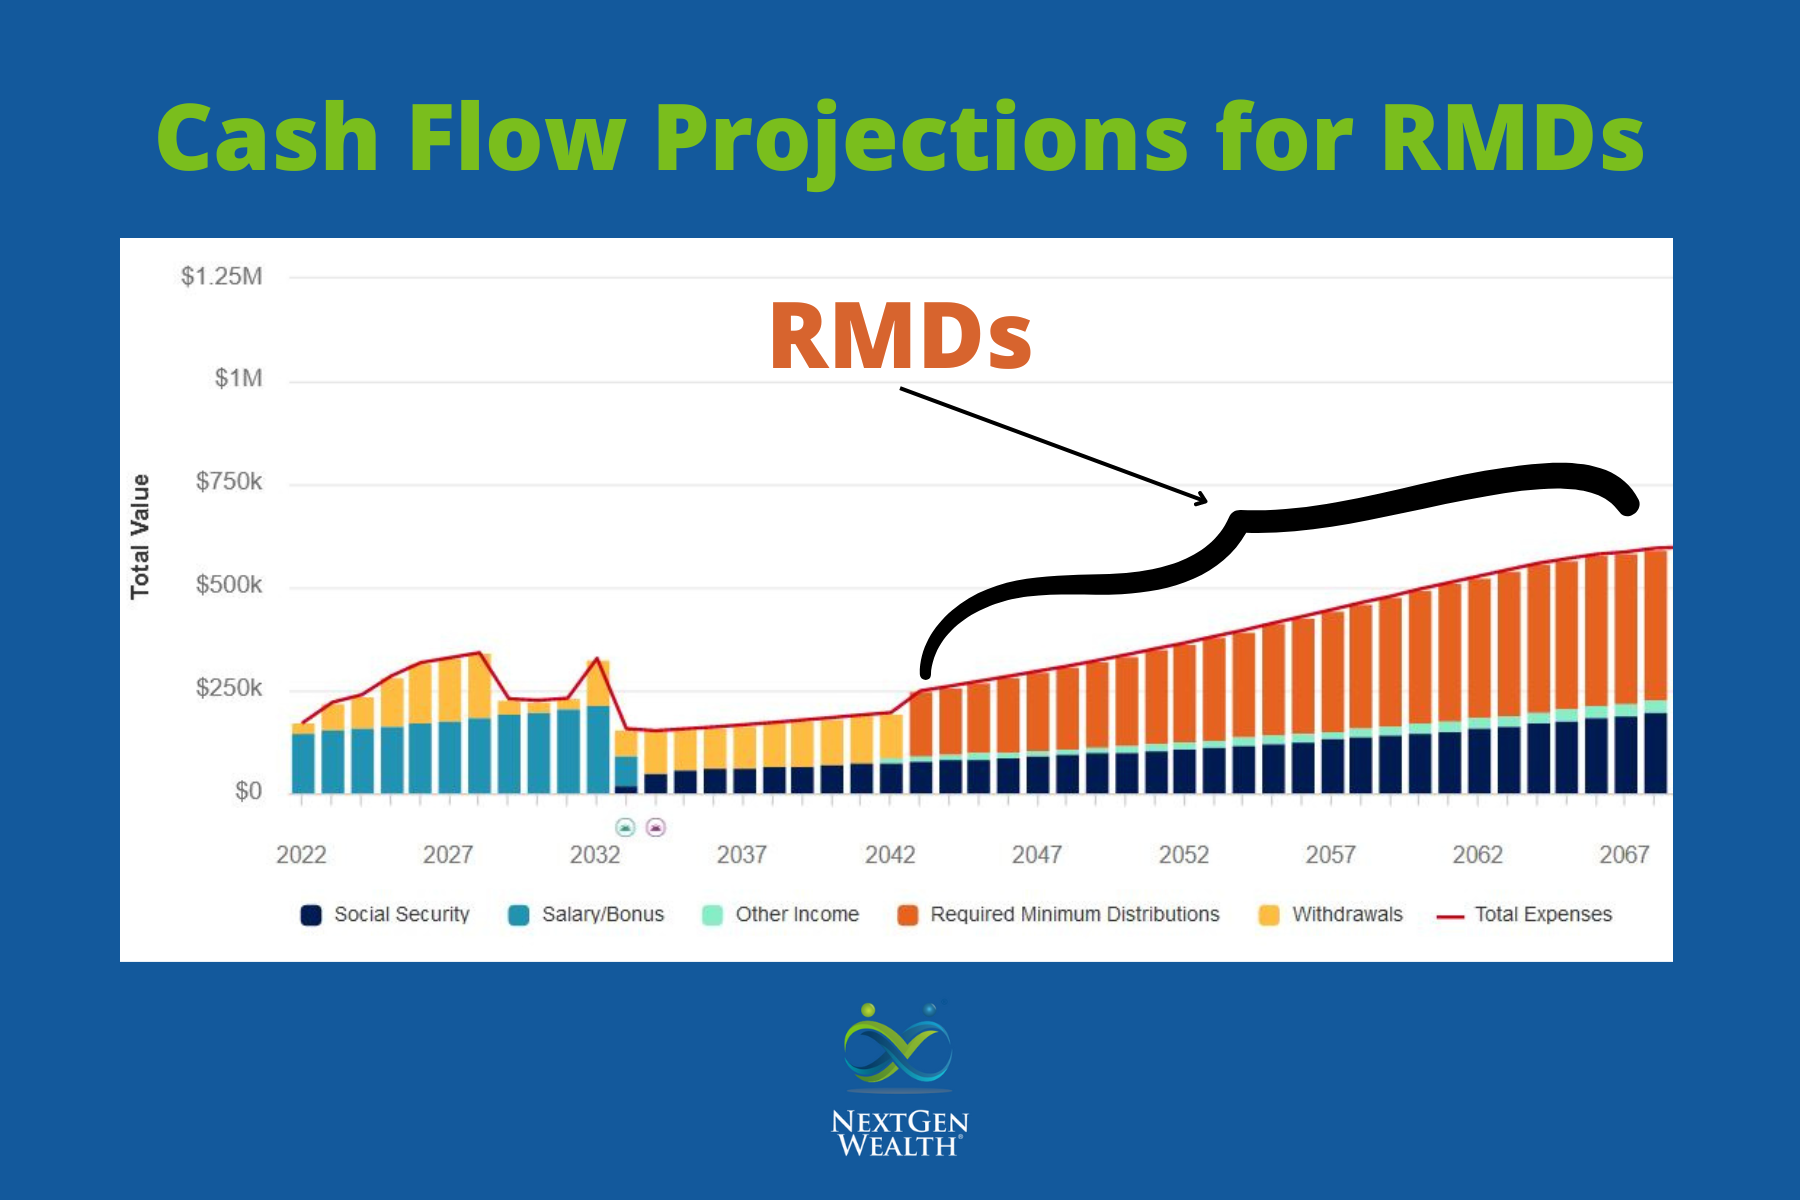
The legislative landscape governing RMDs has seen notable shifts in recent years, particularly with the passage of the SECURE Act in 2019 and SECURE Act 2.0 in 2022. Historically, RMDs typically began at age 70½. The SECURE Act pushed this age to 72 for those who turned 70½ after December 31, 2019. Building on this, SECURE Act 2.0 further raised the RMD age to 73 for individuals who turn 72 after December 31, 2022, and will increase it again to 75 for those who turn 74 after December 31, 2032. These changes underscore the dynamic nature of retirement planning and the need for adaptable financial strategies. For today’s retirees and those nearing retirement, staying abreast of these evolving rules is not just about compliance, but about optimizing their financial future, minimizing tax liabilities, and ensuring their savings align with their long-term goals.
The Core Concept of RMDs
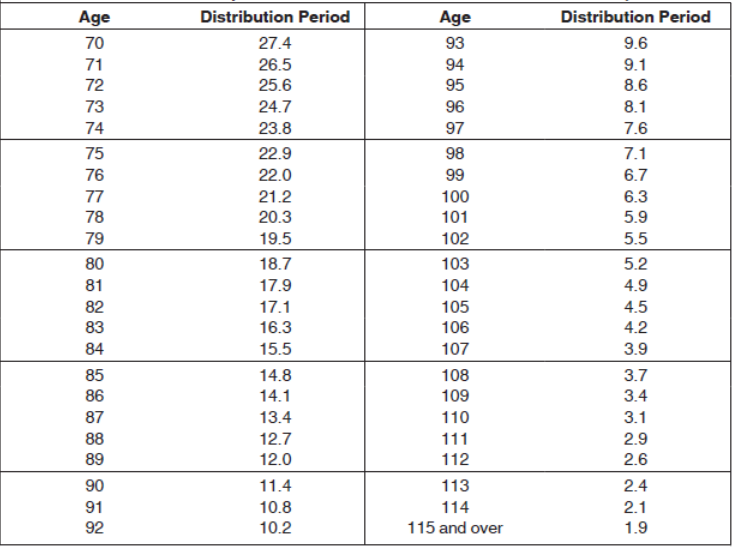
At its heart, an RMD is a calculated annual withdrawal designed to deplete a retirement account over an individual’s expected lifespan, preventing indefinite tax deferral. The calculation generally involves dividing the account balance as of December 31 of the previous year by a life expectancy factor provided by the IRS, typically found in the Uniform Lifetime Table. For example, if an individual’s account balance was $500,000 at the end of the prior year and their life expectancy factor from the Uniform Lifetime Table is 27.4, their RMD for the current year would be approximately $18,248. The complexity intensifies when dealing with multiple retirement accounts, inherited IRAs, or beneficiaries subject to different rules (e.g., the 10-year rule for non-eligible designated beneficiaries). Each account generally requires its own RMD calculation, though for IRAs, the total RMD can often be taken from any single IRA. This nuanced framework necessitates precision and up-to-date information to avoid costly errors, making technological assistance increasingly indispensable.
Leveraging Financial Technology for RMD Compliance
In an era defined by digital transformation, financial technology (FinTech) has emerged as a powerful ally for individuals and financial advisors alike in managing RMDs. The days of manually tracking account balances, consulting IRS tables, and setting calendar reminders are rapidly fading, replaced by sophisticated digital tools that streamline the entire process. These innovations not only enhance accuracy and compliance but also empower individuals with greater control and insight into their retirement assets.
Automated RMD Calculators and Platforms
Modern FinTech platforms offer automated RMD calculators that pull real-time account data directly from linked retirement accounts. These tools instantly apply the correct life expectancy factors based on the account holder’s age, incorporating the latest legislative changes (e.g., SECURE Act 2.0 adjustments to RMD age). Beyond simple calculation, many platforms can model future RMDs, projecting potential distributions for years to come. This foresight is crucial for long-term tax planning, allowing users to anticipate future income streams and adjust other financial strategies accordingly. The integration of these calculators into broader financial planning software provides a holistic view, where RMDs are not just a compliance task but an integral part of a comprehensive financial ecosystem.
Digital Alerts and Reminders
One of the most common reasons for RMD non-compliance is simply forgetting to take the distribution or miscalculating the deadline. FinTech solutions mitigate this risk through proactive digital alerts and reminders. Personalized dashboards prominently display RMD requirements, progress toward fulfilling them, and upcoming deadlines. Automated email or SMS notifications can be configured to prompt users well in advance of the December 31 deadline (or April 1 for the first RMD), ensuring timely action. This shift from reactive crisis management to proactive compliance significantly reduces stress and the likelihood of incurring penalties.
Robo-Advisors and RMD Integration
Robo-advisors, known for their algorithmic portfolio management, are increasingly incorporating RMD strategies into their automated services. These platforms can be programmed to automatically disburse RMDs, selecting assets to sell in a tax-efficient manner (e.g., minimizing capital gains if applicable) and depositing funds into a linked bank account. For investors seeking a hands-off approach, this integration offers a seamless way to remain compliant while their portfolio continues to be managed strategically. Some advanced robo-advisors even consider RMDs when rebalancing portfolios, ensuring that withdrawal strategies align with overall investment goals without disrupting the long-term growth trajectory.
Data Aggregation and Holistic Views
For individuals with multiple 401(k)s, IRAs, and other retirement accounts from various custodians, calculating and tracking RMDs can be a monumental task. Data aggregation technology solves this by consolidating information from all linked financial accounts into a single, comprehensive dashboard. This unified view allows individuals and their advisors to see the total RMD obligation across all accounts, track distributions, and strategize which accounts to draw from for optimal tax efficiency. This holistic approach simplifies complex financial landscapes, providing clarity and control over diverse retirement portfolios.
Innovative Strategies for RMD Management and Tax Efficiency
Beyond basic compliance, modern technology empowers individuals to employ sophisticated strategies for RMD management that can significantly enhance tax efficiency and support broader financial goals. These innovative approaches leverage digital tools for modeling, tracking, and executing complex financial maneuvers that would be cumbersome or impossible manually.

Qualified Charitable Distributions (QCDs) through Digital Tools
For individuals aged 70½ or older, a Qualified Charitable Distribution (QCD) offers a powerful tax-efficient way to satisfy all or part of an RMD directly from an IRA to an eligible charity. While 401(k)s are not eligible for QCDs, rolling a 401(k) into an IRA can enable this strategy. Financial software can help identify eligibility, track the amount of QCDs made, and ensure they are properly reported, offering a seamless way to fulfill philanthropic goals while reducing taxable income by satisfying RMDs without the distribution being counted as income. Digital platforms can even facilitate the direct transfer to the charity, automating what was once a multi-step process.
Strategic Roth Conversions and Technology’s Role
Executing strategic Roth conversions can be a powerful tool for reducing future RMDs, especially for those who anticipate being in a higher tax bracket in retirement or want to leave a tax-free legacy to heirs. Converting pre-tax 401(k) or IRA funds to a Roth account means paying taxes upfront, but all qualified distributions from the Roth account in retirement are tax-free and not subject to RMDs for the original owner. Advanced financial modeling software allows individuals and advisors to project the long-term tax implications of various conversion amounts and timings. These tools can analyze current and future tax brackets, investment growth scenarios, and RMD obligations to determine the optimal conversion strategy, maximizing after-tax wealth over decades.
In-Kind Distributions and Portfolio Optimization
While most RMDs are taken as cash, it is often possible to satisfy an RMD by distributing securities “in-kind” directly from the retirement account. This can be a strategic move, particularly with highly appreciated assets that the account holder wishes to retain outside of the retirement account. Technology assists here by enabling advanced portfolio analysis, helping to identify which assets might be suitable for in-kind distribution, considering their tax basis and potential for future growth. Automated systems can manage the transfer process, ensuring accurate valuation and compliance. This strategy can be particularly useful in managing asset allocation or moving specific investments into a taxable brokerage account without incurring immediate sales and re-purchase fees.
Beneficiary RMD Planning with Tech
The rules for RMDs for inherited retirement accounts can be incredibly complex, especially after the SECURE Act introduced the 10-year rule for most non-spouse beneficiaries. This rule generally requires the inherited account to be fully distributed by the end of the tenth year following the original owner’s death. Technology is invaluable for beneficiaries in understanding these specific rules, calculating their RMD obligations (if applicable under the 10-year rule for non-eligible designated beneficiaries who inherited before 2020 or for eligible designated beneficiaries), and planning distributions to optimize tax outcomes. Specialized software can model various withdrawal scenarios over the 10-year period, helping beneficiaries navigate the complexities and avoid inadvertent penalties, ensuring they maximize the inherited wealth.
The Future of 401k Distributions: Automation and AI
The trajectory of FinTech suggests an even more sophisticated future for 401(k) distributions, where automation and artificial intelligence (AI) will play increasingly pivotal roles. These advancements promise to transform RMD management from a periodic compliance task into a continuously optimized, personalized, and seamlessly integrated component of an individual’s financial life.
Predictive Analytics for Tax Planning
AI-driven predictive analytics will revolutionize RMD tax planning. By analyzing vast datasets of individual financial history, market trends, and legislative patterns, AI models will be able to forecast future income streams, anticipated tax brackets, and RMD obligations with unprecedented accuracy. This capability will allow financial platforms to recommend optimal withdrawal strategies years in advance, suggesting when to take larger distributions, when to initiate Roth conversions, or when to utilize other tax-advantaged strategies, all tailored to minimize lifetime tax burdens and align with the individual’s evolving financial landscape. This proactive insight will move beyond simple calculations to genuine strategic foresight.
Personalized RMD Pathways
Machine learning algorithms will enable the creation of highly personalized RMD pathways. These algorithms will consider not just an individual’s age and account balance, but also their unique financial situation, risk tolerance, spending habits, health status, and life goals. By synthesizing this diverse data, AI can recommend the most suitable distribution strategy – whether it’s optimizing for lowest current tax, preserving capital for future needs, or maximizing legacy for heirs. For instance, an AI might suggest a different RMD strategy for someone with significant other income versus someone relying solely on their 401(k), or for someone planning a large expense in retirement versus someone focused on long-term care planning.
Blockchain for Enhanced Security and Transparency
While still in nascent stages for mainstream financial applications, blockchain technology holds promise for enhancing the security and transparency of retirement distributions. Imagine immutable, decentralized records of all RMD calculations and distributions, verifiable by both account holders and regulatory bodies. This could reduce administrative burdens, minimize disputes over compliance, and provide an unparalleled level of auditability. Smart contracts on a blockchain could potentially automate the execution of RMDs under predefined conditions, ensuring that distributions are always taken on time and in accordance with the rules, further streamlining the process and reducing human error.
Regulatory Intelligence and Adaptive Systems
The continuous evolution of tax laws, as seen with the SECURE Act and SECURE Act 2.0, highlights the need for financial systems that can adapt instantly. Future AI-powered platforms will incorporate advanced regulatory intelligence, continuously monitoring legislative changes and immediately updating RMD calculations, compliance checks, and strategic recommendations. These adaptive systems will provide proactive advice, alerting users to new opportunities or risks arising from legal amendments, and automatically adjusting their personalized RMD plans. This ensures that retirement planning remains resilient and optimized, regardless of shifting policy landscapes, providing peace of mind in a dynamic financial world.