
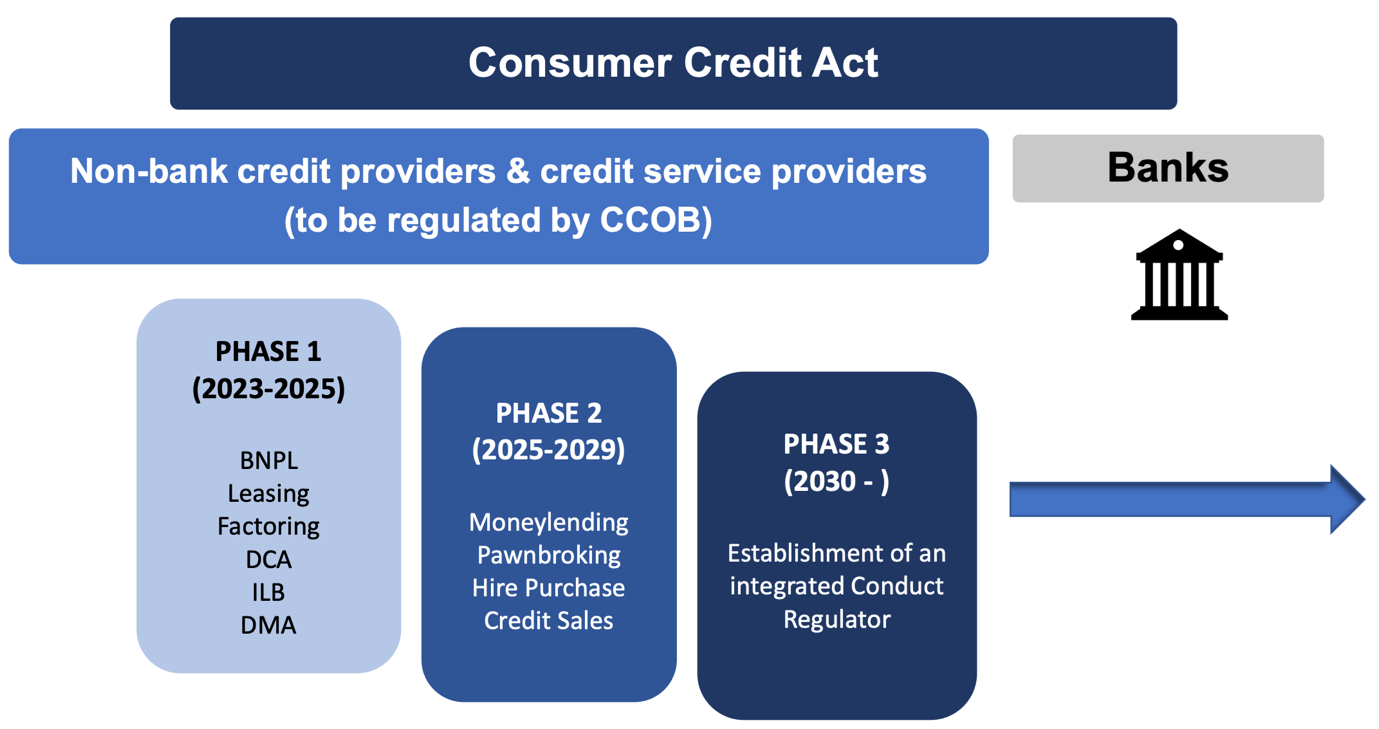
The term “Consumer Credit Act” fundamentally refers to legislative frameworks designed to regulate credit agreements between lenders and consumers, ensuring fairness, transparency, and protection for individuals engaging in various forms of borrowing. While the specific provisions vary by jurisdiction, the core purpose remains consistent: to establish rules for credit card agreements, loans, hire purchase, and other forms of finance, safeguarding consumers from predatory practices and ensuring they are fully informed about their financial commitments. In the dynamic world of drone technology, understanding the implications of such an act, not as a static legal document, but as a dynamic framework influencing technological adoption and innovation, is crucial for both businesses and enthusiasts alike. This is particularly true when considering how cutting-edge drone technology, often a significant investment, becomes accessible to the broader market through various credit mechanisms, underpinned by robust technological infrastructure and innovative financial solutions.

The Foundational Role of Consumer Credit in Technology Ecosystems
At its core, a Consumer Credit Act serves as the bedrock for consumer trust in financial markets. It mandates clear disclosure of terms, provides rights for dispute resolution, and sets limits on interest rates and charges. Without such protections, the widespread adoption of new and expensive technologies, such as advanced drones, would be significantly hampered. For many, acquiring a high-quality drone for professional use, aerial filmmaking, or even serious hobby flying represents a substantial financial commitment. Credit facilities, regulated by acts like the Consumer Credit Act, bridge the gap between aspiration and ownership, making sophisticated drone technology accessible to a wider demographic.
In the context of the rapidly evolving drone industry, the principles enshrined in consumer credit legislation are not merely bureaucratic hurdles but essential enablers of growth. They ensure that consumers purchasing drones on credit are protected, fostering a predictable and fair market environment. This predictability, in turn, encourages investment in drone technology and related services, knowing that the consumer base has reliable pathways to financing their purchases.
Fueling Drone Adoption Through Accessible Financing
The drone market encompasses a vast array of products, from entry-level recreational quadcopters to highly specialized industrial UAVs equipped with advanced sensors for mapping, inspection, or delivery. The cost of these devices can range from a few hundred to tens of thousands of dollars, making outright purchase challenging for many individuals and small businesses. This is where consumer credit, facilitated by technologies and governed by acts, plays a pivotal role.
Accessible financing options – including personal loans, credit cards, manufacturer-specific finance plans, and lease-to-own programs – are critical for making drones a viable tool for a broader audience. A Consumer Credit Act ensures that these financing avenues are transparent and fair. For instance, a small startup specializing in aerial photography may rely on a credit facility to acquire a high-resolution camera drone with a stabilized gimbal. Similarly, an agricultural business might use credit to invest in a drone for crop monitoring or precision spraying. The availability of structured and protected credit facilities, driven by modern financial technology, directly correlates with the rate of drone technology adoption. As drones become more sophisticated, integrating AI for autonomous flight, advanced navigation, and complex payload management, their price points often rise. Consequently, the mechanisms of consumer credit become even more indispensable for driving market penetration and innovation at the consumer level.
AI, Data Analytics, and Responsible Lending in the Drone Sector
The intersection of the Consumer Credit Act’s principles and cutting-edge “Tech & Innovation” is particularly evident in the field of credit assessment itself. Artificial intelligence and advanced data analytics are revolutionizing how lenders evaluate creditworthiness, making the process faster, more accurate, and increasingly personalized. These technologies can process vast amounts of data – beyond traditional credit scores – to predict a borrower’s ability to repay, often in real-time.
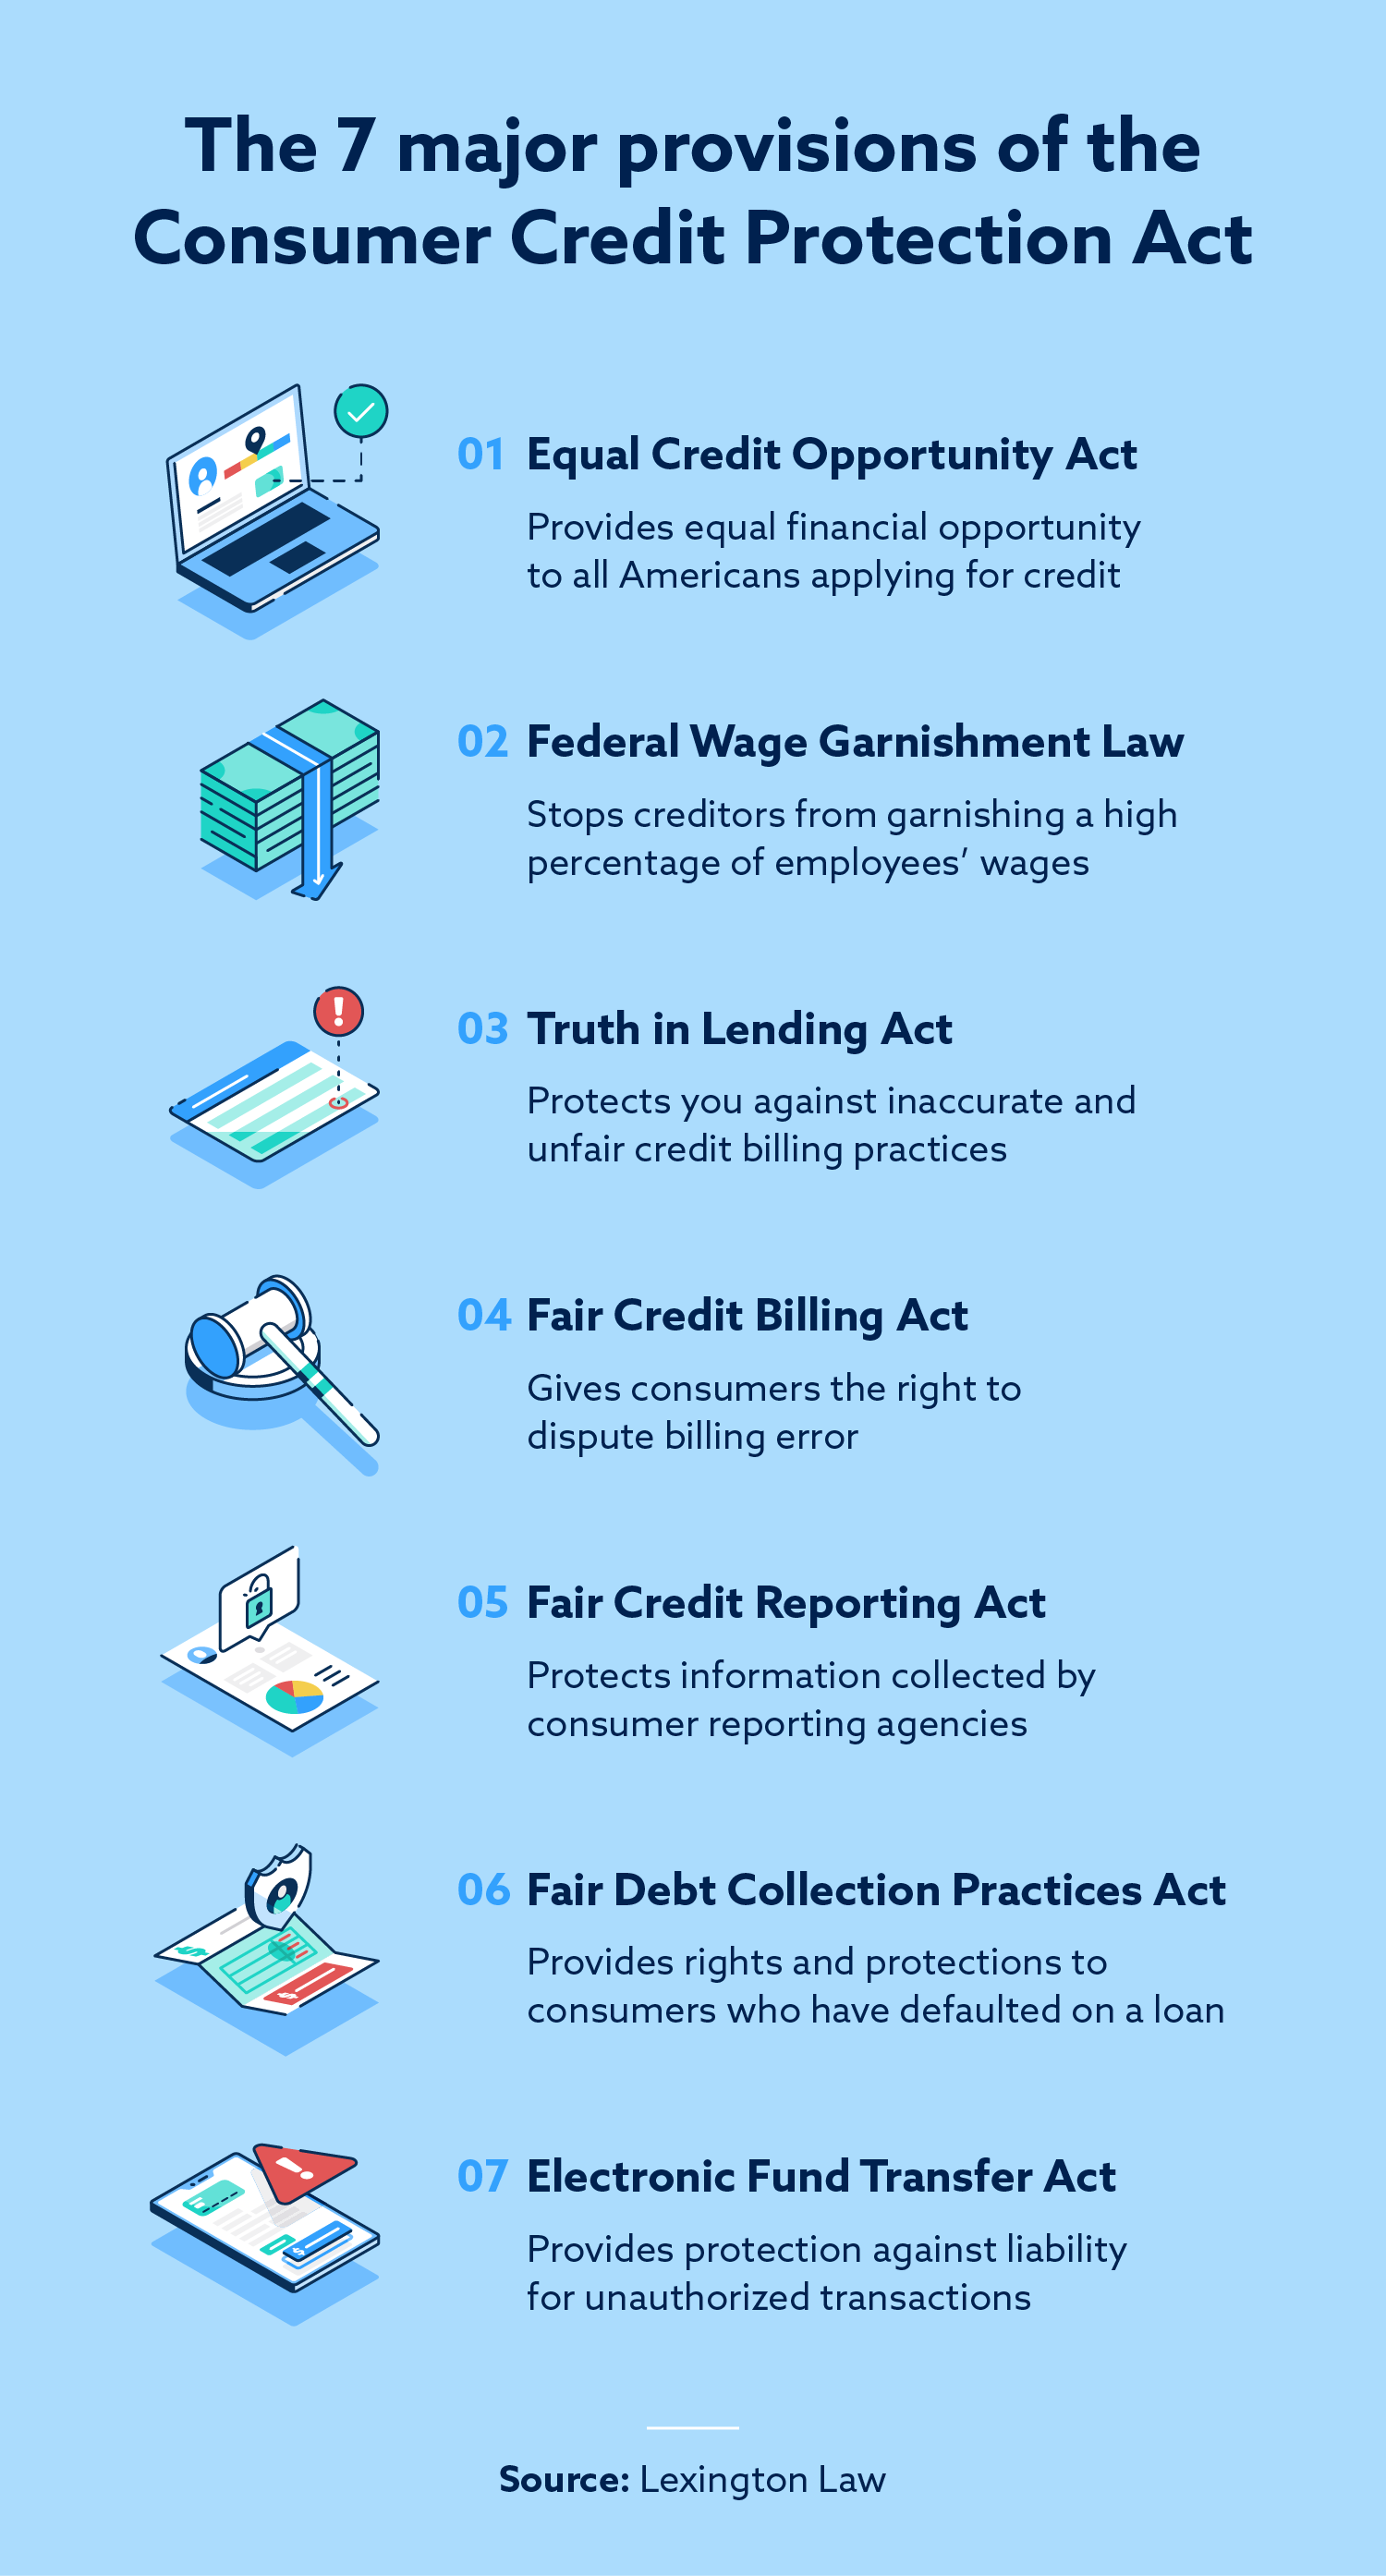
For the drone sector, this means innovative approaches to financing drone purchases and services. Imagine an AI-powered credit platform that can quickly assess the financial health of a freelance drone pilot looking to upgrade their equipment, or a small business seeking to expand its fleet of inspection drones. These systems can factor in diverse data points, from past payment behaviors to business revenue forecasts, providing rapid approval decisions. However, the deployment of such powerful AI tools must operate within the confines of a Consumer Credit Act. The act’s provisions regarding fairness, non-discrimination, data privacy, and the right to appeal credit decisions are paramount. “Tech & Innovation” here involves not only developing sophisticated AI algorithms but also ensuring these algorithms are transparent, auditable, and compliant with consumer protection laws. The challenge lies in leveraging AI for efficient and inclusive credit access for drone consumers, without inadvertently creating biased systems or compromising individual privacy, all under the watchful eye of consumer protection legislation.
Navigating Regulatory Frameworks for Drone-Related Financial Innovation
The regulatory landscape surrounding consumer credit directly impacts how financial innovations can emerge and thrive within specialized markets like drones. A Consumer Credit Act sets the boundaries for financial products and services, compelling innovators to embed compliance into the very design of their technological solutions. For instance, any fintech company developing a specialized lending platform for drone purchases must ensure its algorithms, data handling, and communication protocols adhere to the disclosure requirements, fair practices, and dispute resolution mechanisms mandated by the act.
This isn’t just about avoiding penalties; it’s about building trust in novel financial instruments that support drone tech. Digital lending platforms, mobile payment systems, and blockchain-enabled financing solutions for drones all operate within this regulatory environment. The “Tech & Innovation” in this domain involves creating robust, scalable, and secure systems that can navigate complex regulatory demands while simultaneously offering seamless and user-friendly experiences for consumers looking to finance their drone ventures.
Digital Compliance and Cybersecurity in Drone Finance
Meeting the stringent requirements of a Consumer Credit Act in a digital age necessitates significant technological investment in compliance and cybersecurity. Lenders and financial service providers catering to drone enthusiasts and businesses must implement advanced data encryption to protect sensitive personal and financial information. Secure digital transaction processing, fraud detection systems (often AI-enhanced), and robust identity verification protocols are no longer optional but fundamental necessities.
Consider a company offering subscription models for access to a fleet of advanced mapping drones or specialized drone software. Each subscription typically involves credit checks and ongoing payment arrangements, all governed by the principles of consumer credit. The “Tech & Innovation” here manifests in developing platforms that automate compliance checks, provide real-time reporting on loan portfolios to regulators, and ensure immutable audit trails. Furthermore, the threat of cyberattacks demands continuous innovation in cybersecurity measures to safeguard consumer data and maintain the integrity of financial transactions related to drone technology. This includes everything from secure cloud infrastructure to multi-factor authentication for financial accounts linked to drone purchases, ensuring that the digital pathways for credit are as secure as the regulatory framework intends them to be.
Emerging Business Models and Credit Challenges for Drone Services
The rapid evolution of drone technology is giving rise to entirely new business models that challenge traditional credit frameworks. Concepts like “Drone-as-a-Service” (DaaS), where consumers or businesses pay for drone capabilities (e.g., data collection, inspection, delivery) rather than owning the hardware, introduce new complexities for consumer credit acts. These services often involve recurring payments, tiered subscriptions, or usage-based billing, requiring flexible and technologically sophisticated credit management systems.
For example, a precision agriculture firm might subscribe to a DaaS model for autonomous crop analysis, with payments tied to acreage or flight hours. How do the protections of a Consumer Credit Act apply to such service agreements, especially when innovative pricing models are involved? “Tech & Innovation” becomes crucial in designing flexible credit solutions that can accommodate these dynamic service models, ensuring transparency and consumer protection while facilitating innovation. This also includes developing robust platforms for tracking usage, managing payments, and automating contractual adjustments – all while remaining compliant with the core tenets of fair lending and consumer rights. The need for adaptive credit solutions is critical for enabling these innovative drone service models to scale and thrive.
The Future Landscape: Credit, Innovation, and Autonomous Systems
Looking ahead, the interplay between Consumer Credit Acts and “Tech & Innovation” in the drone sector will only intensify. As drone capabilities expand into fully autonomous operations, urban air mobility, and ubiquitous delivery services, new financial ecosystems will emerge. Imagine a future where autonomous drones fulfill micro-delivery orders, potentially on a pay-per-use basis that involves micro-credit extensions managed by AI. Or where credit risk assessment for businesses in sectors like agriculture or construction might incorporate real-time data from their drone operations.
The fundamental principles of consumer protection and fair lending enshrined in acts will remain vital, but the methods of their application will evolve dramatically through technology. “Tech & Innovation” will continue to push the boundaries of what’s possible in drone technology, but its widespread adoption and impact on consumers will always be tethered to the underlying financial mechanisms. A robust and adaptable Consumer Credit Act, supported by innovative financial technologies, is therefore not just a regulatory necessity but a strategic imperative. It provides the essential framework for trust and accessibility, ensuring that the marvels of drone innovation can reach every consumer and business, fueling a future where advanced aerial technology is not only cutting-edge but also equitably accessible.