
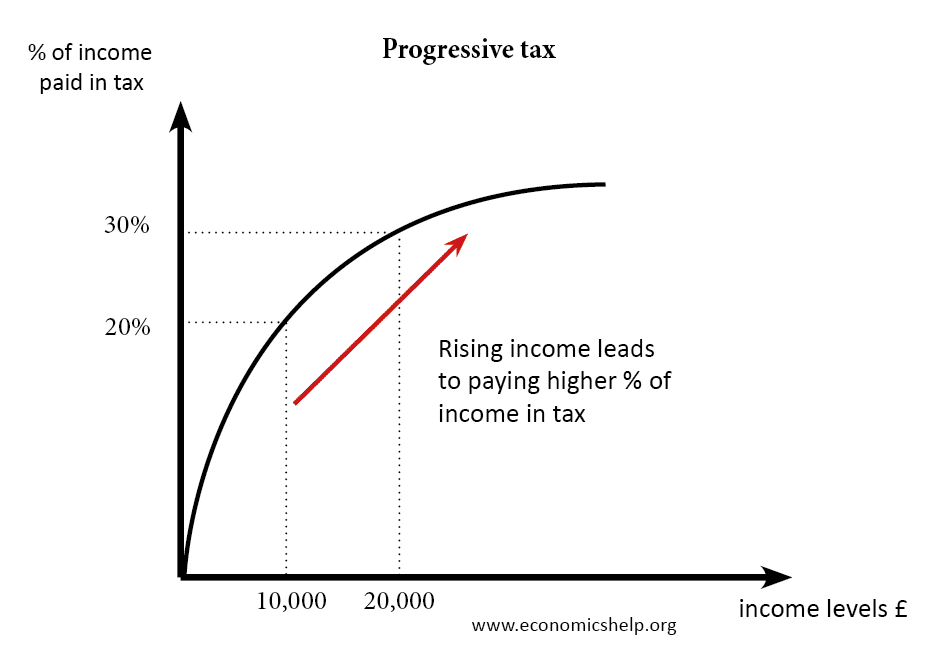
A progressive tax system is a tax structure where the tax rate increases as the taxable amount – typically income or wealth – increases. This means that individuals or entities with higher incomes pay a larger percentage of their earnings in taxes compared to those with lower incomes. The fundamental principle behind a progressive tax system is often rooted in the concept of ability-to-pay taxation, aiming to achieve a more equitable distribution of the tax burden across different income strata within a society.
Core Principles and Mechanics
The essence of a progressive tax system lies in its variable tax rates. Instead of a flat tax rate applied uniformly to all income levels, a progressive system utilizes tax brackets. Each bracket corresponds to a specific range of income and is associated with a different, usually higher, marginal tax rate.
Understanding Tax Brackets and Marginal Rates
In a progressive system, income is divided into several tiers, or brackets. For instance, the first portion of income (e.g., up to $10,000) might be taxed at 10%, the next portion (e.g., from $10,001 to $40,000) at 15%, and so on, with higher brackets facing incrementally higher rates. It’s crucial to understand that these rates are marginal. This means that only the income falling within a particular bracket is taxed at that bracket’s specific rate, not the entire income.
For example, consider a simplified system with two brackets:
- 0-$50,000 taxed at 10%
- Above $50,000 taxed at 20%
An individual earning $60,000 would not pay 20% on their entire income. Instead, they would pay 10% on the first $50,000 ($5,000) and 20% on the remaining $10,000 ($2,000), for a total tax liability of $7,000. Their effective tax rate (total tax paid divided by total income) would be $7,000 / $60,000 = approximately 11.67%, which is lower than their highest marginal rate. This distinction is vital for comprehending how progressive tax systems operate without penalizing individuals disproportionately as they cross into a higher bracket.
Average vs. Marginal Tax Rates
The marginal tax rate is the tax rate applied to the last dollar of income earned. It’s the rate relevant to individuals considering earning additional income, as it determines how much of that extra income they will keep after taxes. The average tax rate, on the other hand, is the total tax paid divided by total taxable income. In a truly progressive system, an individual’s average tax rate will always be lower than or equal to their highest marginal tax rate, and it will increase as their income increases. This ensures that a higher-income earner not only pays more in absolute terms but also a higher percentage of their income compared to a lower-income earner.
Objectives and Economic Implications
The primary goals of implementing a progressive tax system are often multifaceted, aiming to achieve various economic and social outcomes.
Income Redistribution and Equity
One of the most frequently cited objectives is income redistribution. By taxing higher earners at a greater percentage, a progressive system can theoretically reduce income inequality. The revenue generated from higher tax brackets can then be used to fund public services, social safety nets, and welfare programs that disproportionately benefit lower-income segments of the population. This mechanism is seen by proponents as a tool for fostering greater economic fairness and social cohesion.
Economic Stabilization and Demand Management
Progressive taxation can also play a role in economic stabilization. During periods of economic growth and high employment, higher-income individuals tend to save a larger portion of their income. A progressive tax system can capture some of this excess income, potentially reducing inflationary pressures. Conversely, during economic downturns, tax cuts or expansions of social programs funded by progressive taxation can inject spending power into the economy, particularly among those with a higher marginal propensity to consume, thereby stimulating demand and aiding recovery.
Fiscal Sustainability and Revenue Generation
While not its sole purpose, progressive taxation is a significant source of government revenue. By tapping into the larger incomes and wealth of a nation’s most affluent citizens, governments can fund essential public services, infrastructure projects, defense, education, healthcare, and research. The argument is that those with the greatest financial capacity should contribute more to the collective good, ensuring fiscal sustainability for public expenditures.
Criticisms and Debates
Despite its widespread adoption and perceived benefits, progressive tax systems are not without their critics and are often the subject of intense economic and political debate.
Disincentives to Work and Invest
A common criticism is that high marginal tax rates, particularly at the top income brackets, can create disincentives for individuals to work harder, innovate, or invest. The argument is that if a significant portion of additional earnings is taken by taxes, the incentive to pursue more demanding roles, start new businesses, or make risky investments diminishes. This, critics contend, could stifle economic growth and reduce overall productivity.
Tax Avoidance and Evasion
Another concern is that complex progressive tax codes can incentivize tax avoidance and, in extreme cases, evasion. Higher tax rates can encourage wealthier individuals and corporations to seek loopholes, utilize sophisticated tax planning strategies, or even relocate assets and income to jurisdictions with lower tax burdens. This can undermine the system’s effectiveness in revenue generation and its goal of equitable burden sharing.
Economic Efficiency and Capital Formation
Critics also argue that progressive taxation can reduce economic efficiency by distorting market signals and misallocating resources. High taxes on capital gains or corporate profits, for example, might discourage savings and investment, which are crucial for capital formation and long-term economic expansion. The debate often centers on finding the optimal balance between equity and efficiency without hindering wealth creation.

Conclusion
A progressive tax system is a fundamental component of the fiscal policy in many countries around the world. It is characterized by tax rates that rise with income, aiming to distribute the tax burden based on an individual’s ability to pay. While championed for its potential to foster income equality, stabilize economies, and generate substantial public revenue, it also faces scrutiny for potential disincentives to work and invest, and its susceptibility to tax avoidance. The ongoing discourse surrounding progressive taxation highlights the complex interplay between economic efficiency, social equity, and the role of government in shaping a nation’s economic landscape. As societies evolve, so too does the debate over the optimal design and implementation of tax systems that can effectively meet both current needs and future challenges.