
In the dynamic world of drone operation, whether you’re a recreational FPV enthusiast, a professional aerial filmmaker, or an industrial UAV pilot, protecting your investment and mitigating risks is paramount. Drone insurance has become an essential component of responsible flight, and central to understanding any policy is the concept of a “deductible.” Far from being a mere footnote in your policy documents, the deductible is a critical financial lever that directly impacts your out-of-pocket expenses when an incident occurs with your unmanned aerial vehicle (UAV).
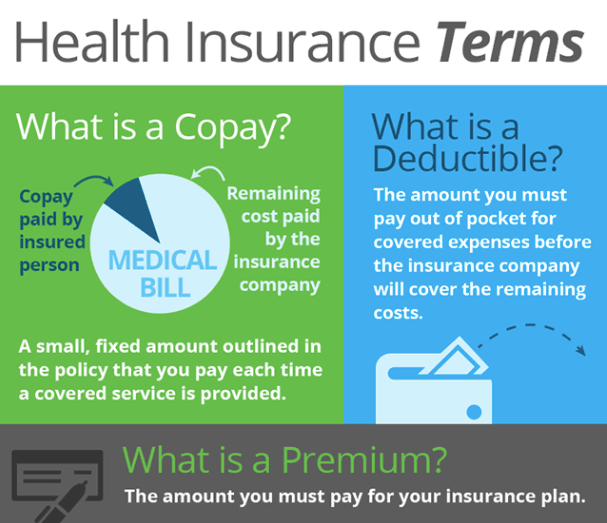
At its core, a deductible in the context of drone insurance represents the amount of money you, the policyholder, must pay yourself before your insurance provider begins to cover the remaining costs of an insured loss. Think of it as your initial contribution to the repair or replacement of a damaged drone, its payload, or to settle a liability claim. This predetermined amount is agreed upon when you purchase your policy and plays a significant role in determining your annual or monthly premium. A higher deductible typically results in a lower premium, and vice-versa, offering a strategic trade-off for drone operators to consider based on their risk tolerance and financial capacity.
The existence of deductibles serves several vital purposes for insurance companies and policyholders alike. Firstly, it discourages small, frequent claims, which can be administratively burdensome for insurers. For example, if your micro drone sustains minor propeller damage costing $50 to fix, and your deductible is $250, you’re unlikely to file a claim, instead covering the repair yourself. This helps keep overall insurance costs down. Secondly, deductibles encourage policyholders to exercise greater caution and responsible piloting, as they have a financial stake in preventing incidents. For a commercial drone operator using an expensive heavy-lift platform, the prospect of paying a $1,000 or $2,500 deductible out of pocket can be a strong motivator for rigorous pre-flight checks and adherence to safety protocols.
Understanding the Core Concept of a Deductible in Drone Insurance
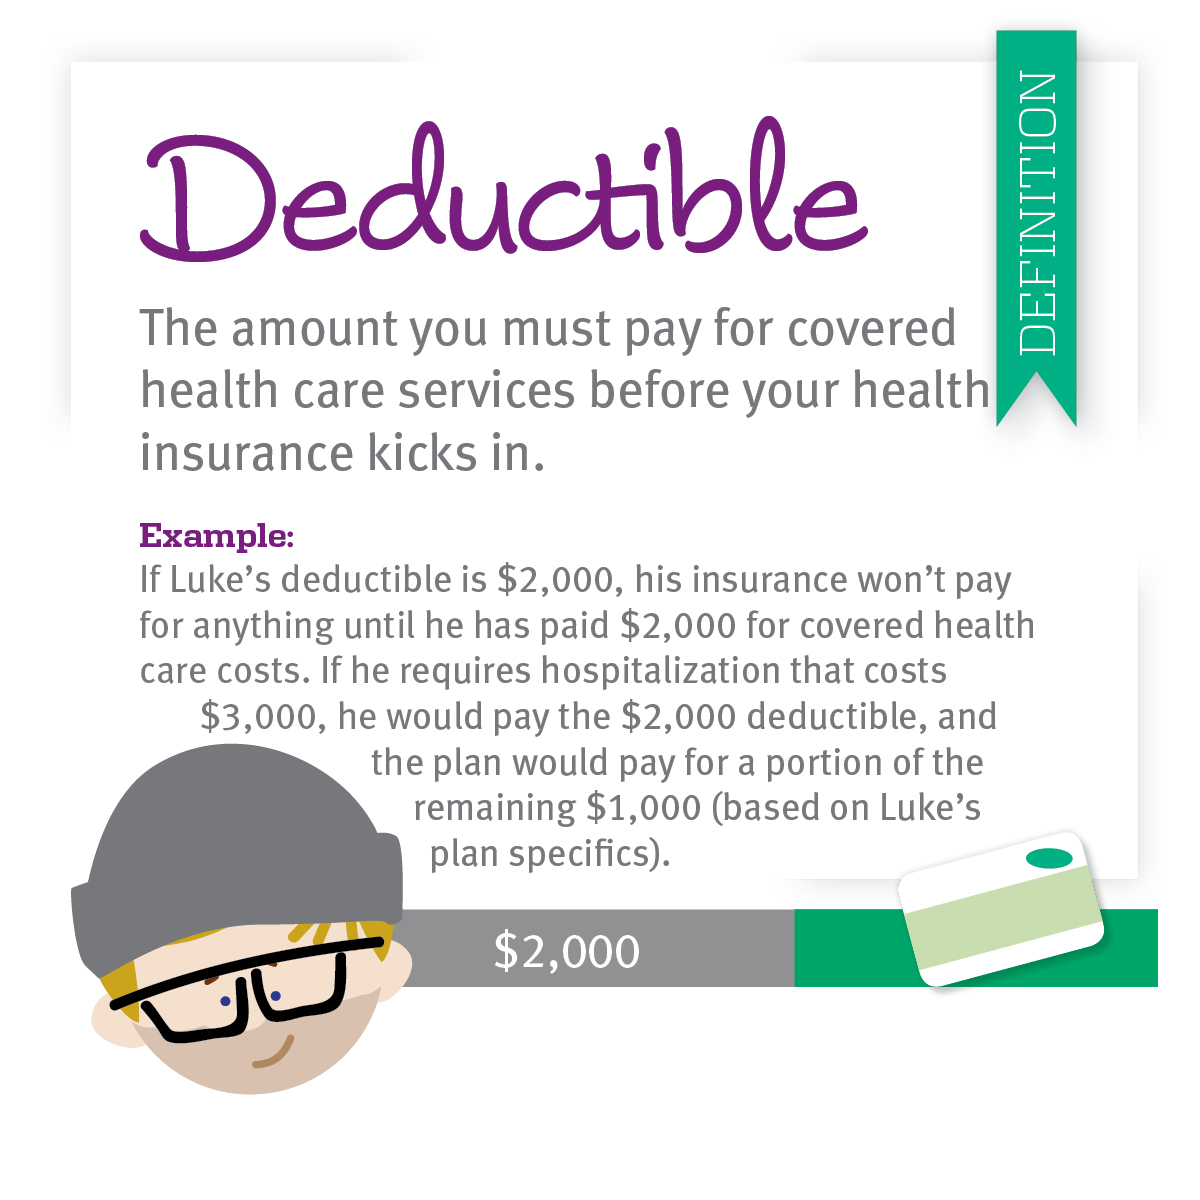
To fully grasp the implications of a deductible for your drone operations, it’s helpful to break down its function with specific examples pertinent to UAVs. When you file a claim for damage to your drone, loss, or a liability event, the deductible is the first amount subtracted from the total approved claim amount. The insurer then pays the remainder, up to the policy’s coverage limits.
Consider a scenario where your professional aerial cinematography drone, a high-end platform with a sophisticated gimbal camera, experiences a hard landing due to a sudden gust of wind. The incident results in damage to the drone’s frame, several motors, and the gimbal mechanism, requiring repairs totaling $3,500. If your drone insurance policy has a physical damage (hull) deductible of $750, you would be responsible for paying that $750 first. Your insurance company would then cover the remaining $2,750 ($3,500 – $750) for the repairs. Without a deductible, the insurer would theoretically pay the full $3,500, but your premium would likely be considerably higher to reflect that increased risk absorption by the insurer.
The deductible amount is typically applied per incident, meaning that if your drone is involved in multiple separate incidents over the policy period, you would likely pay the deductible each time you file a new claim. This reinforces the importance of safe flight practices and proper maintenance to minimize the frequency of incidents. For operators managing a fleet of drones, this “per incident” application can become a significant financial consideration, making aggregate deductibles (discussed later) an attractive option in some specialized policies.
How Deductibles Impact Drone Insurance Claims
The application of deductibles varies slightly depending on the specific type of coverage within your drone insurance policy. Most comprehensive drone policies typically include hull coverage (for the drone itself and its attached components), and liability coverage (for damage or injury caused to third parties).
Physical Damage (Hull) Deductibles
Hull coverage protects the physical drone and its expensive onboard equipment, such as 4K cameras, thermal sensors, or specialized payloads. This is where deductibles are most commonly applied.
- Scenario 1: Accidental Crash & Repair: A pilot operating a racing drone misjudges a turn during a practice run and crashes into a barrier. The quadcopter’s frame is cracked, and two ESCs are damaged. The repair cost is estimated at $400. If the hull deductible is $250, the pilot pays $250, and the insurer covers the remaining $150.
- Scenario 2: Theft: Your valuable survey-grade UAV, along with its custom carrying case, is stolen from your locked vehicle. The total replacement cost for the drone and accessories is $8,000. With a $1,000 deductible, you would pay $1,000, and the insurance company would reimburse you $7,000 towards the replacement.
- Scenario 3: Payload Damage: A commercial mapping drone experiences a minor malfunction, leading to a hard landing that primarily damages its high-resolution multispectral camera, a crucial component valued at $6,000. If your policy has a separate or combined deductible for payload damage, say $500, you pay that amount, and the insurer covers $5,500 for the camera’s repair or replacement.
Third-Party Liability Deductibles
Liability coverage is perhaps the most critical aspect of drone insurance, protecting you against legal and financial responsibility for property damage or bodily injury caused by your drone to others. While some liability policies may have a deductible, it’s far less common than with hull coverage, especially for smaller claims. Many liability policies are “first dollar” coverage, meaning the insurer pays from the very first dollar of loss, up to the policy limit, with no deductible for the policyholder. However, for specific commercial operations or very high-risk profiles, a liability deductible might be included to manage risk.
- Scenario: Drone Damages Property: During an industrial inspection, your drone veers off course due to GPS interference and clips a building, causing minor damage to its facade estimated at $1,200. If your liability policy has no deductible, the insurer would typically cover the full $1,200. If there were a $500 liability deductible, you’d pay that portion, and the insurer would cover $700.
It’s crucial to review your policy documents thoroughly to understand if and how deductibles apply to both hull and liability components of your drone insurance.
Types of Deductibles Relevant to Drone Operations
Beyond the standard per-claim deductible, there are other types that drone operators, particularly those with commercial operations or large fleets, might encounter or consider.
Standard Per-Claim Deductible
This is the most common type, where a fixed monetary amount is applied to each separate claim filed. As illustrated above, if you have a $500 deductible and file two separate hull claims in a year, you would pay $500 for the first and another $500 for the second. This simplicity makes it popular for most recreational and small commercial drone policies.
Percentage Deductible
More frequently seen in policies for high-value commercial drones, specialized payloads, or in scenarios involving significant risk, a percentage deductible requires the policyholder to pay a certain percentage of the total loss. For example, a policy might state a 5% deductible. If your $20,000 mapping drone suffers a total loss, your deductible would be 5% of $20,000, which is $1,000. If the repair cost for a partial damage incident is $4,000, the deductible would still be 5% of $4,000, which is $200. Percentage deductibles inherently scale with the severity of the loss or the value of the insured item, often providing a more nuanced risk-sharing mechanism.
Aggregate Deductible
An aggregate deductible specifies a total maximum amount that the policyholder will have to pay out in deductibles over the entire policy period, regardless of the number of claims filed. Once this aggregate limit is met, the insurer will cover 100% of any subsequent covered losses for the remainder of that policy term. This type is particularly beneficial for large commercial drone operations or entities with fleets of UAVs where multiple small incidents could occur within a year. For instance, a drone delivery company with an aggregate deductible of $5,000 might pay individual deductibles for their first few drone incidents. Once their out-of-pocket payments reach $5,000, any further claims in that policy year would be covered entirely by the insurer (up to policy limits), without additional deductible payments.
Strategic Considerations for Choosing Your Drone Insurance Deductible
Selecting the right deductible amount for your drone insurance policy is a strategic decision that should align with your operational risk profile, financial resilience, and desired premium cost.
Assessing Your Risk Exposure
Consider how frequently you fly your drone, the environments you operate in (e.g., urban, rural, near obstacles, over water), and the inherent risks of your specific drone activities (e.g., FPV racing, heavy-lift cinematography, industrial inspections in complex sites). If you’re a high-volume commercial operator flying daily in challenging conditions, you might experience more minor incidents. In such cases, a lower deductible, while resulting in a higher premium, could save you money in the long run by reducing your out-of-pocket costs across multiple claims. Conversely, if you fly recreationally and infrequently, or primarily in low-risk environments, a higher deductible might be acceptable to lower your premium.
Financial Capacity
Honestly evaluate how much you can comfortably afford to pay out-of-pocket for a drone repair or replacement at any given time without significant financial strain. A deductible should not be so high that it prevents you from getting necessary repairs or replacing a lost drone, effectively defeating the purpose of having insurance. For a hobbyist with a $1,000 drone, a $750 deductible might be too high, making them shoulder most of the loss. For a business with a $15,000 enterprise drone, a $1,000 or $2,500 deductible might be a more manageable and cost-effective option.
The Premium vs. Deductible Trade-off
This is the classic balancing act. Generally, a higher deductible translates to a lower insurance premium, as you are assuming more of the initial risk. A lower deductible means the insurer takes on more immediate risk, leading to a higher premium. Calculate your potential annual savings on premiums versus your potential out-of-pocket cost in case of a claim. Sometimes, a slightly higher premium for a lower deductible is a worthwhile investment for peace of mind, especially for critical operational drones.
Specific Coverage Needs
Consider if your deductible applies uniformly across all aspects of your drone insurance (hull, payload, accessories) or if there are separate deductibles for different components. Some policies might have a lower deductible for the drone itself but a higher one for specialized, highly valuable, or easily damaged payloads (e.g., thermal cameras, LiDAR units). Ensure you understand these nuances.
Navigating a Claim with a Deductible for Your UAV
When an unfortunate incident occurs with your drone, understanding the claims process, especially concerning your deductible, is crucial for a smooth resolution.
- Immediate Action & Documentation: After an incident, prioritize safety and secure your drone (if possible). Document the scene thoroughly with photos and videos. Retrieve any available flight logs, which are invaluable for demonstrating the circumstances of the incident to your insurer. This data, unique to UAVs, can provide critical context regarding flight path, altitude, speed, and any error messages.
- Contact Your Insurer: Report the incident to your drone insurance provider as soon as reasonably possible. Provide them with all the documented information, including a detailed description of what happened and the extent of the damage.
- Claim Assessment: The insurer will initiate the claims process, which may involve assigning a claims adjuster. For complex or high-value drones, this might be an adjuster specializing in aviation or drone technology. They will assess the damage, review your documentation, and determine if the incident is covered under your policy. They will also estimate the repair or replacement cost.
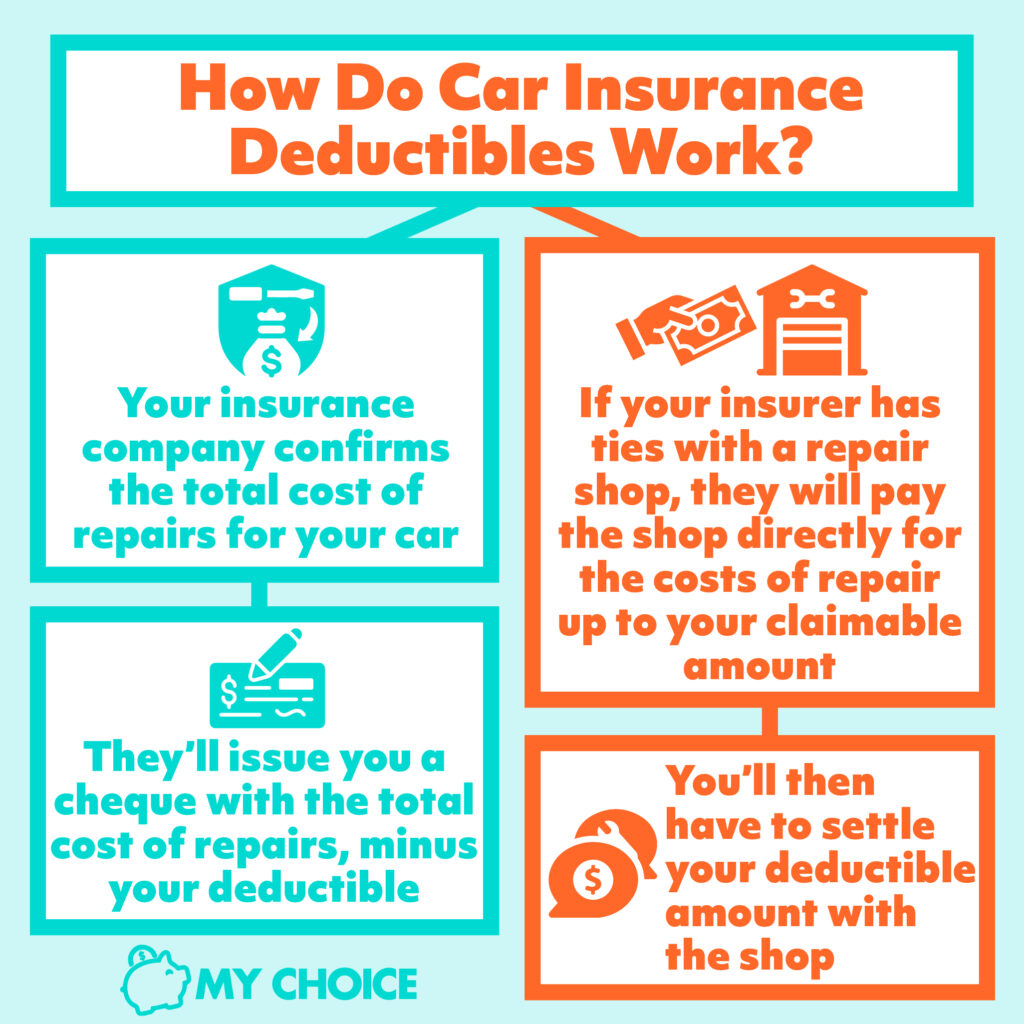
- Deductible Application: Once the claim is approved and the total covered loss is determined, your deductible will be applied. The insurer will subtract your deductible amount from the total approved payout.
- Payment & Resolution: You will be responsible for paying your deductible directly to the repair facility (if your drone is being fixed) or it will be withheld from the insurance payout for a total loss. The insurer will then pay the remaining balance directly to the repair shop or reimburse you for the covered loss.
In essence, the deductible on your drone insurance is more than just a number; it’s an active participant in your risk management strategy. By carefully considering its role, you can make informed decisions that protect your valuable drone assets, manage your financial exposure, and ensure the continuity of your aerial operations.