
High-yield savings accounts (HYSAs) represent a significant evolution in personal finance, leveraging advancements in financial technology to offer consumers substantially higher interest rates on their deposits compared to traditional savings options. In an era defined by digital transformation and instant access, HYSAs stand out as a smart, accessible tool for managing and growing liquid funds. These accounts are primarily offered by online banks and credit unions, which operate with lower overhead costs than their brick-and-mortar counterparts. This operational efficiency, a direct benefit of technological streamlining, allows them to pass on a greater share of their earnings to depositors in the form of elevated annual percentage yields (APYs). Understanding what constitutes an HYSA, how they function, and their strategic place within a modern financial plan is crucial for anyone looking to optimize their savings.
The Evolution of Savings: A Technological Leap
The concept of a savings account is fundamental to personal finance, providing a secure place to store money and earn a modest return. However, the digital revolution has reshaped this landscape, giving rise to HYSAs that redefine what “modest return” can mean. This transformation is not merely incremental; it’s a paradigm shift driven by technological innovation in banking.
Traditional vs. High-Yield: The Digital Advantage
Traditional savings accounts, typically offered by large national banks with extensive physical branch networks, often feature very low interest rates, sometimes barely keeping pace with inflation. These institutions bear significant costs associated with maintaining physical infrastructure, staffing, and legacy systems. In contrast, HYSAs capitalize on a lean, technology-first operational model. Online-only banks, free from the burden of physical branches, reduce their operational expenditures dramatically. This cost saving is the primary mechanism through which they can afford to offer superior APYs. The core innovation here isn’t a new financial product, but rather a new delivery mechanism that fundamentally alters the economic model of banking, making it more advantageous for the end consumer. This digital-first approach allows for greater efficiency in processing transactions, managing customer data, and deploying capital, all of which contribute to the ability to offer higher returns.
How Technology Drives Higher Rates
The ability of HYSAs to offer elevated interest rates is intrinsically linked to their technological foundation. Firstly, sophisticated digital platforms enable these institutions to automate many processes that would otherwise require manual intervention, from account opening to transaction processing and customer service. This automation translates directly into lower labor costs. Secondly, enhanced data analytics and risk management algorithms allow online banks to operate with greater precision, optimizing their lending and investment strategies to maximize returns while maintaining required liquidity. Thirdly, the inherent scalability of digital infrastructure means these banks can serve a vast customer base without proportionally increasing their physical footprint or staff, further enhancing their cost-efficiency. Finally, the seamless integration of online banking with other fintech tools allows for a more efficient flow of funds and more dynamic treasury management, all contributing to the financial health that permits competitive APYs. These technological advantages culminate in a financial product that serves the customer better by giving back a larger portion of the bank’s earnings.
Key Features and Benefits of HYSA Technology
Beyond just higher interest rates, HYSAs offer a suite of features that are deeply intertwined with their technological underpinnings, making them highly attractive to the modern saver. These advantages extend to accessibility, efficiency, and security.
Accessibility and Online Management
The hallmark of a high-yield savings account is its unparalleled accessibility. Accounts can typically be opened online in minutes, requiring minimal paperwork and often no in-person verification. Once established, account holders gain 24/7 access to their funds and account information through intuitive web portals and mobile applications. These platforms allow users to monitor balances, track interest earnings, set up recurring transfers, and move money between accounts with ease. Features like mobile check deposit, electronic transfers (ACH), and integration with payment apps further enhance convenience. This digital-first approach means savers are no longer bound by banking hours or geographic location, offering unprecedented control and flexibility over their money. The user experience is often superior, characterized by clean interfaces, robust self-service options, and personalized notifications.
Enhanced Interest Earnings Through Digital Efficiency
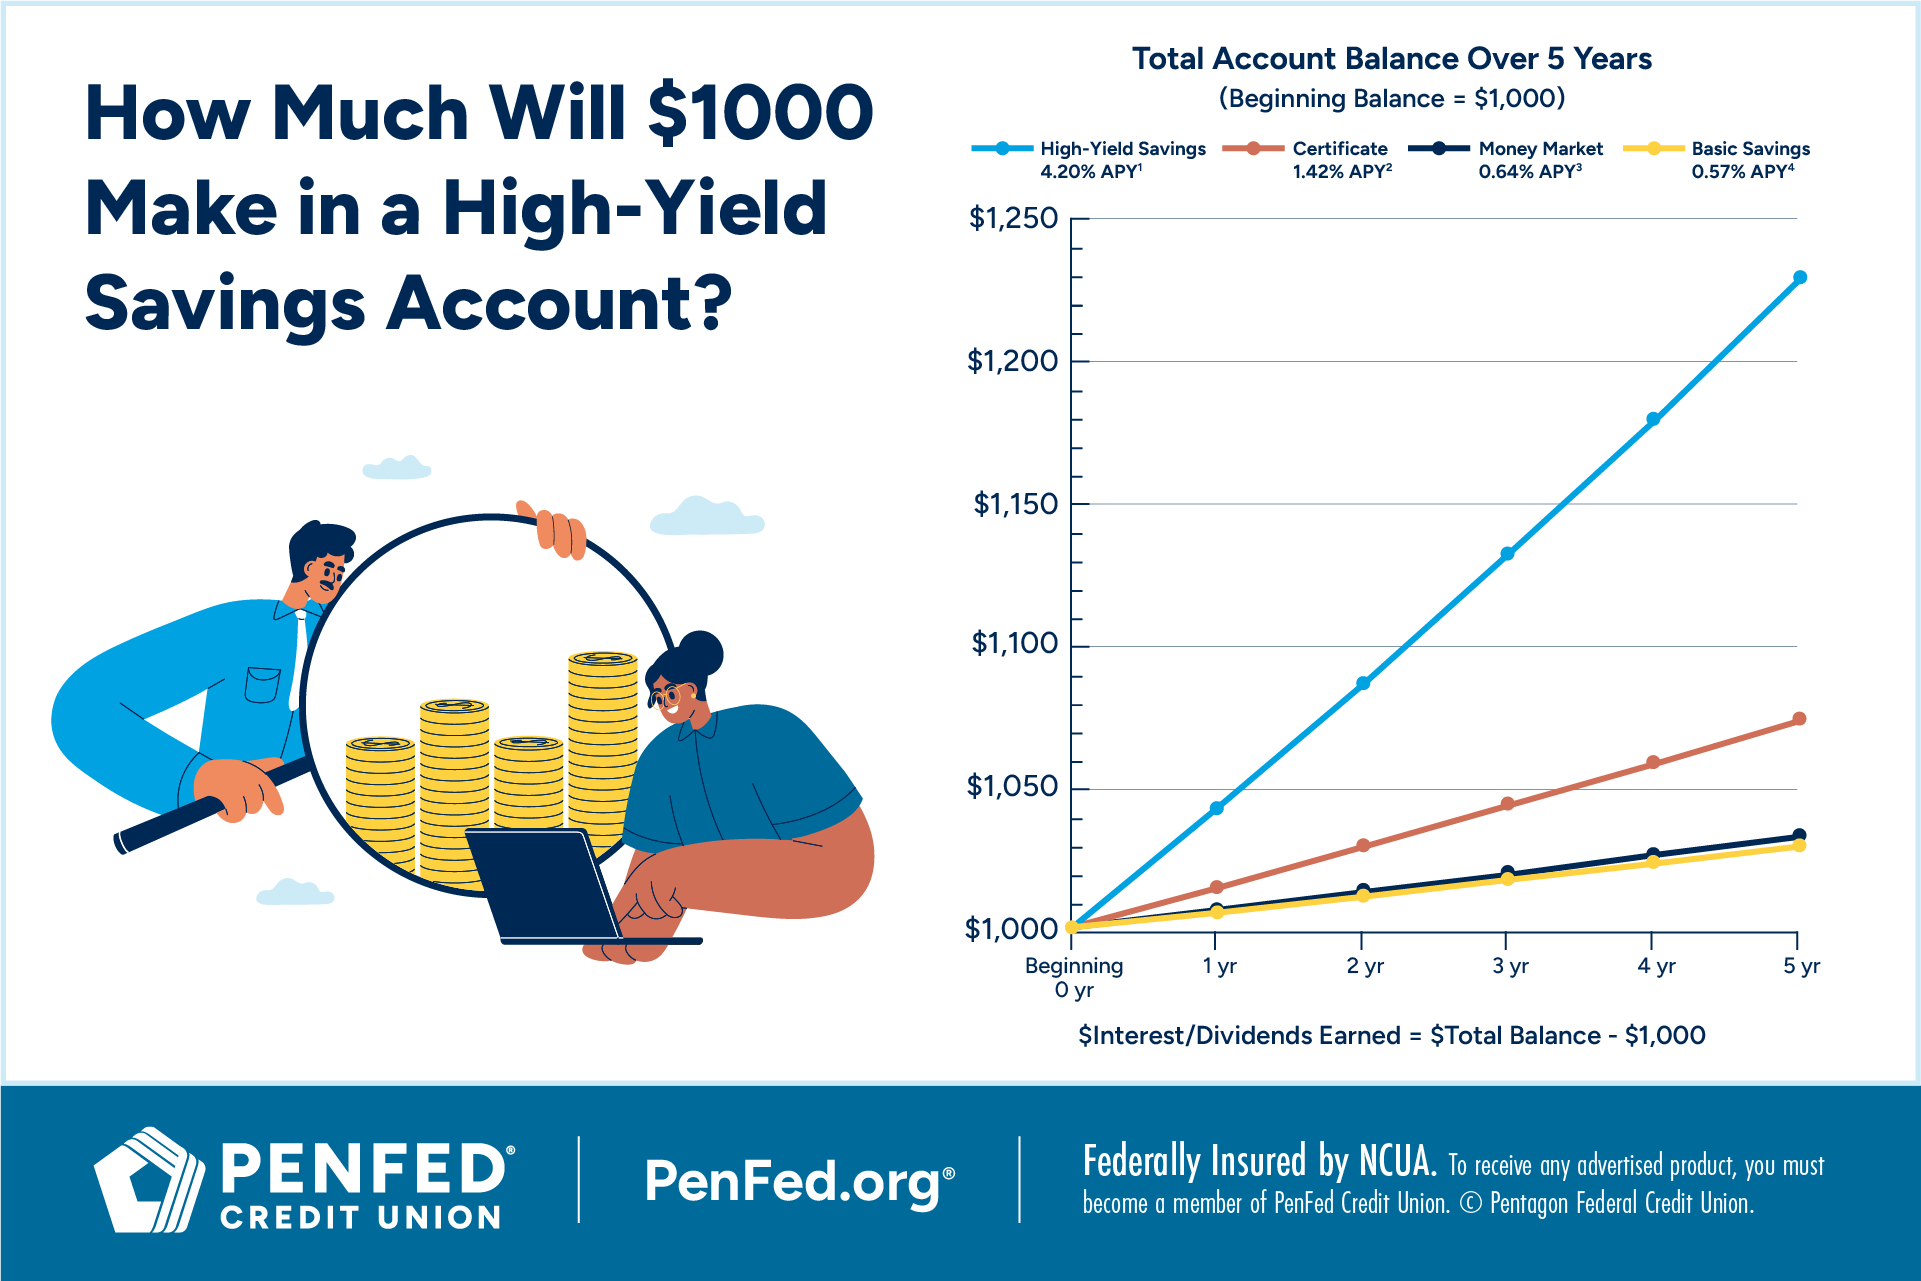
The primary benefit, as discussed, is the significantly higher APY. This isn’t just a minor bump; it can often be several multiples higher than rates offered by traditional banks. For example, while a traditional savings account might offer 0.01% to 0.05% APY, an HYSA might offer 3.00% to 5.00% APY or more, depending on market conditions. Over time, particularly with compounding interest, this difference can amount to substantial additional earnings. The digital efficiency of these banks allows them to maintain these higher rates consistently, making them a powerful tool for growing an emergency fund, saving for a down payment, or accumulating funds for any short-to-medium-term financial goal. The compounding effect, where interest is earned not only on the principal but also on previously accrued interest, is significantly amplified by higher rates.
Security in the Digital Age
A common concern with purely online financial products is security. However, HYSAs offered by reputable institutions are just as secure, if not more so, than traditional bank accounts. These banks employ state-of-the-art encryption technologies, multi-factor authentication (MFA), fraud monitoring systems, and advanced cybersecurity protocols to protect customer data and funds. Most importantly, HYSAs are typically insured by the Federal Deposit Insurance Corporation (FDIC) for up to $250,000 per depositor, per insured bank, in the event of bank failure, just like traditional banks. For credit unions, similar protection is offered by the National Credit Union Administration (NCUA). This federal insurance, combined with robust digital security measures, provides a strong safety net, mitigating the risks associated with storing funds digitally.
Navigating the HYSA Landscape: What to Look For
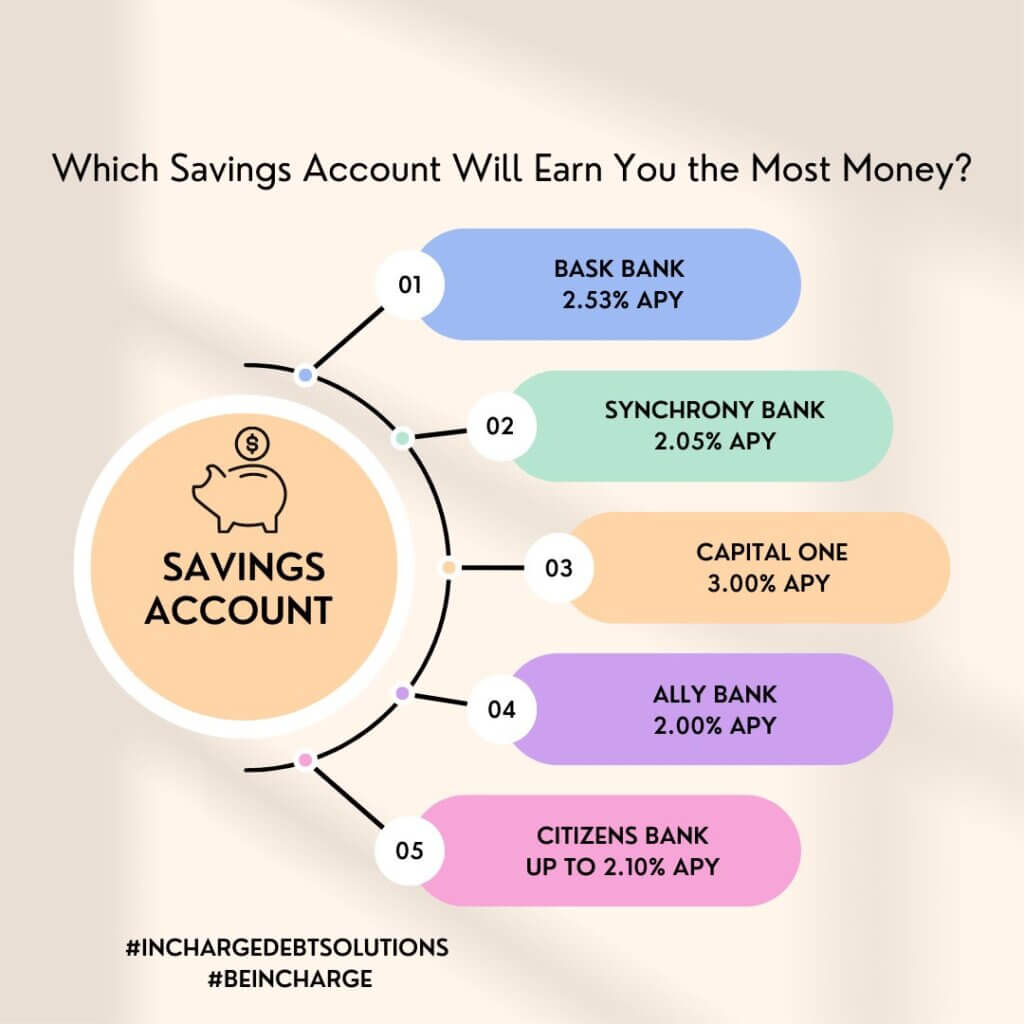
While the benefits of HYSAs are compelling, not all accounts are created equal. Savvy savers need to evaluate several factors to choose an account that best fits their financial needs and objectives, focusing on the finer points enabled by their technological frameworks.
Understanding APY and Compounding
The Annual Percentage Yield (APY) is the most critical metric for HYSAs, as it reflects the total amount of interest paid on an account over a year, taking compounding into effect. It’s essential to understand that APYs can fluctuate with market conditions, particularly interest rate changes by central banks. While an HYSA will generally maintain a competitive edge, its specific rate isn’t fixed indefinitely. It’s also important to consider how frequently interest is compounded (daily, monthly, quarterly). Daily compounding, often facilitated by sophisticated banking software, results in slightly higher effective returns over time compared to less frequent compounding, though the difference might be marginal for smaller balances.
Fees, Minimums, and Digital Limitations
Despite their digital efficiency, some HYSAs may still have certain fees or minimum balance requirements. Common fees might include those for excessive withdrawals (though HYSAs typically adhere to federal limits on monthly withdrawals), wire transfers, or dormant accounts. Many online banks, however, pride themselves on offering fee-free accounts with no minimum balance to open or maintain, leveraging their lower operating costs. It’s crucial to review the fee schedule carefully. Additionally, while HYSAs offer high liquidity, they are not checking accounts. Federal regulations (Regulation D, though currently suspended, its principles often guide bank practices) historically limit transfers and withdrawals from savings accounts. While the suspension provides more flexibility, banks can still impose their own limits. Understanding these digital limitations, usually outlined in the account terms, is vital.
Integration with Other Financial Tech
A distinct advantage of many HYSAs lies in their seamless integration with other financial technology tools and services. Many online banks offer user-friendly mobile apps that integrate features like budgeting tools, spending trackers, and even direct connections to investment platforms or peer-to-peer payment services. This interconnectedness allows for a more holistic view and management of one’s financial ecosystem. Some accounts might even offer features like “round-up” savings, where spare change from debit card purchases is automatically transferred to the HYSA, an innovative use of technology to encourage consistent saving. When choosing an HYSA, consider how well it integrates with your existing financial tech stack and if it offers features that can simplify your financial life.
The Strategic Role of HYSAs in Modern Finance
HYSAs are more than just accounts for earning interest; they are strategic tools that play a vital role in building a robust and resilient personal financial plan in the digital age. Their attributes make them ideal for specific financial goals.
Building Emergency Funds with Digital Tools
Perhaps the most common and recommended use for an HYSA is housing an emergency fund. The combination of high liquidity, FDIC/NCUA insurance, and superior interest earnings makes HYSAs perfect for this purpose. An emergency fund needs to be readily accessible yet growing, and an HYSA provides precisely that balance. The digital platforms allow for quick transfers when an emergency arises, while the higher APY ensures that the fund isn’t losing significant purchasing power to inflation while it sits dormant. Setting up automated recurring transfers to an HYSA via online banking tools can streamline the process of building this critical financial safety net.
Optimizing Short-Term Savings Goals
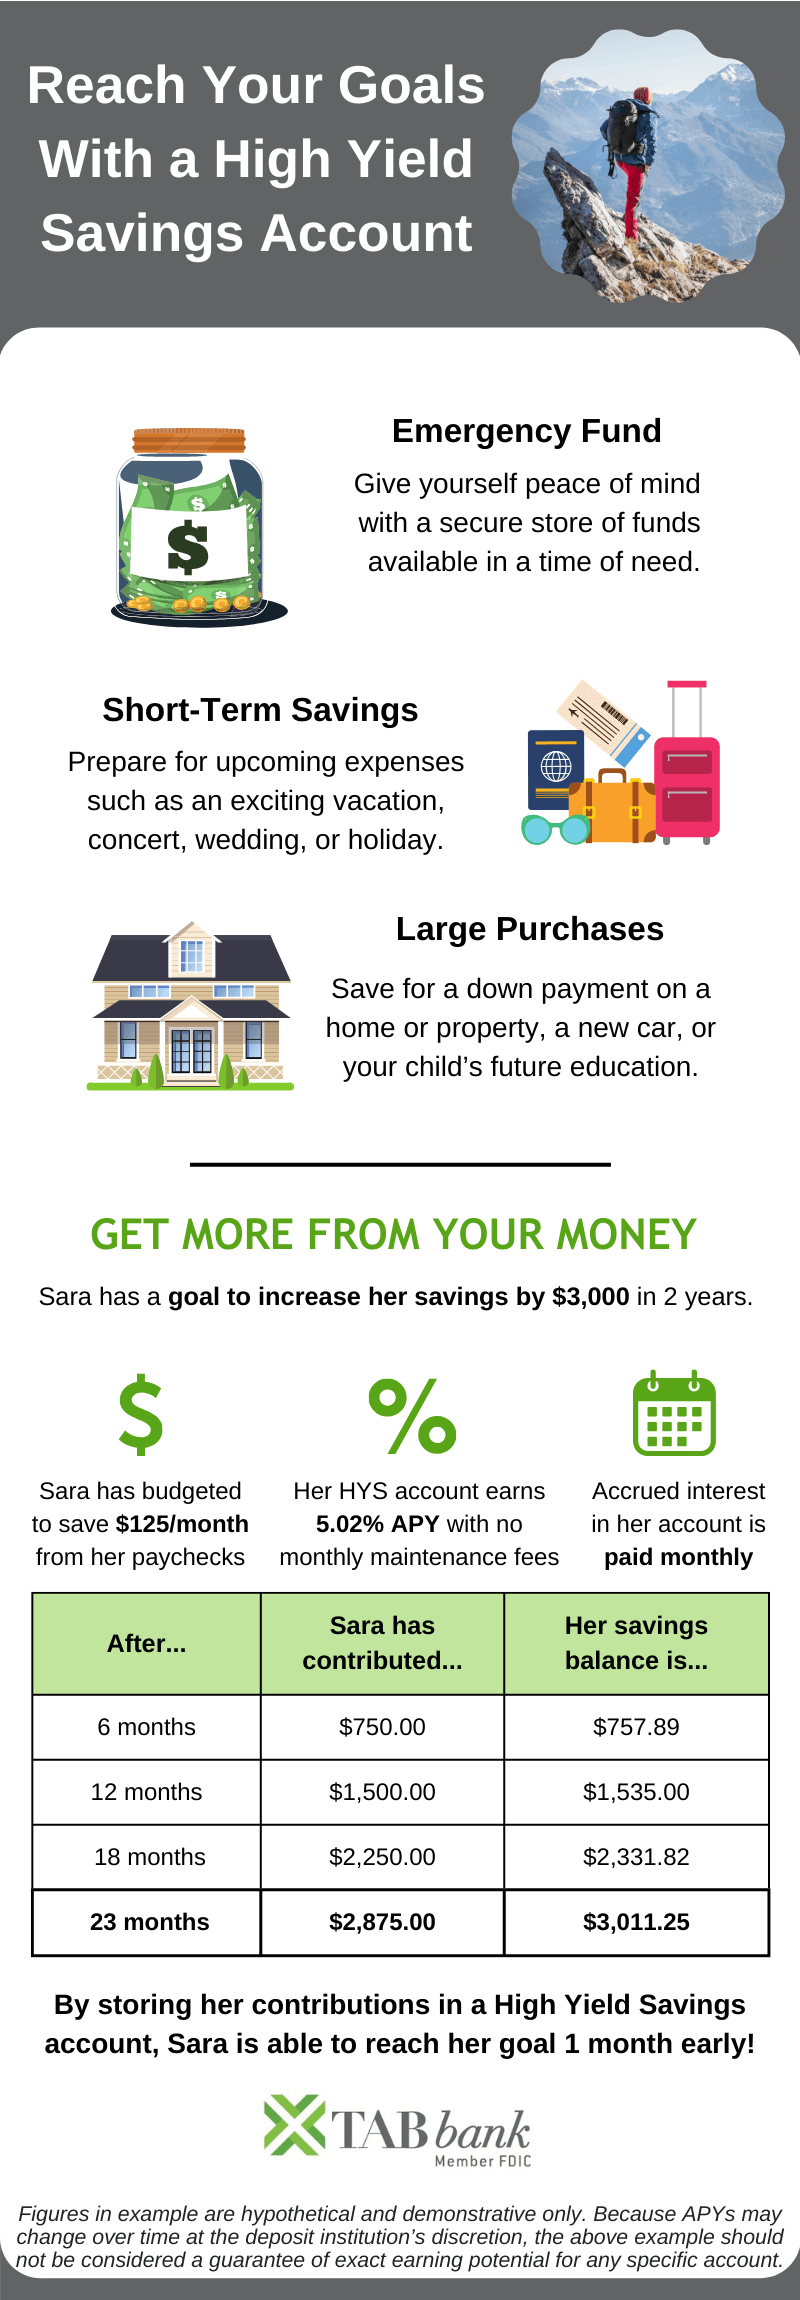
Beyond emergencies, HYSAs are excellent for any short-to-medium-term savings goals (typically 1-5 years). This could include saving for a down payment on a house, a new car, a vacation, or a major purchase. Unlike investment accounts, HYSAs carry virtually no market risk, ensuring that the principal amount is preserved and grows predictably. The higher interest rates mean these goals can be reached faster or with less overall contribution from your active income, thanks to the power of compound interest. Many online banks even offer sub-accounts or “buckets” within a single HYSA, allowing users to digitally earmark funds for different goals, enhancing organization and motivation.
Complementing Broader Investment Strategies
While HYSAs are not a substitute for long-term investments like stocks or bonds, they serve as a crucial complement. They can act as a “cash holding” area for funds awaiting deployment into investments, or as a safe harbor for profits taken from volatile markets. For individuals adhering to a diversified portfolio strategy, HYSAs provide the stable, low-risk component for liquid assets, balancing out the higher-risk, higher-return potential of other investment vehicles. They ensure that all your money, even your most liquid funds, is working efficiently for you, leveraging the best of financial innovation.