
California, a hub of technological innovation and a significant market for drone technology, implements a sales tax system that impacts both individual consumers and businesses operating within the state. Understanding the nuances of California’s sales tax is crucial for anyone involved with drones, from hobbyists purchasing their first FPV system to commercial operators acquiring advanced aerial platforms, and businesses selling drone-related products or services. Unlike a simple flat rate, California’s sales tax is a complex interplay of state-wide base rates and various local district taxes, all of which contribute to the final price paid for tangible personal property, including drones and their associated accessories. This article delves into the specifics of California sales tax, offering a professional and insightful guide for the drone community.
Understanding the Base Rate and Local Add-ons for Drone Purchases
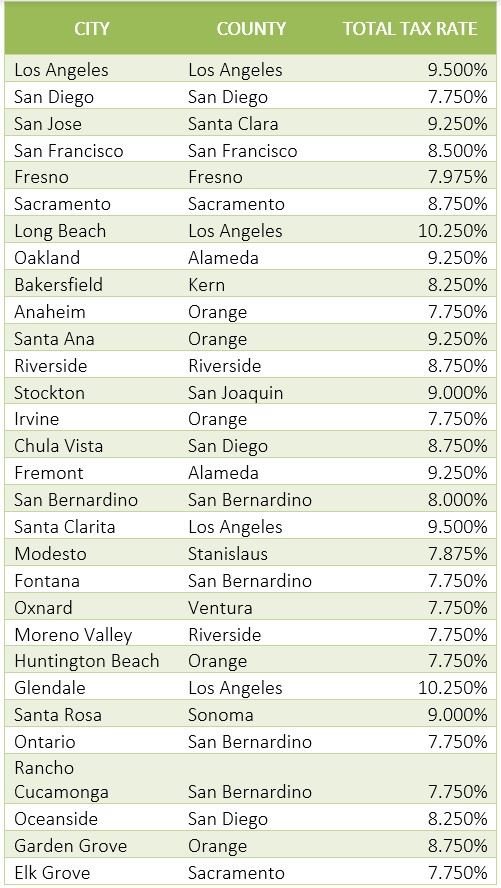
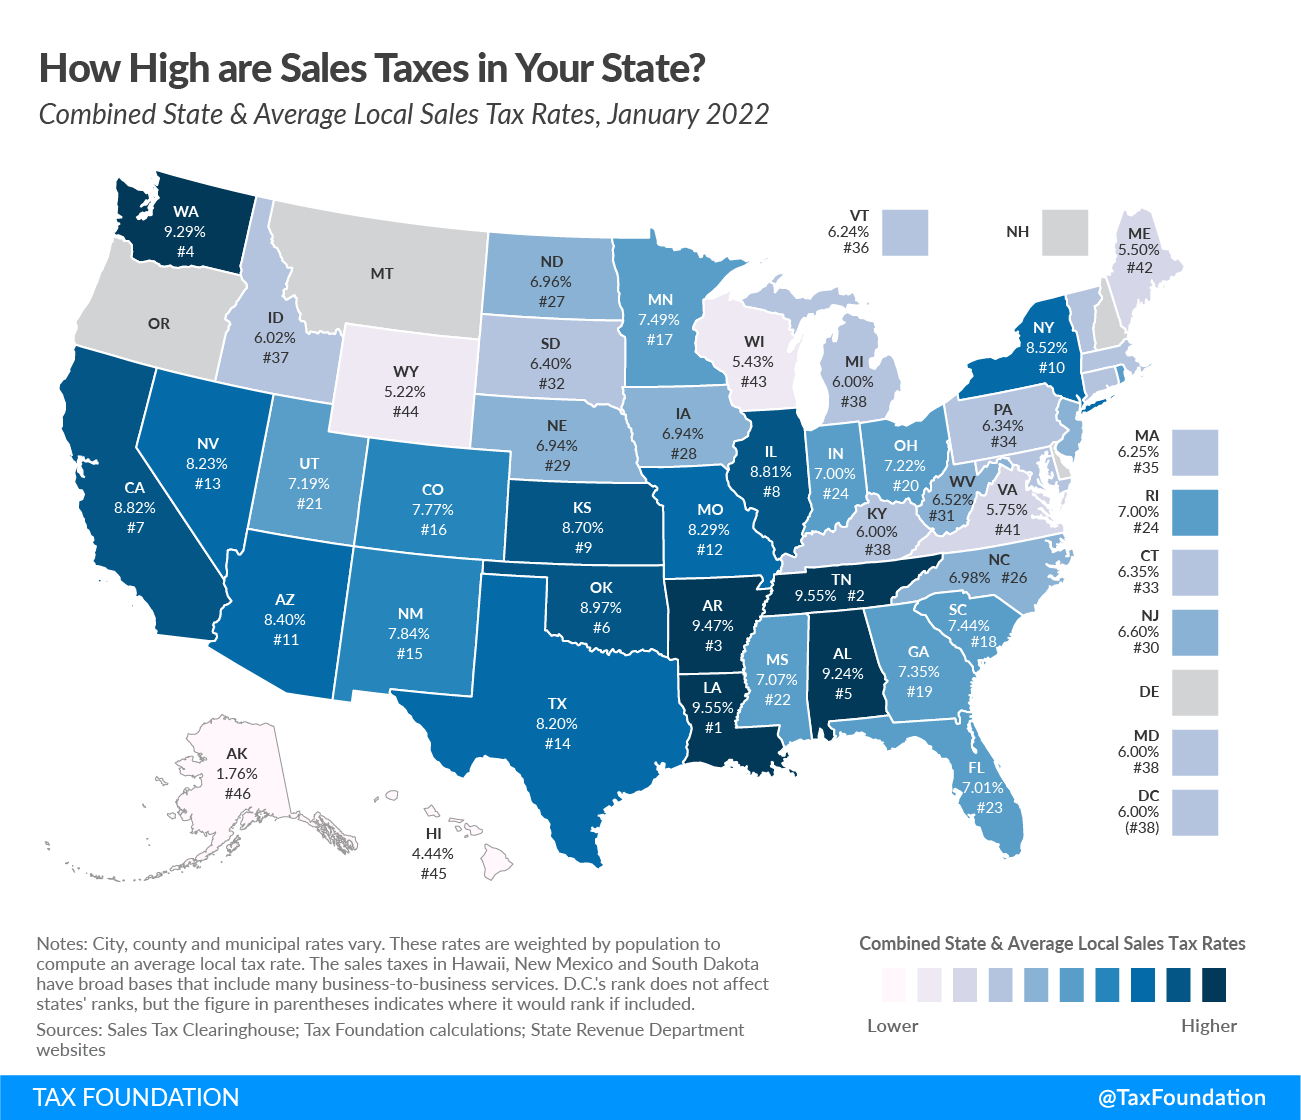
The California sales tax is not a single, uniform percentage across the entire state. Instead, it is comprised of a statewide base rate supplemented by numerous local district taxes. This structure means that the precise sales tax rate applied to a drone purchase can vary significantly depending on the specific city and county where the transaction takes place. For drone enthusiasts and businesses, accurately identifying this rate is essential for budgeting and compliance.
State-Wide Baseline
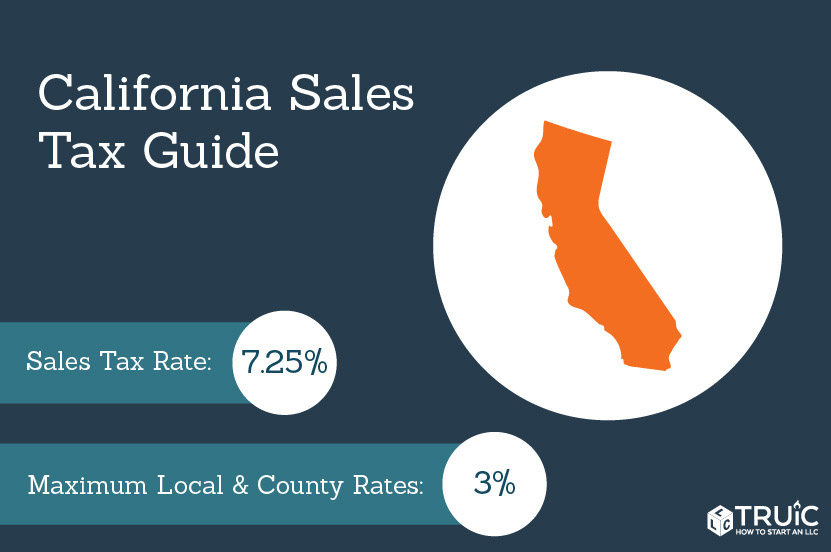
At the core of California’s sales tax system is a statewide base rate. This rate is established by the state legislature and applies uniformly across all jurisdictions within California. As of the latest information, this foundational rate has been a significant component of the overall sales tax. It is the minimum percentage applied to the retail sale of taxable goods. For drone retailers, this base rate represents the standard portion of sales tax they must collect and remit to the California Department of Tax and Fee Administration (CDTFA). For consumers, it’s the non-negotiable starting point for calculating the tax on their new quadcopter, thermal camera, or flight controller.
District Taxes: A Variable for Drone Buyers
Beyond the statewide base rate, California allows local jurisdictions—such as counties, cities, and special districts—to impose additional sales taxes. These are known as district taxes. These voter-approved taxes fund a variety of local services, including transportation, public safety, and other community initiatives. Consequently, the total sales tax rate experienced by a drone buyer can fluctuate from one district to another, sometimes by several percentage points.
For instance, a drone purchased in Los Angeles County might incur a different total sales tax rate than the exact same drone purchased in San Francisco County, or even in a different city within Los Angeles County, due to varying district taxes. This regional variation necessitates that both consumers and businesses confirm the precise sales tax rate applicable to their specific location of transaction. Online drone retailers, in particular, must have robust systems in place to accurately calculate and collect sales tax based on the buyer’s shipping address, as this determines the applicable district taxes. Failure to do so can lead to under-collection and subsequent liabilities, or over-collection and customer dissatisfaction.
Impact on Drone Enthusiasts and Businesses
The California sales tax significantly impacts both the individual who buys a drone for recreational use or professional application, and the businesses that manufacture, distribute, or retail drone technology. Understanding these implications is key to navigating the market efficiently and compliantly.
For Individual Consumers: Calculating Your Drone’s Final Cost
For the drone enthusiast, the sales tax directly affects the final out-of-pocket expense. When purchasing a new drone, a gimbal camera, spare batteries, or even specialized FPV goggles, the advertised price is typically before sales tax. The applicable sales tax rate, determined by the location of purchase (or shipping address for online orders), will be added to this price. This means a drone advertised at $1,500 might end up costing over $1,600 after tax, depending on the specific California district.
Savvy drone buyers often factor in sales tax when comparing prices from different retailers, especially if they have the option to purchase from stores in different tax districts or online. Furthermore, for those looking to import drone parts or complete systems from out-of-state or internationally, California’s “use tax” comes into play. If sales tax was not collected by the seller (because they are not registered in California), the buyer is generally responsible for remitting an equivalent use tax directly to the state. This ensures that out-of-state purchases are taxed similarly to in-state purchases, preventing an unfair advantage. Understanding this distinction can prevent unexpected tax liabilities for individuals acquiring specialized drone components or imported systems.
For Drone Businesses: Collection and Remittance Obligations
For businesses operating in the drone sector within California—whether they are manufacturers, wholesale distributors, or retail outlets—the sales tax represents a critical aspect of their financial and legal compliance. These businesses are generally required to register with the CDTFA, obtain a seller’s permit, and then collect sales tax from their customers on all taxable sales. The collected sales tax is not income for the business; rather, it is funds held in trust for the state.
Businesses must meticulously track all sales, accurately calculate the applicable sales tax based on the customer’s location, and then periodically remit these collected taxes to the CDTFA. The frequency of remittance (monthly, quarterly, or annually) depends on the volume of sales tax collected. Failure to correctly collect, report, and remit sales tax can result in significant penalties, interest charges, and potential legal issues. This includes fines for late payments, underpayments, or even tax fraud. For drone businesses engaging in both in-state and out-of-state sales, the complexity increases, requiring careful distinction between taxable and non-taxable transactions based on nexus rules and shipping destinations. Furthermore, businesses selling to other businesses for resale (e.g., a drone manufacturer selling to a retail store) must ensure they obtain valid resale certificates from their buyers to avoid collecting sales tax on wholesale transactions.
Taxable vs. Non-Taxable Drone-Related Transactions
Navigating the California sales tax landscape for drones requires a clear understanding of what constitutes a taxable transaction. Generally, sales tax applies to the retail sale of tangible personal property. However, the rapidly evolving drone industry also involves services and digital products, which can have different tax implications.
Tangible Personal Property: The Core of Drone Taxation
The vast majority of drone-related purchases fall under the category of tangible personal property and are therefore subject to California sales tax. This includes:
- Complete Drone Systems: Ready-to-fly drones, FPV kits, cinematic drones, enterprise UAVs, and even drone components sold individually (frames, motors, ESCs, flight controllers, GPS modules).
- Drone Accessories: Batteries, propellers, remote controllers, carrying cases, chargers, antennas, landing gear, and spare parts.
- Payloads: Gimbal cameras (e.g., 4K, thermal, multispectral), LiDAR units, speakers, spotlights, and other attachments that add functionality to the drone.
- Ground Station Equipment: Monitors, tablets, and specialized computers sold as part of a drone system that are tangible hardware.
- Repair Parts: Any physical parts purchased for repairing a drone or its components.
For these items, the sales tax calculation is straightforward: the selling price multiplied by the applicable sales tax rate at the point of sale or delivery. Businesses must ensure their POS systems or e-commerce platforms are configured to correctly apply these taxes based on the shipping address of the buyer.
Services and Digital Products: Nuances for Drone Software
While tangible goods are clearly taxable, the taxation of services and digital products in California is more nuanced and often not subject to sales tax, unless they are an integral and inseparable part of the sale of tangible personal property.
- Drone Services: Services such as aerial photography, videography, drone inspections, mapping, surveying, and drone pilot training are generally considered non-taxable services in California. The labor and expertise provided do not involve the transfer of tangible personal property to the client in a way that triggers sales tax. However, if these services include the transfer of a physical deliverable (e.g., a printed map, a USB drive with data where the primary value is the physical medium itself), complications can arise. Generally, the fee for operating the drone and processing the data is service-based and non-taxable.
- Digital Products: Many modern drone systems rely heavily on software, firmware updates, and cloud-based services. Pure digital goods, such as downloaded software updates, mobile applications (unless bundled with hardware), or subscriptions to cloud processing platforms for drone data, are typically not subject to California sales tax. The key distinction is whether a tangible medium (like a physical CD-ROM) is transferred. With the proliferation of over-the-air updates and subscription models, most software aspects of drone operation fall outside the direct scope of sales tax. However, if software is pre-loaded onto a tangible device (like a drone controller or a specialized tablet sold with the drone), its value is generally included in the taxable price of the hardware. This area can be complex, and businesses offering mixed packages of hardware and software/services should consult with tax professionals to ensure compliance.
Navigating Exemptions and Reporting for Drone Operations
While most retail sales of drones and related hardware are taxable, understanding potential exemptions and the proper reporting mechanisms is vital for both individual purchasers and drone enterprises to ensure full compliance with California sales and use tax laws.
Potential Exemptions: Limited Scope for Drones
California’s sales tax law provides specific exemptions, but these are generally narrow and typically do not apply to the vast majority of drone purchases by consumers. Common exemptions that do not apply to drones include food, prescription medicines, and certain manufacturing equipment for specific industries.
However, there are a few scenarios where a drone-related purchase might be exempt:
- Sales for Resale: A drone business that purchases drones or components from a wholesaler or manufacturer with the intent to resell them in the regular course of business can provide a valid resale certificate to the seller. This exempts the wholesale purchase from sales tax, as the tax will be collected when the item is ultimately sold to the end consumer. This is a critical exemption for the supply chain of the drone industry.
- Out-of-State Sales: If a California-based drone retailer sells a drone to a customer who takes possession of it outside of California, or if the drone is shipped by the retailer directly to an out-of-state address, that sale is generally exempt from California sales tax. This is because California’s sales tax jurisdiction applies only to sales and deliveries within its borders.
- Certain Government or Non-Profit Purchases: While rare for standard drone purchases, specific government entities or qualifying non-profit organizations might have sales tax exemptions for certain purchases. Drone businesses selling to these entities should verify their exempt status and obtain proper documentation.
It is crucial for any business or individual claiming an exemption to maintain thorough records to substantiate the claim, as the CDTFA may audit such transactions.
Sales and Use Tax Reporting for Drone Enterprises
For drone businesses, accurate and timely reporting of sales and use tax is a continuous obligation. Businesses holding a seller’s permit must periodically file sales and use tax returns with the CDTFA. These returns detail the total taxable sales made during the reporting period, the amount of sales tax collected, and any applicable use tax liabilities.
Key aspects of reporting include:
- Filing Frequency: Determined by the CDTFA based on the amount of sales tax a business collects, filing can be monthly, quarterly, or annually. Larger drone retailers will typically file more frequently.
- Use Tax Reporting: If a drone business purchases tangible personal property from an out-of-state vendor for its own use (e.g., office equipment, a drone for internal R&D) and that vendor did not collect California sales tax, the business is responsible for reporting and paying the equivalent “use tax” on its sales and use tax return. This ensures a level playing field between in-state and out-of-state purchases.
- Record Keeping: Comprehensive records of all sales, invoices, sales tax collected, exemptions claimed (e.g., resale certificates), and remittance records are mandatory. These records must be retained for at least four years and are crucial during any potential audit by the CDTFA.
- Online Sales Considerations: For drone businesses with an online presence, the reporting requirements can be complex due to varying district tax rates. E-commerce platforms must accurately calculate sales tax based on the buyer’s shipping address, which dictates the local district tax rate. This requires up-to-date tax tables and robust geographical tax calculation capabilities.
Understanding and meticulously adhering to these reporting requirements is paramount for drone businesses to maintain good standing with the state and avoid costly penalties, allowing them to focus on innovation and growth in the dynamic drone market.