
In the intricate landscape of modern finance, the FICO score stands as a cornerstone of credit assessment, a sophisticated algorithmic construct that distills an individual’s financial history into a single, three-digit number. While many aspire to merely “good” credit, the pursuit of the “top FICO score” represents an ambition to achieve peak financial health and unlock the most favorable terms in a credit-driven economy. Understanding what constitutes this pinnacle requires delving into the technological innovation that birthed FICO, the complex algorithms it employs, and the strategic financial behaviors that optimize one’s standing within this system.
The Architecture of Credit Assessment: FICO’s Innovation
The FICO score, developed by the Fair Isaac Corporation, was a groundbreaking technological innovation that transformed how lenders evaluate risk. Before its widespread adoption, credit decisions were often subjective, relying on qualitative assessments and individual lender discretion. FICO introduced a standardized, objective, and data-driven approach, fundamentally changing the financial industry.
From Qualitative to Quantitative: A Paradigm Shift
The advent of FICO scores marked a significant paradigm shift from subjective credit analysis to a data-driven, quantitative methodology. This innovation leveraged early computational power and statistical modeling to process vast amounts of consumer financial data. Instead of relying on a loan officer’s interpretation of an applicant’s character or anecdotal evidence, FICO provided a consistent numerical representation of creditworthiness. This not only streamlined the lending process but also reduced bias and expanded access to credit for many, albeit within the confines of its algorithmic parameters. The very existence of a “top score” signifies the measurable, objective outcome that this technological leap enabled.
The Evolving FICO Models
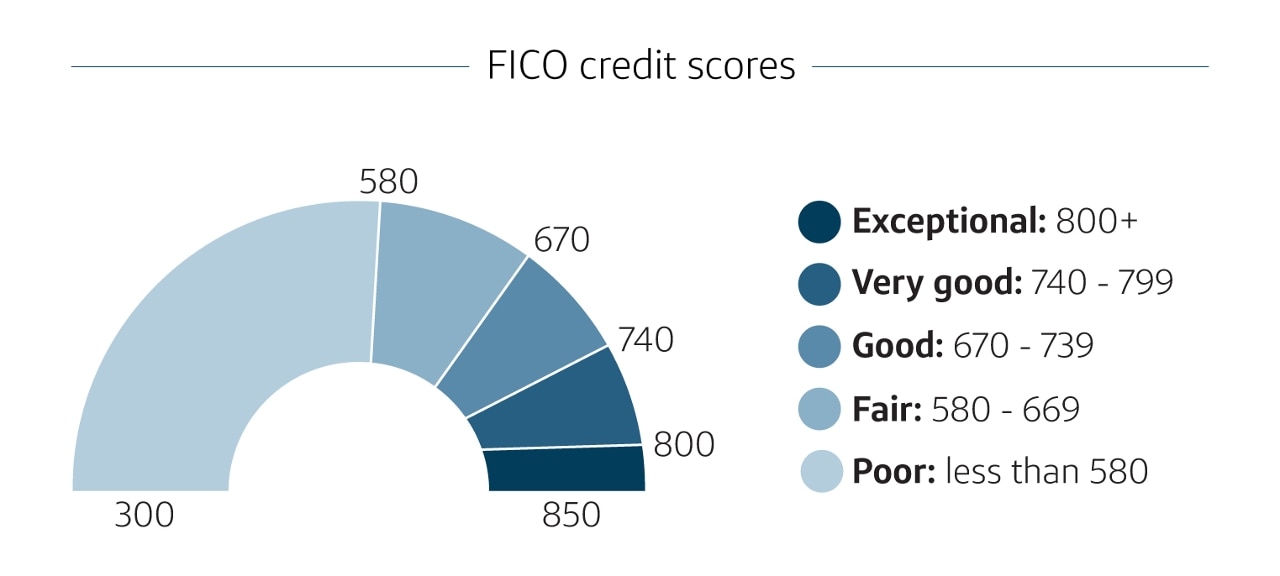
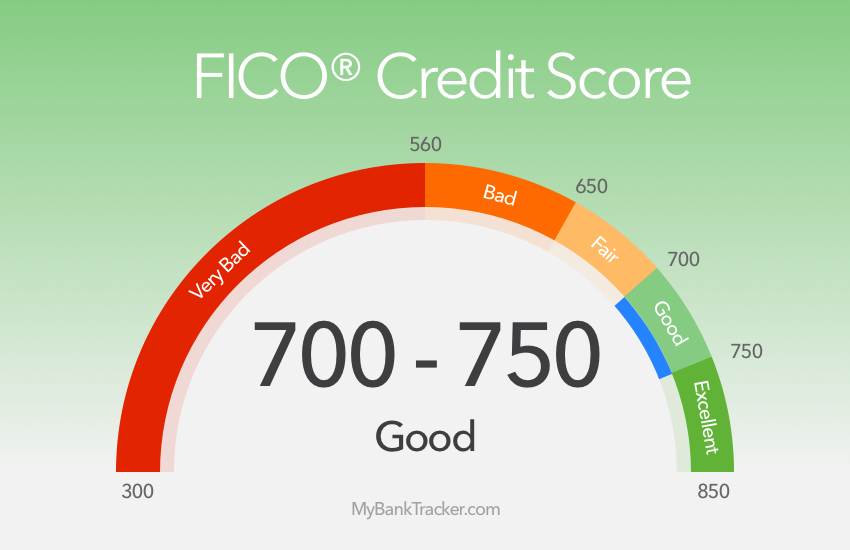
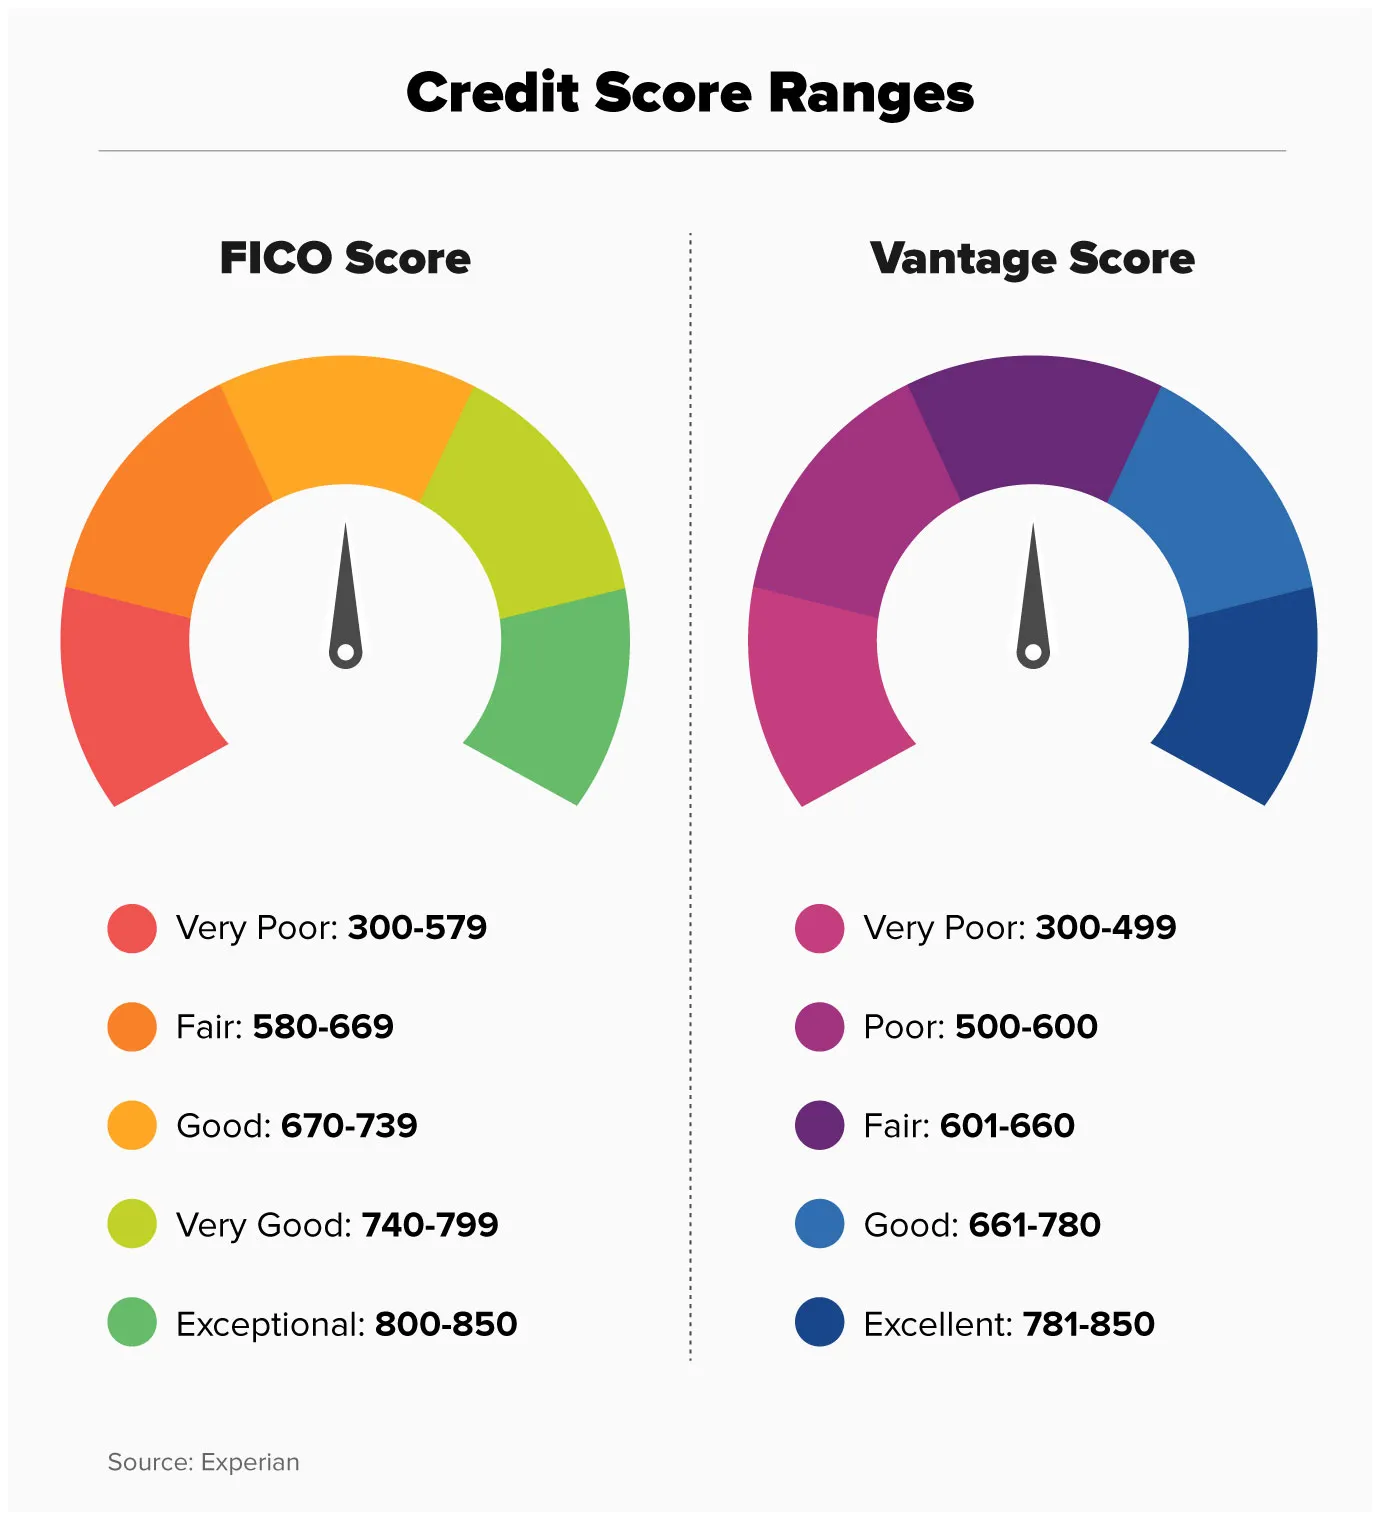
The FICO ecosystem is not static; it’s a dynamic field of ongoing technological refinement. Over the decades, Fair Isaac has released numerous versions of its scoring model, such as FICO Score 8, FICO Score 9, and the most recent FICO Score 10 T (T for “Trended Data”). Each iteration represents an evolution in data processing capabilities and predictive analytics. These newer models incorporate more nuanced data points and advanced statistical techniques to improve accuracy and reflect contemporary consumer financial behavior. For instance, FICO Score 10 T places greater emphasis on “trended data,” looking at how an applicant manages credit over time rather than just a snapshot, a testament to the continuous innovation in leveraging time-series data for more precise risk assessment. The “top score” thus isn’t a fixed target but rather the highest achievable score within the parameters of the most current and relevant FICO model employed by a lender. Generally, the standard FICO score range is 300 to 850, making 850 the undisputed top FICO score.
Decoding the Algorithmic Engine: Technology at Play
Achieving the top FICO score isn’t merely about good financial habits; it’s about understanding and optimizing one’s financial footprint within the sophisticated technological framework that FICO utilizes. At its core, FICO is a masterpiece of data science, predictive analytics, and algorithmic design.
Data Aggregation and Processing
The foundation of any FICO score lies in the meticulous aggregation and processing of extensive financial data. Credit bureaus (Equifax, Experian, TransUnion) serve as the primary repositories, collecting information from lenders, creditors, and public records. This colossal dataset includes payment history, amounts owed, length of credit history, new credit, and credit mix. FICO’s technology then ingests, cleanses, and structures this raw data to feed its proprietary algorithms. The sheer computational power required to handle millions of consumer profiles and billions of data points daily is immense, showcasing a continuous innovation in scalable data management systems essential for modern financial infrastructure.
Predictive Analytics and Machine Learning Principles
While FICO’s original models were rooted in advanced statistical regression, contemporary credit scoring increasingly incorporates principles from predictive analytics and machine learning. These technologies enable FICO to identify complex patterns and correlations within the vast datasets that might not be apparent through traditional statistical methods. The algorithms are designed to predict the likelihood of an individual defaulting on a loan within a specific timeframe. For instance, they learn which combinations of credit behaviors are most indicative of future risk or reliability. This sophisticated predictive modeling is what allows for the granular differentiation between, say, a score of 790 and a perfect 850, identifying subtle yet significant signals in a consumer’s financial behavior that contribute to their overall risk profile. The constant refinement of these models using new data and machine learning techniques ensures their relevance and accuracy in an ever-changing economic landscape.
Strategies for Scoring Excellence: Optimizing Your Digital Financial Footprint
Attaining the top FICO score of 850 is a rare feat, a testament to near-perfect financial management within the FICO algorithm’s parameters. It requires not just good habits, but a strategic understanding of how your financial actions translate into data points the algorithm evaluates.
Key Factors Influencing Your Score
FICO categorizes credit data into five primary factors, each weighted differently, providing a clear roadmap for optimization:
- Payment History (35%): This is the most crucial factor. A perfect payment history—never missing a payment on any account—is non-negotiable for an 850 score. Technology enables this data to be tracked precisely across all creditors, making every single payment (or missed one) a direct input into the algorithm.
- Amounts Owed (30%): This factor considers your credit utilization ratio, which is the amount of credit you’re using compared to your total available credit. Maintaining very low utilization (typically under 10% for excellent scores, and often under 1-2% for an 850) signals to the algorithm that you manage credit responsibly and are not over-reliant on it.
- Length of Credit History (15%): The older your accounts, the better. A long history of responsible credit use provides the algorithm with more data to assess your reliability. This factor naturally improves with time, showcasing consistent financial behavior over an extended period.
- New Credit (10%): Frequent applications for new credit can signal higher risk. The algorithm interprets multiple recent hard inquiries or opening many new accounts in a short period as potential financial distress. Strategic, infrequent opening of new accounts is key.
- Credit Mix (10%): Having a diverse portfolio of credit accounts (e.g., credit cards, installment loans, mortgages) demonstrates the ability to manage different types of credit responsibly. This shows a well-rounded and stable financial profile to the FICO model.
Cultivating Financial Habits for Algorithmic Advantage
Achieving and maintaining an 850 FICO score requires more than just avoiding mistakes; it demands proactive and consistent financial discipline. This includes always paying bills on time, keeping credit card balances exceptionally low, refraining from opening too many new credit lines, and maintaining a long average age of accounts. These habits create a pristine financial data profile that feeds the FICO algorithm with optimal inputs, demonstrating minimal risk. It’s an ongoing process of algorithmic optimization, where every financial decision contributes to the predictive model’s assessment of your creditworthiness.
The Pervasive Influence of FICO in the Modern Economy
The FICO score, a product of enduring financial technology and innovation, has permeated far beyond its initial application in mortgage lending. Its influence in the digital age is pervasive, shaping access to various financial products and services, and even extending into non-financial realms.
Beyond Lending: The Broader Implications
While primarily associated with loans and credit cards, a top FICO score can unlock a multitude of advantages. Landlords often use credit scores to screen tenants, insurance companies might factor them into premium calculations (known as credit-based insurance scores), and even utility providers may require deposits from individuals with lower scores. In the gig economy, some platforms might consider credit scores for certain roles. This widespread adoption underscores FICO’s success as a standardized, data-driven assessment tool. A perfect 850 score not only grants access to the most competitive interest rates and loan terms but also serves as a strong signal of financial reliability in a world increasingly reliant on automated background checks and data analytics.
Future Innovations in Credit Scoring
The field of credit scoring continues to evolve, driven by advancements in data science, artificial intelligence, and the availability of new data sources. While FICO remains dominant, alternative credit scoring models are emerging that incorporate non-traditional data—such as rent payments, utility bills, and even banking transaction data—to assess individuals with thin credit files or those outside the traditional credit system. These innovations aim to make credit more inclusive and accurate, leveraging big data and machine learning to paint a more complete picture of an individual’s financial behavior. The core technological challenge remains the same: how to best predict future financial behavior from available data. As technology progresses, the definition and achievement of a “top score” may broaden, encompassing more diverse forms of financial data and potentially even more sophisticated predictive algorithms, continuously pushing the boundaries of financial innovation.