
Navigating the complexities of Social Security benefits can be a daunting task, particularly when considering the various provisions for spouses. Spousal benefits are a crucial component of the Social Security system, designed to provide financial support to individuals whose working spouses contributed to the system. These benefits can significantly impact a couple’s retirement planning and offer a vital safety net. Understanding the eligibility criteria, calculation methods, and claiming strategies is essential for maximizing these provisions and ensuring financial security in retirement.
Eligibility Requirements for Spousal Benefits
To qualify for spousal benefits, both the claimant and their spouse must meet specific conditions set forth by the Social Security Administration (SSA). These requirements ensure that benefits are distributed fairly and in accordance with the program’s guidelines.
Marriage Duration
Generally, to claim spousal benefits, you must have been married to your spouse for at least one continuous year. This rule applies to current marriages. There are exceptions, such as if you are the parent of your spouse’s child, in which case the one-year marriage requirement may be waived.
Filing for Your Own Benefits
For your spouse to claim benefits based on your record, you must have already filed for your own retirement or disability benefits. If you have not yet filed, your spouse typically cannot claim benefits on your record, unless they are claiming divorced spousal benefits under specific conditions (discussed later).
Age Requirements
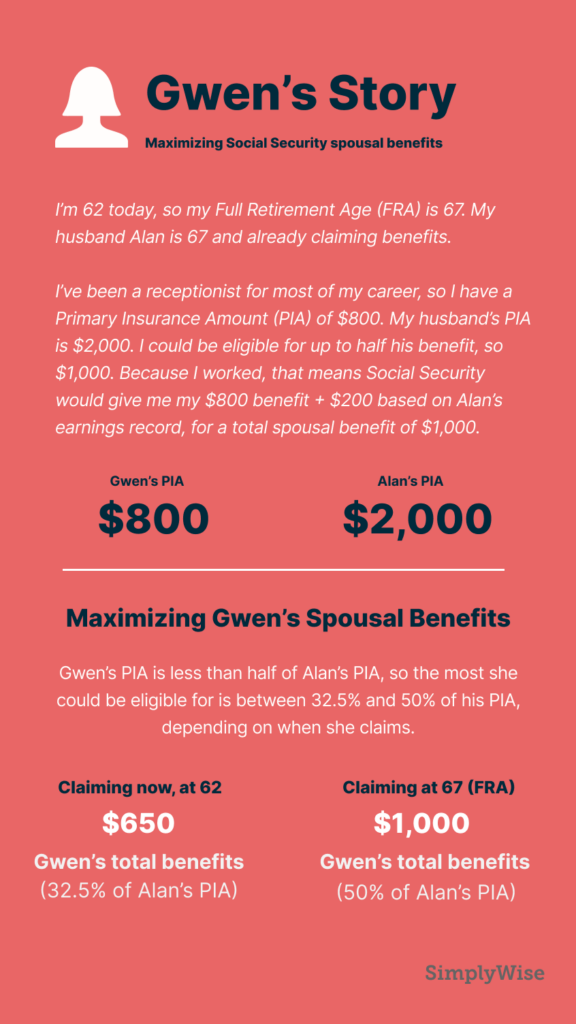
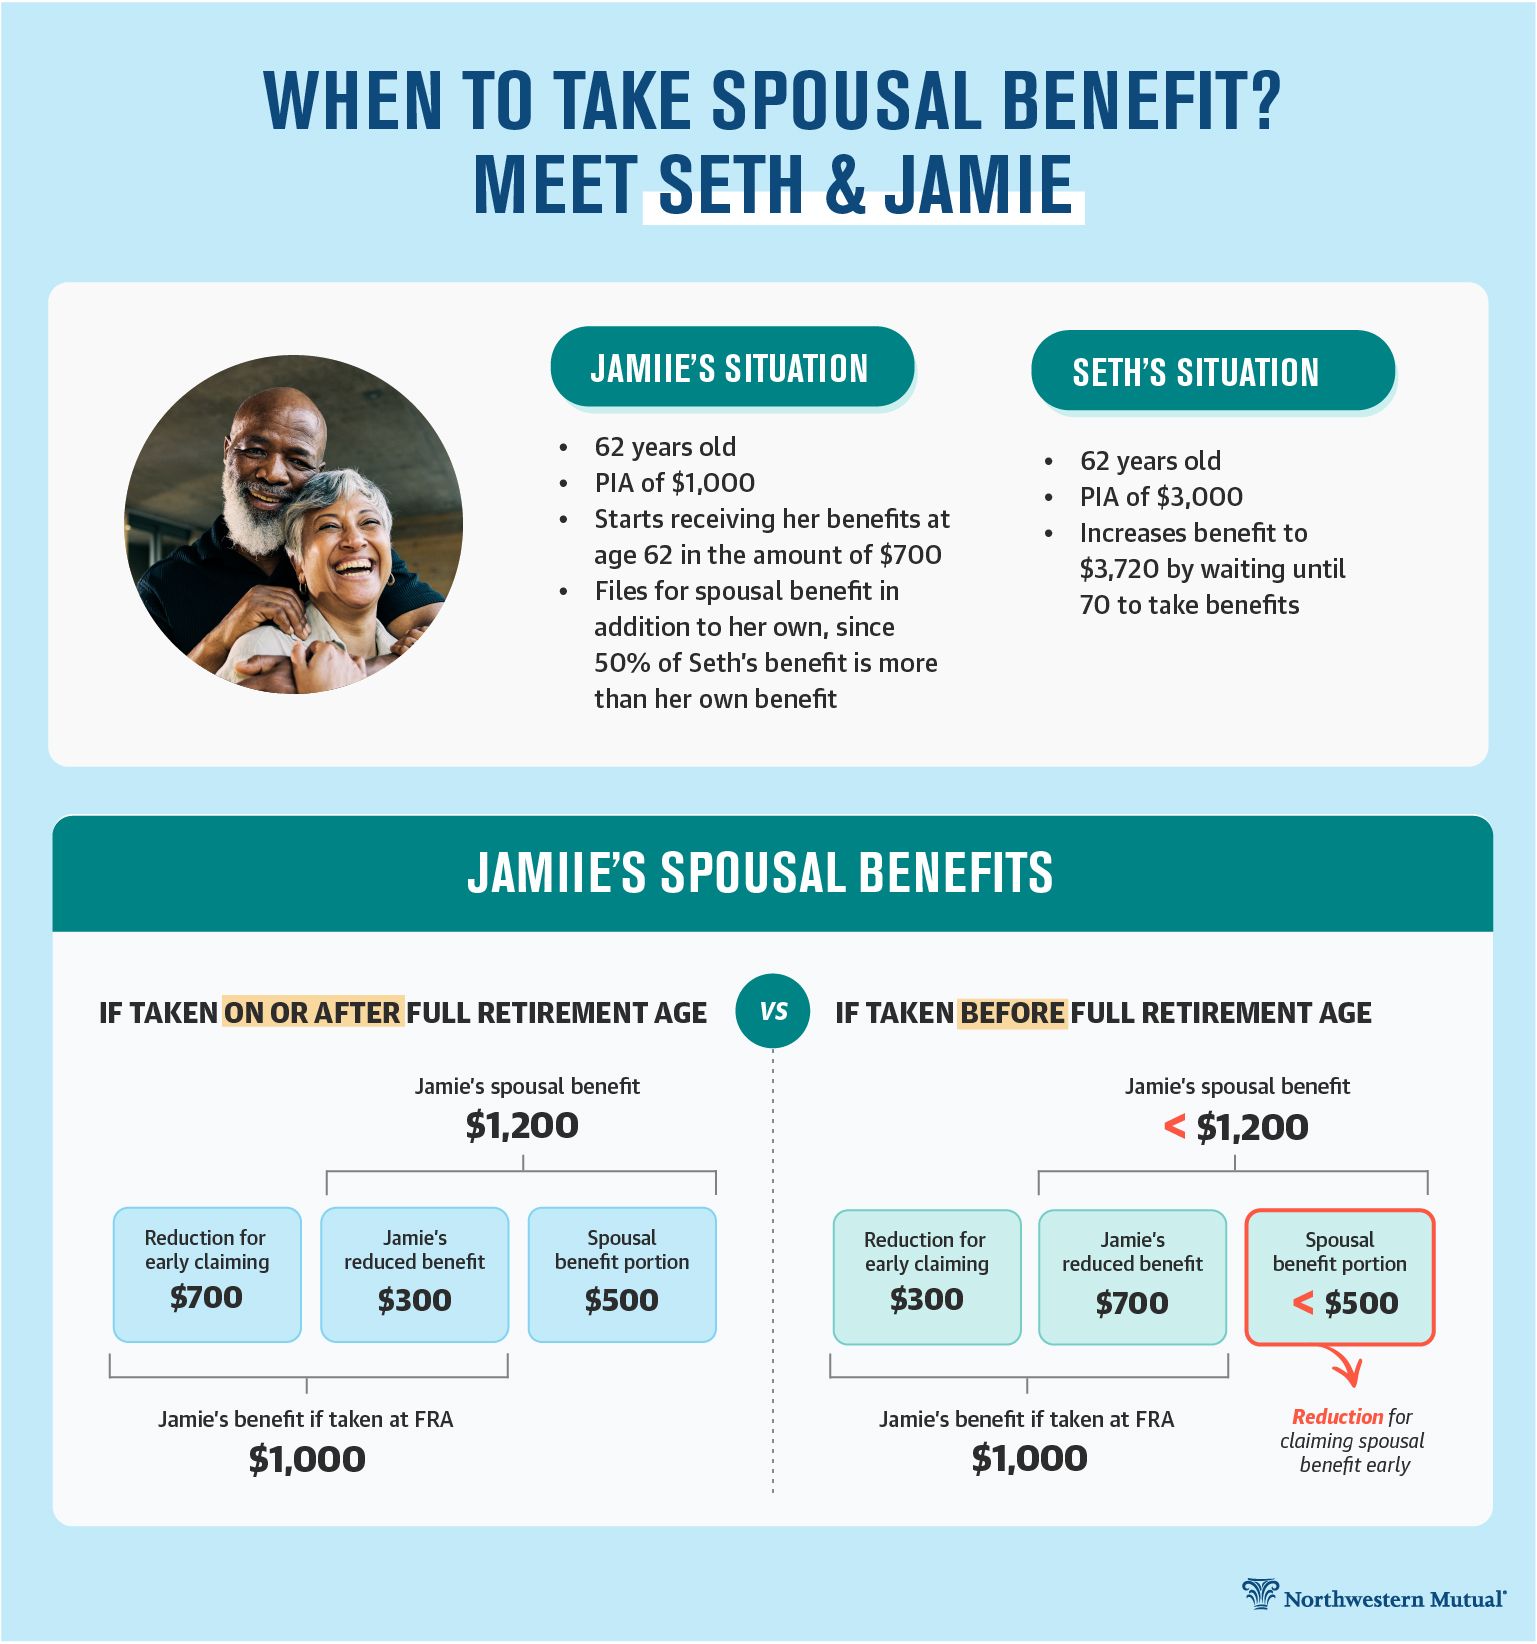
The earliest you can begin receiving spousal benefits is age 62, provided your spouse has already started receiving their own benefits. However, similar to individual retirement benefits, claiming spousal benefits before your Full Retirement Age (FRA) will result in a permanent reduction of your monthly benefit amount. Your FRA depends on your birth year, typically ranging from 66 to 67. If you wait until your FRA, you can receive 50% of your spouse’s primary insurance amount (PIA). Unlike individual retirement benefits, spousal benefits do not accrue delayed retirement credits beyond your FRA.
Deceased Spouse
If your spouse has passed away, you may be eligible for survivor benefits, which are a different category of benefits but operate similarly in some respects. Survivor benefits often provide a higher percentage of the deceased spouse’s benefit than standard spousal benefits. To qualify as a widow or widower, you generally must have been married for at least nine months prior to their death (exceptions apply).
How Spousal Benefits Are Calculated
The calculation of spousal benefits is directly tied to the primary earner’s work record and benefit amount. The goal is to provide a portion of the spouse’s benefit to ensure a baseline level of support.
Full Spousal Benefit Amount
A fully eligible spouse can receive a maximum of 50% of their spouse’s Primary Insurance Amount (PIA). The PIA is the amount of the worker’s full retirement benefit at their FRA. For example, if your spouse’s PIA is $2,000, your full spousal benefit would be $1,000. This 50% benefit is only available if you claim at your own Full Retirement Age.
Reduced Benefits and Filing Strategies
If you claim spousal benefits before your Full Retirement Age, the benefit amount will be permanently reduced. The reduction can be substantial; for instance, if your FRA is 67 and you claim at 62, your spousal benefit could be reduced by up to 35%, resulting in only 32.5% of your spouse’s PIA.
It’s important to note that if you are eligible for both your own Social Security retirement benefits and spousal benefits, the SSA will pay you an amount equal to the higher of the two. You generally cannot collect both in full. If your own benefit is less than 50% of your spouse’s PIA, Social Security will pay your own benefit first, and then add a “spousal top-up” to bring you up to the spousal benefit amount.

Claiming Spousal Benefits: Key Considerations
Strategic claiming of spousal benefits can significantly enhance a couple’s lifetime benefits. Over the years, Social Security rules regarding claiming strategies have evolved, making it crucial to understand the current regulations.
File and Suspend Strategy (Historically)
Historically, the “file and suspend” strategy allowed a worker to file for their retirement benefits at their FRA, immediately suspend them to earn delayed retirement credits, and enable their spouse to claim spousal benefits based on their record. This allowed the spouse to receive benefits while the worker’s own benefit continued to grow. This strategy was largely eliminated for new filers as of April 30, 2016.
Restricted Application Strategy (Historically)
Another strategy, the “restricted application,” allowed individuals born before January 2, 1954, to file a restricted application for spousal benefits only at their FRA, while allowing their own retirement benefit to continue growing with delayed retirement credits up to age 70. Once they reached age 70, they could then switch to their higher personal retirement benefit. This strategy is also no longer available for those born after January 1, 1954.
Current Rules for Claiming
Under current rules, if you are eligible for both your own retirement benefits and spousal benefits, you are generally deemed to have applied for both. The SSA will pay the higher of the two amounts. This “deemed filing” provision means you can no longer choose to claim only spousal benefits and let your own benefit grow, or vice-versa, if you are filing for benefits after the rule changes. The system automatically awards you the larger of the two benefits you are entitled to based on your age and filing status.
For most people, the decision revolves around when to start receiving benefits based on their own work record and their spouse’s. Coordinating these decisions can still lead to better outcomes. For instance, if one spouse has a significantly higher earning history, they might delay claiming their own benefits until age 70 to maximize delayed retirement credits, while the lower-earning spouse could claim their own benefits (or spousal benefits if their own is lower) earlier.
Divorced Spousal Benefits
Social Security also provides benefits for divorced spouses, offering a vital financial lifeline for individuals who meet specific criteria, even if their marriage has ended.
Eligibility for Divorced Spousal Benefits
To qualify for divorced spousal benefits, you must meet the following conditions:
- Your marriage lasted for at least 10 years.
- You are currently unmarried.
- You are age 62 or older.
- Your ex-spouse is entitled to Social Security retirement or disability benefits.
- The benefit you would receive based on your own work record is less than the benefit you would receive based on your ex-spouse’s record.
A unique aspect of divorced spousal benefits is that your ex-spouse does not need to have filed for their own benefits for you to claim benefits on their record, provided you have been divorced for at least two years. Your ex-spouse must be at least age 62, but they do not need to be actively receiving benefits for you to claim.
Impact on Ex-Spouse
Claiming divorced spousal benefits has absolutely no impact on your ex-spouse’s benefits or the benefits of their current spouse (if they have remarried). Your claim is entirely independent and does not diminish their entitlements in any way. This means an ex-spouse can claim benefits without needing their former partner’s permission or knowledge, and it won’t reduce the original earner’s or their new spouse’s benefits.
Understanding Your Options and Future Planning
Understanding spousal benefits is crucial for comprehensive retirement planning. Given the complexities and the impact of legislative changes, it is often advisable to consult with a financial advisor or the Social Security Administration directly. They can help you analyze your specific situation, project potential benefit amounts, and determine the optimal claiming strategy for you and your family. Proactive planning can help ensure that you maximize your Social Security entitlements and secure a more stable financial future.