
Apple Pay stands as a quintessential example of modern technological innovation, fundamentally reshaping how consumers interact with their finances and conduct transactions. Launched by Apple Inc. in 2014, it represents a pioneering step in the digital wallet and mobile payment landscape, leveraging sophisticated technological infrastructure to deliver unparalleled convenience, security, and privacy. More than just a payment method, Apple Pay is an integrated system designed to streamline financial interactions, making them faster, safer, and more intuitive for users across a multitude of devices and environments.
The Core Technological Infrastructure and Seamless User Experience
At its heart, Apple Pay is an intricate tapestry of hardware, software, and secure protocols working in concert to facilitate swift and secure digital transactions. Its architecture is built upon established industry standards while introducing innovative layers of security and user convenience.
NFC: The Foundation of Proximity Payments
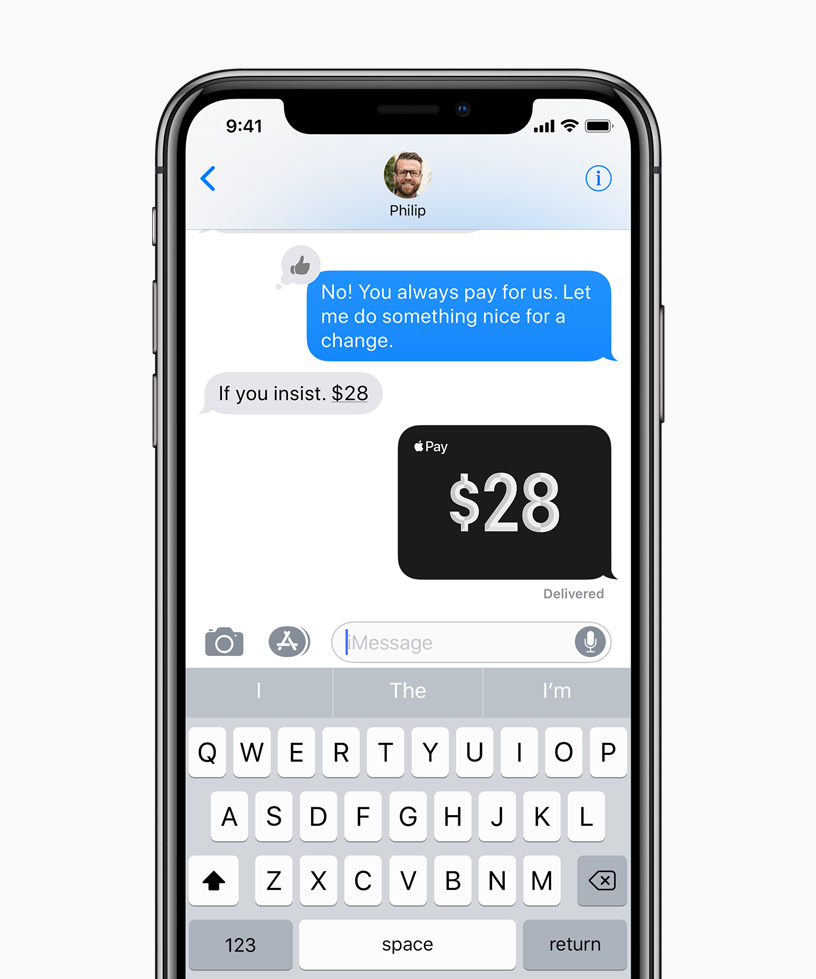
The primary enabler of Apple Pay for in-store purchases is Near Field Communication (NFC) technology. NFC is a short-range wireless connectivity standard that allows two electronic devices to communicate when they are brought within a few centimeters of each other. In the context of Apple Pay, this means an iPhone or Apple Watch can securely exchange data with a compatible point-of-sale (POS) terminal.
When a user wishes to make a purchase, they simply hold their enabled Apple device near an NFC-ready payment terminal. This initiates a rapid, encrypted data exchange, verifying the payment without the need for physical cards, swiping, or chip insertion. The “tap-to-pay” mechanism has revolutionized the checkout process, offering a frictionless experience that minimizes physical contact and speeds up transactions, a feature particularly valued in fast-paced retail environments and increasingly important in a hygiene-conscious world. The underlying NFC technology ensures that the communication is localized and secure, preventing unauthorized interception over longer distances, unlike some other wireless protocols.
The Digital Wallet Ecosystem
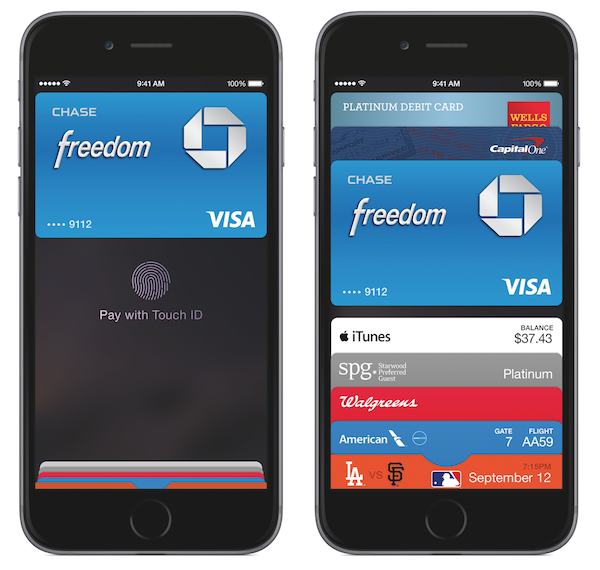
Central to the Apple Pay experience is the Wallet app, which serves as a secure, centralized hub for managing various digital assets. Users can provision their credit, debit, and prepaid cards from participating financial institutions directly into the Wallet app. This process involves a secure verification step with the bank, ensuring that only the legitimate cardholder can add a card.
Once a card is added, it becomes a “digital card” linked to the device, ready for use with Apple Pay. The Wallet app also extends its functionality beyond traditional payment cards, integrating transit passes, loyalty cards, event tickets, digital car keys, and even identification documents in select regions. This consolidation transforms the physical wallet into a digital counterpart, accessible and manageable from a single, intuitive interface on Apple devices like iPhones, Apple Watches, iPads, and Macs. The ease of adding and managing multiple cards and passes within a unified interface significantly enhances user convenience, making the Wallet app a powerful organizing tool for daily life.
Security and Privacy at the Forefront of Digital Transactions
Perhaps the most compelling aspect of Apple Pay, and a major driver of its widespread adoption, is its uncompromising focus on security and privacy. Unlike traditional payment methods that expose sensitive card details, Apple Pay employs a multi-layered security architecture designed to protect user data from compromise at every stage of a transaction.
Tokenization: Masking Sensitive Data
One of the cornerstone security features of Apple Pay is tokenization. When a user adds a credit or debit card to Apple Pay, the actual card number is not stored on the device, nor is it ever transmitted to the merchant during a transaction. Instead, Apple Pay assigns a unique, device-specific Device Account Number (DAN) for each card. This DAN is encrypted and securely stored in the device’s Secure Element.
During a transaction, it is this DAN, along with a dynamic, transaction-specific cryptogram, that is sent to the merchant and then to the payment network. If intercepted, this tokenized data is useless to potential fraudsters because it cannot be reverse-engineered to reveal the actual card number. Each transaction generates a unique cryptogram, meaning that even if one transaction’s data were compromised, it could not be used to authorize subsequent transactions. This effectively severs the link between the payment and the user’s actual card details, drastically reducing the risk of fraud associated with data breaches at merchant terminals.
Biometric Authentication and Secure Element
Further fortifying Apple Pay’s security is its integration with biometric authentication methods and a dedicated hardware component known as the Secure Element (SE). To authorize any payment, users must authenticate themselves using Touch ID (fingerprint recognition) or Face ID (facial recognition), ensuring that only the device owner can initiate a transaction. This multi-factor authentication process adds a powerful layer of personal security, far surpassing the protection offered by a simple signature or PIN.

The Secure Element is a specialized, tamper-resistant chip embedded within the Apple device, specifically designed to store sensitive data like the Device Account Numbers and cryptographic keys in an isolated, highly protected environment. This hardware-level security ensures that payment information is never stored on Apple servers or accessible by the device’s main operating system or other applications. The SE operates independently, providing a secure enclave that is certified to meet stringent industry standards, offering a robust defense against software vulnerabilities and physical tampering attempts.
Privacy by Design
Beyond security, Apple Pay is engineered with privacy at its core. Apple explicitly states that it does not track users’ purchases, transaction history, or locations when Apple Pay is used. Transaction details remain private between the user, their bank, and the merchant. Apple does not retain any transaction information that can be tied back to the user, ensuring a high degree of anonymity in payment processing. This commitment to privacy aligns with Apple’s broader philosophy of user data protection, setting a high standard for digital payment solutions.
Market Adoption, Evolution, and Broadening Utility
Since its debut, Apple Pay has seen significant market adoption and has continuously evolved, expanding its utility far beyond initial expectations. Its impact has been profound, influencing both consumer behavior and the broader payment industry.
From Retail to Online: Expanding Payment Horizons
Initially, Apple Pay’s primary focus was on simplifying in-store, contactless payments via NFC. However, its capabilities rapidly expanded to encompass online transactions. Users can now “Pay with Apple Pay” within compatible apps and on websites through Safari. This functionality eliminates the cumbersome process of manually entering card numbers, expiration dates, and billing/shipping addresses. With a single authentication via Touch ID or Face ID, users can complete online purchases swiftly and securely, enhancing the e-commerce experience and significantly reducing checkout abandonment rates. The integration across various digital touchpoints has made Apple Pay a versatile tool for both physical and virtual commerce.
Beyond Traditional Payments: The Expanding Digital Wallet
The vision for Apple Pay has grown to encompass more than just credit and debit card transactions. The Wallet app has transformed into a comprehensive digital utility, integrating a wide array of passes and functionalities. Users can add transit cards for seamless public transportation, such as Japan’s Suica, New York’s OMNY, or the San Francisco Bay Area’s Clipper. The advent of digital car keys and home keys allows compatible vehicles and smart locks to be accessed and operated directly from an iPhone or Apple Watch. Furthermore, student IDs and corporate badges can be added, streamlining campus and office access. The integration of loyalty and rewards programs means users can automatically earn points or apply discounts without needing to present physical cards. Most recently, the introduction of Apple Pay Later offers a “buy now, pay later” service, further embedding Apple into the broader financial ecosystem. This continuous expansion showcases Apple Pay’s ambition to be the indispensable digital repository for all critical access and payment credentials.
Global Reach and Regulatory Landscape
Apple Pay has achieved significant global reach, expanding its services to numerous countries and regions worldwide. This global expansion, however, presents unique challenges, as it requires navigating diverse financial regulations, varying payment infrastructures, and different cultural preferences. Each new market necessitates partnerships with local banks, payment networks, and transit authorities, adapting the service to local customs and legal frameworks. Despite these complexities, Apple Pay has demonstrated remarkable success in establishing itself as a leading digital payment solution across continents, driving the global trend towards contactless and mobile-first transactions.
The Innovative Impact and Future Trajectory
Apple Pay’s influence extends beyond its immediate utility, fundamentally reshaping consumer expectations and driving innovation across the payment industry. It stands as a testament to how thoughtful technology design can create substantial societal and economic impact.
Reshaping Consumer Expectations
Apple Pay has played a pivotal role in accelerating the global shift towards contactless payments. Its intuitive interface and robust security features have made “tapping to pay” a widely accepted and preferred method, fostering a generation of consumers who expect speed, convenience, and security in their transactions. This shift has, in turn, pressured merchants to upgrade their POS systems and financial institutions to support digital wallet solutions, ultimately modernizing the entire payment ecosystem. The ease with which transactions are completed, coupled with the inherent security, has raised the bar for what consumers expect from any payment method, driving competitors to innovate and enhance their own offerings.
Upcoming Innovations and Ecosystem Enhancements
The trajectory of Apple Pay suggests a continued focus on expanding its reach and refining its utility. One significant innovation is “Tap to Pay on iPhone,” which allows businesses to accept contactless payments directly on their iPhone, without requiring additional hardware like card readers. This transforms the iPhone into a mobile POS terminal, democratizing payment acceptance for small businesses and independent merchants.
Looking ahead, Apple Pay could see deeper integration with emerging technologies such as augmented reality (AR) and virtual reality (VR), creating new commerce experiences where payments are even more seamlessly embedded into digital environments. Continued focus on decentralization and enhanced user control over financial data is also anticipated, aligning with broader trends in digital privacy. While challenges from new payment technologies like cryptocurrencies and competing digital wallets persist, Apple Pay’s robust infrastructure, vast user base, and continuous innovation position it to remain a dominant force in the future of digital finance. Its evolution underscores a commitment to integrating cutting-edge technology to simplify, secure, and enhance every aspect of the payment experience.