
Certificates of Deposit (CDs) represent a foundational yet often misunderstood component of personal finance and investment strategies. Essentially, a CD is a type of savings account that holds a fixed amount of money for a fixed period of time, such as six months, one year, or five years. In exchange for keeping your money untouched for the agreed-upon term, the issuing bank pays you interest, typically at a higher rate than a standard savings account. The term “bank CD rates” refers specifically to these interest rates offered by financial institutions for their various CD products. Understanding these rates, the factors that influence them, and how they fit into a broader financial plan is crucial for individuals seeking stable, predictable returns on their savings.

Understanding Certificates of Deposit (CDs)
A Certificate of Deposit is a time deposit, meaning the money must remain deposited for a specific duration to earn the full interest agreed upon. When you open a CD, you are essentially lending money to the bank for a set period. In return, the bank guarantees a fixed interest rate for the entire term. This predictability is a key appeal of CDs, especially for risk-averse investors. Unlike stocks or mutual funds, the principal invested in a CD is typically insured by the Federal Deposit Insurance Corporation (FDIC) for up to $250,000 per depositor, per insured bank, in the event of bank failure. This makes CDs an extremely safe investment vehicle.
The core components of a CD are:
- Principal: The initial amount of money deposited into the CD.
- Term: The fixed period for which the money is deposited, ranging from a few months to several years.
- Interest Rate: The fixed annual percentage yield (APY) that the bank pays on the principal.
- Maturity Date: The date when the CD term ends, and you can withdraw your principal and accumulated interest without penalty.
Should you need to withdraw funds before the maturity date, most banks impose an early withdrawal penalty. This penalty typically involves forfeiting a portion of the interest earned or even a portion of the principal in extreme cases. This deterrent reinforces the “time deposit” nature of CDs and ensures investors commit to the full term.
Factors Influencing CD Rates
CD rates are not static; they fluctuate based on a variety of economic and market conditions. Understanding these underlying factors can help investors anticipate changes and make informed decisions about when to lock in a rate.
Federal Reserve Policy and Interest Rates
The most significant influencer of CD rates is the monetary policy set by the Federal Reserve (the Fed) in the United States. When the Fed raises its benchmark interest rate (the federal funds rate), it generally costs banks more to borrow money. To attract deposits and fund their lending activities, banks often respond by increasing the interest rates they offer on savings products, including CDs. Conversely, when the Fed lowers interest rates, CD rates tend to fall. This direct correlation makes Fed announcements a critical point of attention for CD investors.
Economic Outlook and Inflation
The broader economic environment also plays a vital role. During periods of strong economic growth and higher inflation expectations, banks may offer higher CD rates to compensate depositors for the reduced purchasing power of future money. If inflation is expected to be low, the real return on a CD (after accounting for inflation) might still be attractive even with lower nominal rates. Conversely, in a recessionary environment, with lower demand for loans, banks might decrease CD rates as they have less need for deposits.
Market Competition
The competitive landscape among banks and credit unions significantly impacts CD rates. If one bank offers particularly attractive rates, others may follow suit to retain or attract customers. Online banks, with lower overhead costs, often offer higher CD rates compared to traditional brick-and-mortar institutions, leading to increased competition in the digital banking space. Investors benefit from shopping around and comparing rates from various institutions to find the best available offers.
CD Term Length
Generally, the longer the CD term, the higher the interest rate offered by the bank. This is because banks are willing to pay more for the certainty of having your money for an extended period, which they can then use for longer-term lending and investments. A 5-year CD, for instance, will almost always offer a higher rate than a 6-month CD from the same institution. However, this also means locking in your money for longer, which might expose you to opportunity cost if rates rise significantly during your CD term.
Types of CDs and Their Rates
Beyond the standard fixed-rate CD, banks offer several variations designed to meet diverse financial needs and risk appetites. Each type comes with its own rate structure and unique features.
Standard Fixed-Rate CDs
This is the most common type. You deposit a lump sum, agree to a fixed term, and earn a fixed interest rate until maturity. The predictability of the return and the principal protection are its main advantages. Rates vary based on term length and the bank’s offerings.
Jumbo CDs
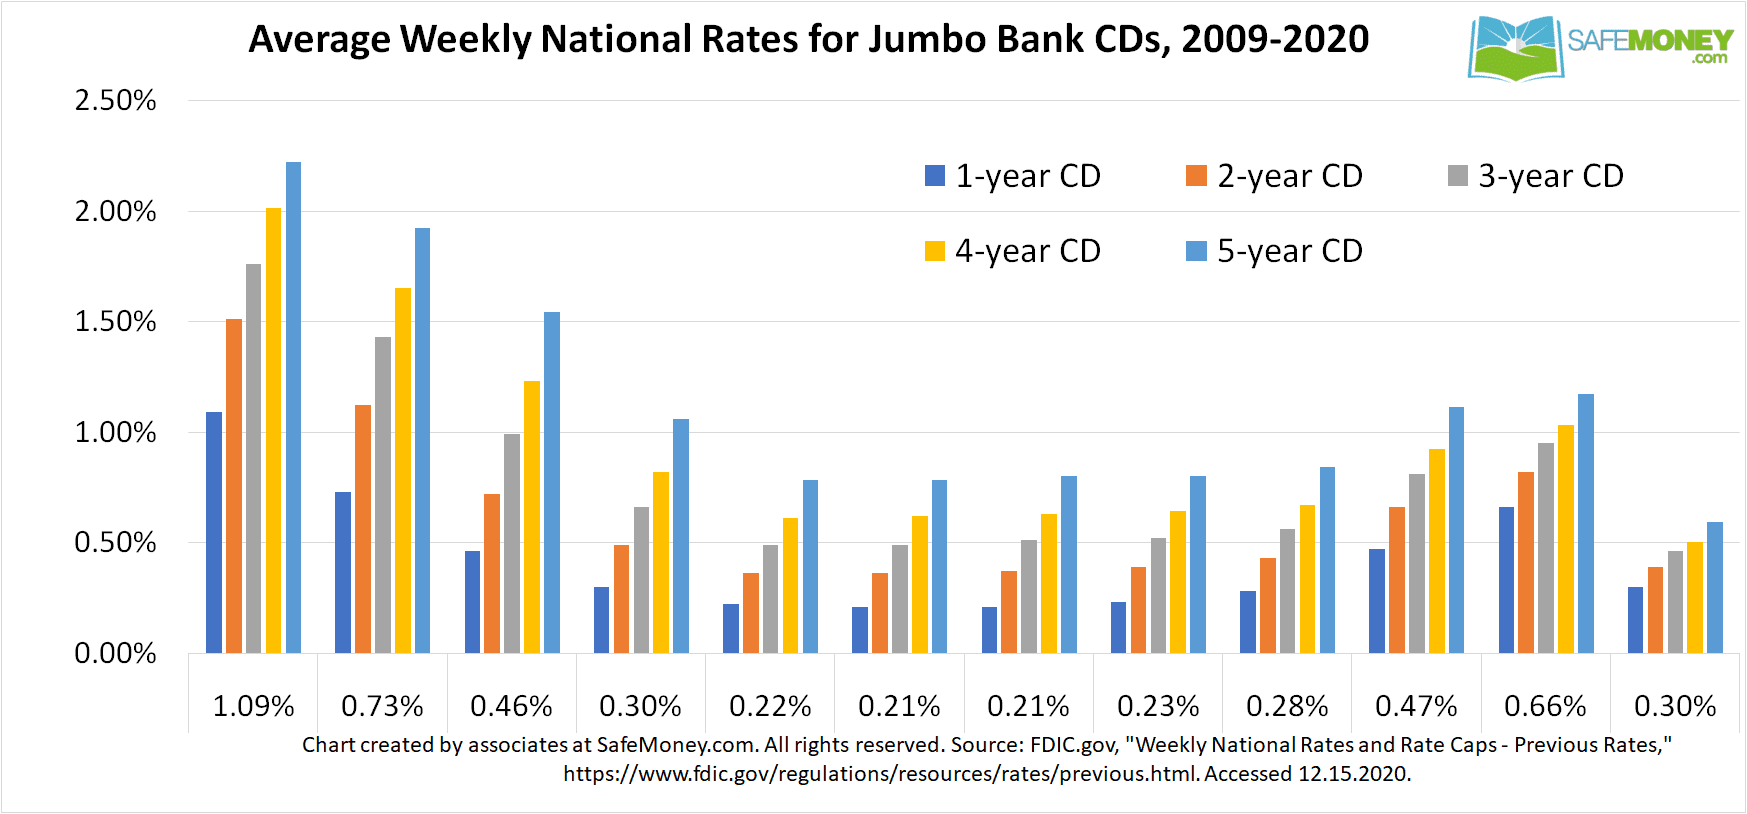
These are standard CDs but require a much larger minimum deposit, typically $100,000 or more. In exchange for the larger deposit, jumbo CDs often offer slightly higher interest rates than regular CDs of the same term. They are popular among institutional investors or high-net-worth individuals.

Callable CDs
With a callable CD, the issuing bank has the option to “call” or redeem the CD before its maturity date. If interest rates fall significantly, the bank might call the CD to avoid paying a higher fixed rate. While callable CDs often offer higher rates initially to compensate for this risk, they introduce uncertainty for the investor.
Brokered CDs
These CDs are issued by banks but sold through brokerage firms. They can offer a wider range of terms and potentially higher rates than those offered directly by traditional banks. Brokered CDs can also allow for greater diversification across multiple issuing banks, providing additional FDIC insurance coverage. However, they may involve brokerage fees and can sometimes be more complex in their redemption or secondary market trading.
Liquid (No-Penalty) CDs
As the name suggests, a liquid CD allows you to withdraw your money before maturity without incurring an early withdrawal penalty, usually after an initial waiting period (e.g., 7 days). While this flexibility comes at the cost of a slightly lower interest rate compared to a traditional fixed-rate CD of the same term, it offers a valuable option for those who want better returns than a savings account but might need access to their funds.
Step-Up and Bump-Up CDs
These CDs offer the potential for rate increases during the term.
- Bump-Up CDs: Allow the investor a one-time (or sometimes limited) option to “bump up” their interest rate if the bank’s rates for new CDs rise during the term. This provides a hedge against rising interest rates.
- Step-Up CDs: Automatically increase their interest rate at pre-determined intervals throughout the CD’s term. While the initial rate might be lower, the guaranteed increases can make them attractive in a rising rate environment.
Strategic Investment: Maximizing CD Returns
Investing in CDs effectively requires more than simply choosing the highest rate. A strategic approach can help maximize returns while managing liquidity needs.
CD Ladders
A popular strategy for CD investors is building a “CD ladder.” This involves dividing your total investment into several CDs with staggered maturity dates. For example, if you have $50,000 to invest and want to build a 5-year ladder, you might buy five $10,000 CDs maturing in one, two, three, four, and five years, respectively. As each CD matures, you can then reinvest the principal and interest into a new 5-year CD. This strategy offers several benefits:
- Liquidity: A portion of your money becomes available at regular intervals.
- Interest Rate Averaging: You benefit from both short-term rates (for liquidity) and long-term rates (which are usually higher), and you regularly capture new, potentially higher rates as they become available.
- Flexibility: You avoid locking all your money into a single rate for a long period, which could be disadvantageous if rates rise.
Shopping Around for Rates
It’s critical to compare CD rates from various financial institutions. Online banks, credit unions, and local banks often have different rate offerings. Online banks, due to their lower operating costs, frequently provide some of the most competitive rates. Credit unions are also known for competitive rates and often offer a more personalized customer experience. Utilizing online comparison tools can help identify the best rates across the market.
Considering Tax Implications
Interest earned on CDs is taxable at the federal level and potentially at state and local levels as ordinary income in the year it’s earned (or constructively received). For individuals in higher tax brackets, the after-tax return on a CD might be less attractive. For those nearing retirement or in lower tax brackets, CDs can still be a valuable, low-risk component of their portfolio. Some investors also consider investing in municipal bonds if tax-free income is a priority, but these carry different risks than FDIC-insured CDs.
The Role of CDs in a Diversified Portfolio
While CDs are generally considered conservative investments, they play a crucial role in a well-diversified financial portfolio. They serve as a safe haven for cash, providing capital preservation and predictable income, especially in volatile market conditions.
Capital Preservation and Stability
For investors primarily focused on protecting their principal, CDs are an excellent choice. The FDIC insurance provides a robust safety net, making them virtually risk-free from a credit perspective. This makes CDs suitable for emergency funds or money earmarked for specific short-term goals where preserving the principal is paramount.
Income Generation
CDs provide a steady stream of income through interest payments. While the rates may not always compete with the potential returns of riskier assets like stocks, the guaranteed nature of the income is invaluable. For retirees or those living on fixed incomes, CDs can supplement other income sources with minimal risk.
Diversification
A diversified portfolio should ideally include a mix of assets with varying risk and return profiles. CDs provide a low-risk component that can balance out higher-risk investments like stocks. When the stock market experiences downturns, the value of your CD investments remains stable, offering a counterbalance and potentially reducing overall portfolio volatility.
Short to Medium-Term Goals
CDs are ideal for saving for specific financial goals that are a few months to a few years away. Whether it’s a down payment on a house, a child’s college fund, or a planned major purchase, locking in funds in a CD ensures the money is available when needed without being subject to market fluctuations. The fixed term helps enforce savings discipline, preventing impulsive spending of earmarked funds.
In conclusion, bank CD rates are a critical element for anyone looking to build a secure and balanced financial future. By understanding the types of CDs available, the economic forces that shape their rates, and strategic approaches like CD ladders, investors can effectively leverage these products to preserve capital, generate stable income, and diversify their portfolios against market uncertainties.