The Apple Card, introduced by Apple in partnership with Goldman Sachs and Mastercard, represents more than just another credit card; it embodies a significant stride in the realm of financial technology and user-centric innovation. At its core, the Apple Card is a digital-first credit card designed to seamlessly integrate with the Apple ecosystem, leveraging the company’s prowess in hardware, software, and services to redefine the consumer credit experience. It is a testament to how established technology firms can disrupt traditional industries by focusing on security, privacy, transparency, and an intuitive user interface, pushing the boundaries of what a credit card can be in the digital age.
The Technological Core of a Modern Credit Card
Apple’s approach to the credit card market was not merely to offer a new financial product but to re-engineer the entire user experience from the ground up, placing technology at the forefront. This digital-first philosophy permeates every aspect of the Apple Card, from its application process to transaction management and rewards.
Digital-First Design and Onboarding
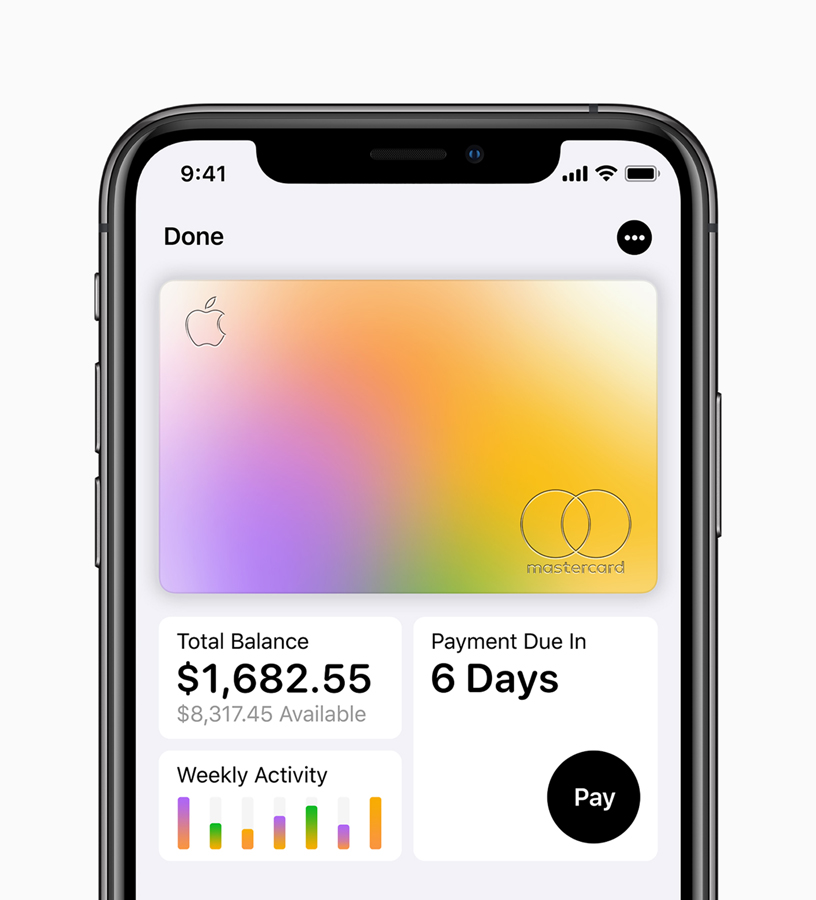
The Apple Card distinguishes itself immediately through its entirely digital application and approval process, facilitated within the Wallet app on an iPhone. This eliminates traditional paperwork, lengthy waits, and physical mail correspondence. Users can apply in minutes, often receiving approval and immediate access to their digital card for online and Apple Pay purchases almost instantly. This rapid, friction-free onboarding is a direct result of sophisticated backend technology, including secure identity verification protocols and real-time credit assessment algorithms, all orchestrated to provide a seamless user experience that is characteristic of Apple’s product design principles. The digital card resides securely in the Wallet app, ready for use with Apple Pay wherever it is accepted, making it instantly accessible and a primary payment method for many users.
The Physical Card as a Statement of Design and Tech
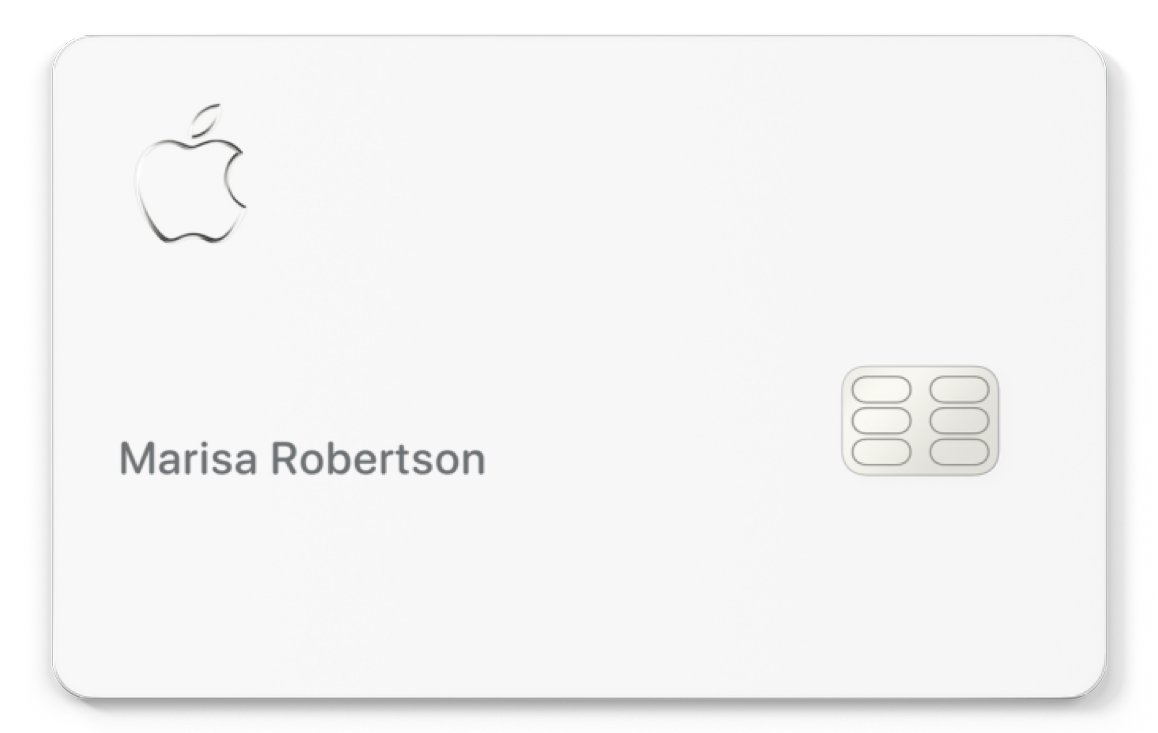
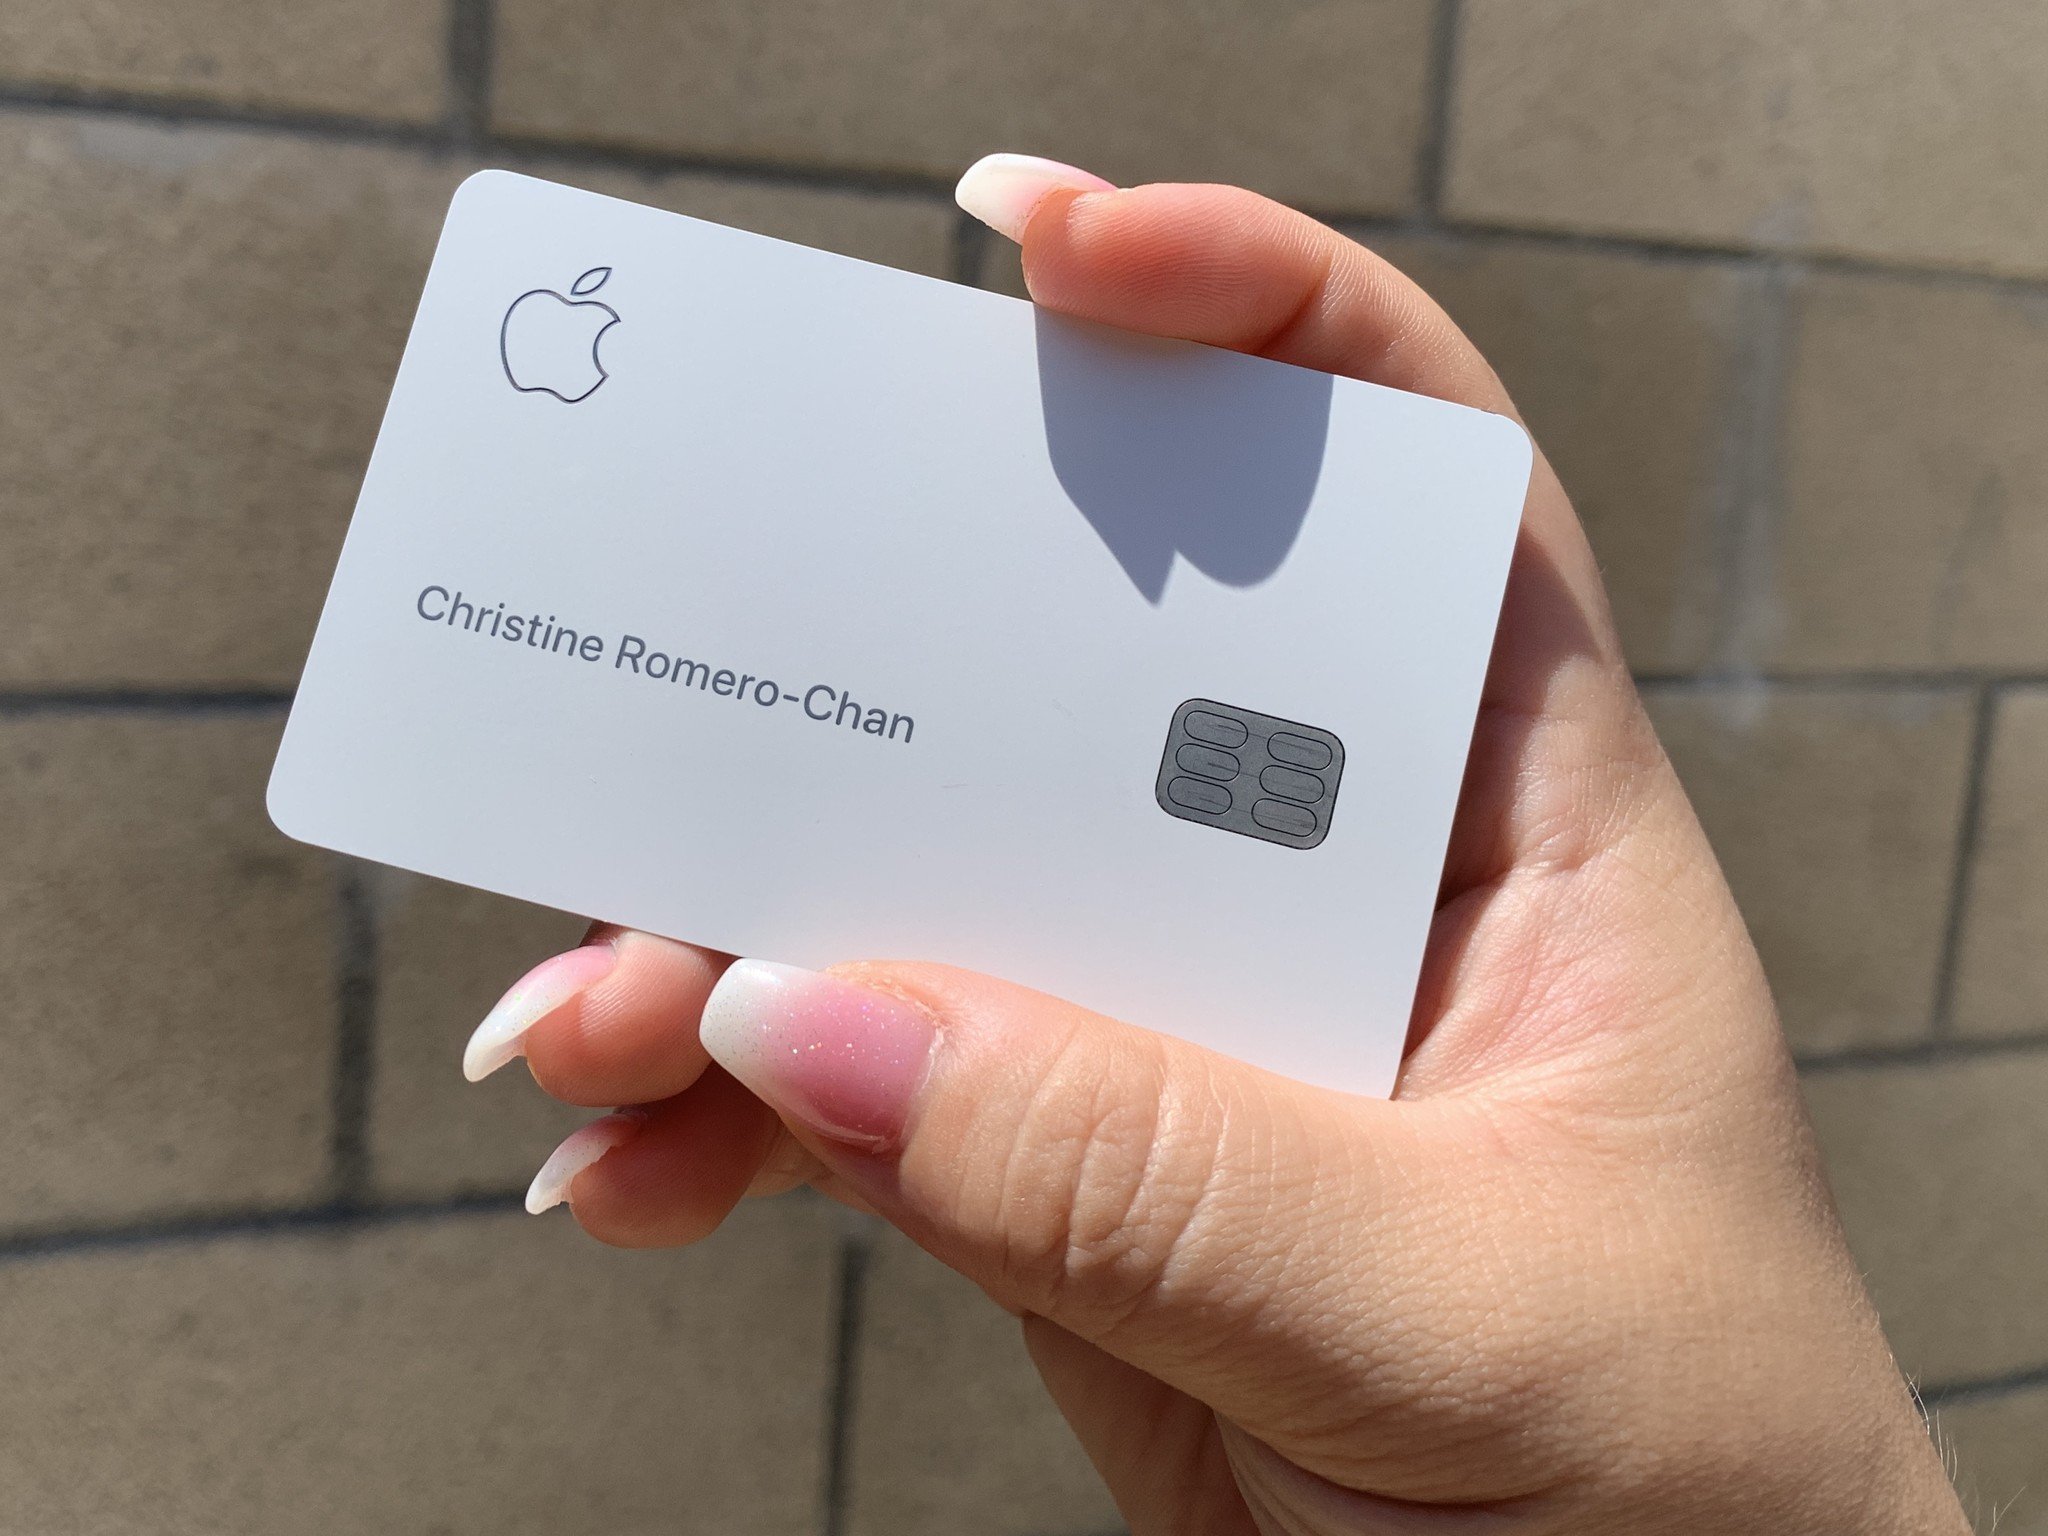
While primarily a digital product, Apple also offers a physical titanium card for situations where Apple Pay is not yet available. This physical card itself is a piece of minimalist technological design. Unlike traditional credit cards, it bears no card number, CVV security code, expiration date, or signature. Instead, this sensitive information is stored securely within the Wallet app and linked to the user’s Apple ID, accessible only after biometric authentication (Face ID or Touch ID). The card number associated with the physical card is unique to the device, further enhancing security by minimizing the exposure of core financial data. The absence of printed details not only contributes to its sleek aesthetic but also significantly reduces the risk of sensitive information being compromised through visual inspection or theft of the physical card. It serves as a physical manifestation of Apple’s commitment to privacy and security through design.
Innovation in Security and Privacy
Security and privacy have been paramount in the development of the Apple Card, reflecting Apple’s broader commitment to these principles across its product ecosystem. The card integrates several advanced technological features that set new benchmarks for consumer credit security.
Unique Device Account Numbers and Tokenization
Every Apple Card purchase made with Apple Pay utilizes a unique, single-use transaction code generated on the user’s device, alongside a specific Device Account Number. This tokenization process means that the actual card number is never stored on the device or Apple servers, nor is it transmitted to merchants during transactions. This cryptographic separation ensures that even if a merchant’s system is compromised, the exposed data cannot be linked back to the user’s actual credit card number, significantly reducing the risk of fraud. This method of securing transactions far surpasses the capabilities of traditional magnetic stripe or even chip-and-PIN cards, which still transmit static card numbers.
Secure Enclave and Biometric Authentication
The core of the Apple Card’s security architecture is deeply rooted in the iPhone’s Secure Enclave, a dedicated, isolated hardware component that stores and processes sensitive data, including biometric information (Face ID/Touch ID) and cryptographic keys, in an encrypted environment. All transactions and access to card details within the Wallet app require biometric authentication, ensuring that only the authorized user can initiate payments or view sensitive information. This hardware-level security provides a formidable barrier against unauthorized access, making it significantly more secure than simply requiring a PIN or signature. The Secure Enclave’s isolation from the main operating system prevents malware or unauthorized software from accessing critical financial data, a level of protection rarely seen in traditional payment systems.
Dynamic Security Codes
For online purchases where Apple Pay might not be an option, the Apple Card generates dynamic security codes (CVVs) within the Wallet app. Unlike static CVV codes found on physical cards, these codes change regularly, providing an additional layer of security against online fraud. A stolen or compromised dynamic CVV is valid for a limited time, making it much harder for fraudsters to use stolen card details for multiple unauthorized transactions. This feature addresses one of the major vulnerabilities of online credit card usage, where static security codes are often the weakest link.
Privacy by Design
Apple explicitly states that it does not know where users shop, what they buy, or how much they spend. Transaction data is processed on the device itself and not by Apple. While Goldman Sachs, as the issuing bank, has access to transaction data for regulatory and operational purposes, it is contractually prohibited from selling or sharing this data for marketing or advertising. This “privacy by design” approach aims to instill user trust by limiting data aggregation and monetization, a stark contrast to many other financial services that often leverage consumer data for targeted advertising or other commercial purposes.
Seamless Integration and User Experience
The Apple Card’s technological innovations extend beyond security into creating an unparalleled user experience, deeply integrated into the iOS platform.
The Wallet App as a Control Hub
The Wallet app on the iPhone serves as the central hub for managing the Apple Card. It offers a comprehensive, real-time view of spending, balances, payments, and rewards. This intuitive interface replaces the need for separate bank apps or clunky web portals, consolidating all essential information in one place. Users can instantly see their credit limit, available credit, current balance, and even a visual representation of their spending across different categories. This level of immediate, consolidated insight into one’s financial activity is a significant technological leap from traditional monthly statements or delayed online banking updates.
Real-time Transaction Tracking
One of the most praised features of the Apple Card is its real-time transaction tracking and categorization. Every purchase appears instantly in the Wallet app, often with the merchant’s name and location clearly displayed on a map. Transactions are automatically categorized (e.g., Food & Drink, Shopping, Services) and color-coded, providing an immediate visual breakdown of spending patterns. This real-time data flow is powered by sophisticated backend processing that quickly clears and categorizes transactions, allowing users to stay on top of their finances without delay. This proactive notification and categorization empower users with immediate financial awareness, a significant improvement over waiting days for transactions to post.
AI-Powered Spending Insights
Beyond simple categorization, the Wallet app uses machine learning to provide insightful breakdowns of spending. Users can view their weekly or monthly spending totals, track trends, and identify areas where they might be overspending. The interactive interface allows users to tap on categories to drill down into specific transactions. While not explicitly branded as AI, the underlying algorithms that categorize transactions, identify merchants (even when transaction data is ambiguous), and present spending patterns are forms of intelligent automation designed to simplify financial management and provide actionable insights, effectively acting as a personal finance assistant within the Wallet app.
Redefining Rewards and Financial Management with Technology
The Apple Card also innovates in how it delivers rewards and facilitates financial management, leveraging technology for transparency and immediacy.
Daily Cash: Instantaneous Digital Rewards
Instead of complex points systems or delayed statement credits, the Apple Card offers Daily Cash, a straightforward cash back program where rewards are added to the user’s Apple Cash card within the Wallet app every day. This immediate gratification of rewards (3% on Apple purchases, 2% on Apple Pay purchases, 1% on physical card purchases) is a unique technological feature. The instant transfer of funds into Apple Cash allows users to spend their rewards immediately via Apple Pay, send them to friends, or transfer them to a bank account. This instantaneous delivery mechanism is a direct result of advanced real-time processing and integration between the credit card system and the Apple Cash platform, eliminating the typical lag associated with traditional rewards programs.
Goal-Setting and Budgeting Tools
While not a full-fledged budgeting app, the Apple Card within the Wallet app provides intuitive tools to help users manage their payments and understand the financial implications of different payment amounts. A visual interface allows users to drag a slider to see how much interest they would accrue based on their payment amount, encouraging more informed financial decisions. This interactive visualization is a clever application of user interface design and real-time calculation, making complex financial concepts more accessible and transparent. It aims to foster healthier financial habits by demystifying interest calculations and empowering users to proactively manage their debt.
Impact on the Fintech Landscape
The Apple Card’s emergence has had a palpable effect on the broader fintech landscape, influencing consumer expectations and driving innovation among competitors.
Pushing the Boundaries of Digital Payments
Apple, with its vast user base and ecosystem, has significantly accelerated the adoption and expectation of advanced digital payment features. The Apple Card showcases what’s possible when a technology company fully commits to reimagining financial services with a focus on user experience, security, and integration. Its success has undoubtedly spurred other banks and financial institutions to invest more heavily in their digital platforms, mobile app experiences, and advanced security features, recognizing that consumers now expect more than just a functional credit card. It has raised the bar for what constitutes a “modern” credit card experience.
Consumer Expectations and Future Innovations
The Apple Card has helped shape consumer expectations around transparency, real-time insights, and ease of use in financial products. Users now anticipate instant access to their spending data, clear reward structures, and robust security measures as standard, rather than luxury, features. This shift in consumer demand will likely continue to drive innovation across the fintech sector, encouraging the development of more intelligent, integrated, and secure financial tools. The Apple Card serves as a blueprint for how technology can transform traditionally stagnant industries, demonstrating that a focus on user-centric design and robust security protocols can create a highly competitive and compelling offering in the crowded financial services market. Its innovative approach to payments, privacy, and financial management positions it not just as a credit card, but as a significant milestone in the ongoing evolution of financial technology.