For professionals, entrepreneurs, and innovators immersed in the dynamic world of drone technology, AI, autonomous flight systems, and remote sensing, understanding federal tax brackets is not just a matter of compliance but a critical component of strategic financial planning. Whether you’re a software engineer developing AI for drone navigation, a startup founder specializing in mapping solutions, or a freelance aerial cinematographer, your earnings, investments, and business activities directly influence your taxable income and, consequently, your federal income tax bracket. This knowledge empowers you to make informed decisions about salary negotiations, equity vesting, intellectual property monetization, and future investment strategies within the innovation economy.

Understanding Your Taxable Income in the Innovation Economy
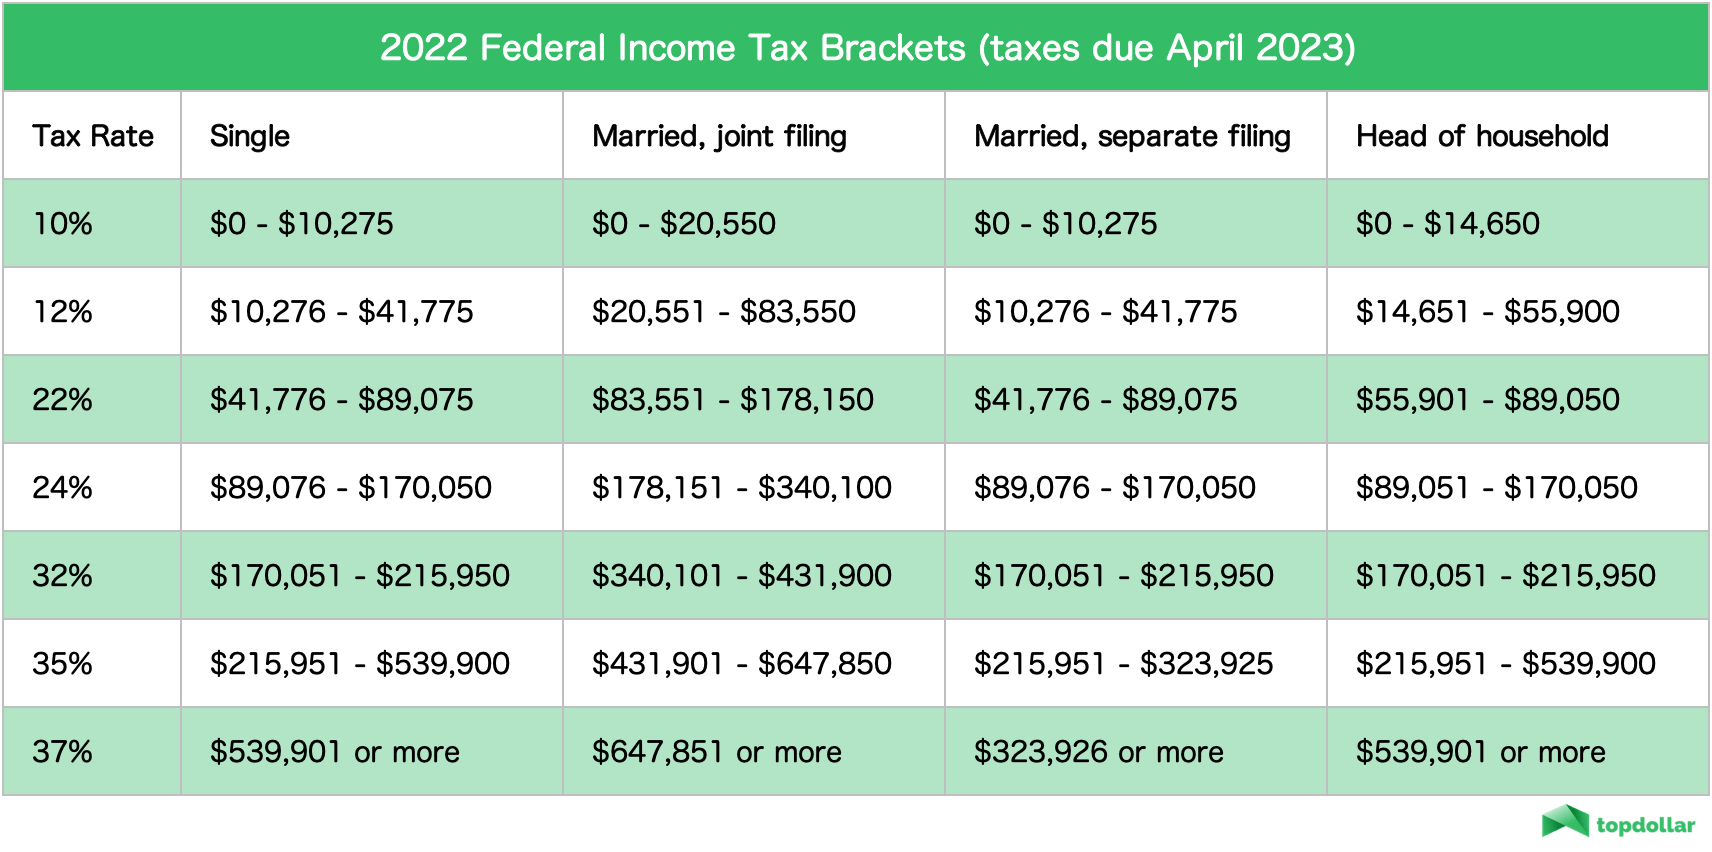
Your federal tax bracket is determined by your taxable income and your filing status. Taxable income isn’t simply your gross pay; it’s the amount left after subtracting certain deductions, adjustments, and exemptions from your gross income. For individuals deeply embedded in tech and innovation, income sources can be diverse and complex, requiring careful consideration.
Consider an AI specialist earning a substantial salary from a leading drone manufacturer, or a founder who recently secured venture capital for their autonomous flight startup. Their gross income might include wages, bonuses, stock options, and perhaps even early-stage startup dividends or consulting fees. Each of these income streams contributes to the total figure that, after adjustments, will place them into a specific bracket.
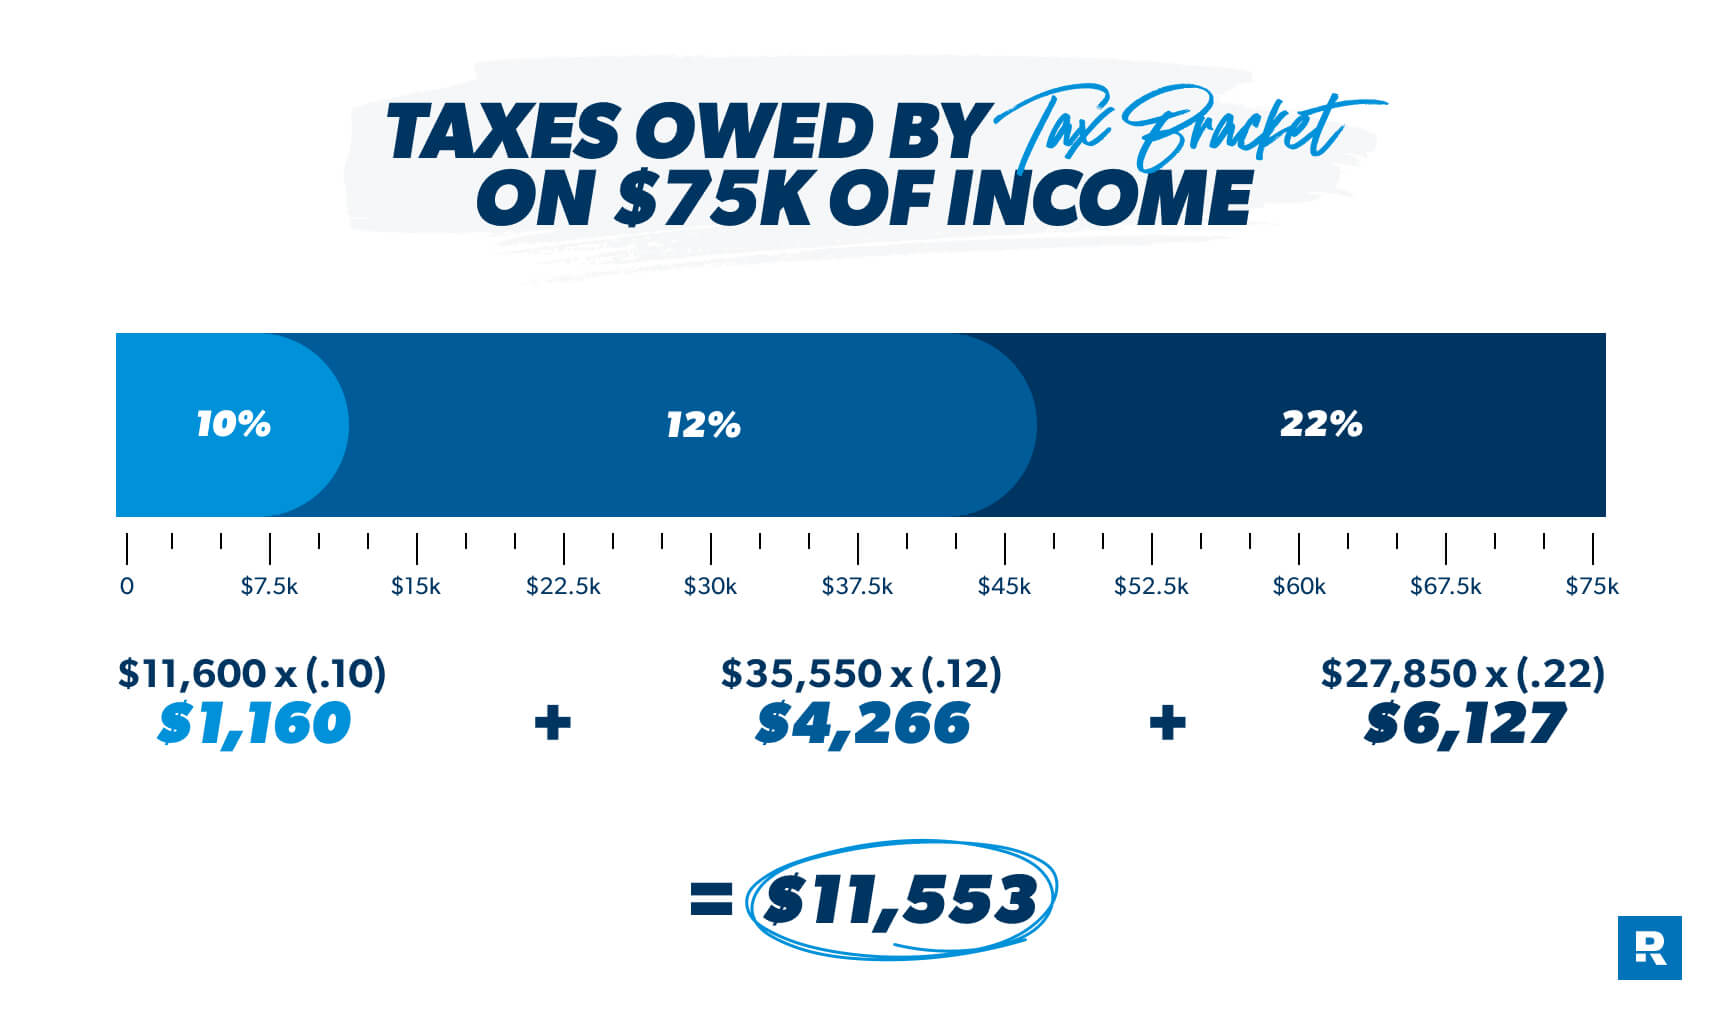
The U.S. federal income tax system operates on a progressive scale. This means different portions of your income are taxed at different rates. For instance, the lowest portion of your taxable income is taxed at the lowest rate, and successively higher portions are taxed at higher rates. This is why understanding your “marginal” tax rate versus your “effective” tax rate is crucial. Your marginal tax rate is the rate at which your last dollar of income is taxed, while your effective tax rate is the total amount of tax paid divided by your total taxable income. For a high-earning tech executive, while their highest income might fall into the 37% bracket, their overall effective tax rate will be significantly lower because earlier portions of their income were taxed at 10%, 12%, 22%, and so on.
Staying updated with the annual adjustments to federal tax brackets is also essential. The IRS periodically revises these thresholds to account for inflation, which can slightly shift where your income falls from one year to the next. For those involved in rapidly growing tech sectors, where income can fluctuate significantly with bonuses, stock vests, or successful project completions, consistent monitoring of these brackets ensures optimal financial forecasting.
Navigating Filing Status for Tech Professionals and Founders
Your filing status is a primary determinant of the tax bracket thresholds that apply to your income. There are five main filing statuses, each with its own set of income thresholds for the progressive tax rates:
- Single: This status applies if you are unmarried, divorced, or legally separated according according to state law on the last day of the tax year. It’s common for many early-career tech professionals or independent contractors in the drone space.
- Married Filing Jointly: If you are married and you and your spouse agree to file one return together, this status generally offers the widest tax brackets for a given income level, meaning a larger portion of combined income can remain in lower tax brackets. This is a common choice for married couples where one or both partners work in tech.
- Married Filing Separately: While less common due to potentially higher tax liability, this status allows married individuals to file separate returns. It might be chosen in specific scenarios, such as when one spouse has significant itemized deductions that would be diluted on a joint return, or in cases of financial or legal separation.
- Head of Household: This status typically applies to unmarried individuals who pay more than half the cost of keeping up a home for themselves and a qualifying person. A single parent working as a drone data analyst, supporting their child, would likely qualify.
- Qualifying Widow(er) with Dependent Child: This status allows taxpayers to use the Married Filing Jointly tax rates for up to two years after the death of a spouse, provided they meet certain conditions, including having a dependent child.
For startup founders, understanding personal filing status is often intertwined with their business’s legal structure. While the business might be an LLC or C-Corp, the founder’s personal income (salary, distributions, capital gains from equity) funnels back to their individual tax return, where their chosen filing status applies. Incorrectly identifying your filing status can lead to either overpaying taxes or facing penalties from the IRS, underscoring the importance of accurate self-assessment.
Deductions and Credits: Optimizing Your Tax Strategy in Tech
Understanding your tax bracket is only one side of the coin; strategically utilizing deductions and credits can significantly reduce your taxable income and, by extension, your tax liability. For those in tech and innovation, there are numerous opportunities to optimize their tax position.
Standard vs. Itemized Deductions: Most taxpayers opt for the standard deduction, a fixed amount that reduces taxable income. However, if your eligible itemized deductions exceed the standard deduction, itemizing can be more beneficial. For tech professionals, itemized deductions might include significant unreimbursed employee expenses (though many are no longer deductible after tax reform), substantial home mortgage interest, or large charitable contributions.
Business Expenses for Freelancers and Contractors: The gig economy thrives in tech, with many experts in AI development, remote sensing data analysis, or drone piloting operating as independent contractors. These individuals can deduct a wide array of legitimate business expenses from their gross income, including:
- Equipment Purchases: High-end drones, specialized cameras, powerful computing hardware for data processing, and software licenses.
- Home Office Deduction: If a portion of your home is used exclusively and regularly as your principal place of business.
- Professional Development: Costs for specialized certifications, workshops on new drone regulations, or subscriptions to industry journals.
- Travel Expenses: For client meetings, site surveys, or attending tech conferences relevant to your niche.
Credits for Innovation and Investment: Beyond deductions, tax credits directly reduce the amount of tax you owe, dollar for dollar. These are particularly valuable. While many credits are for specific circumstances (e.g., child tax credit), some can indirectly benefit individuals in the tech ecosystem:
- Research & Development (R&D) Tax Credit: While primarily a corporate credit, some self-employed individuals or small businesses performing qualified research activities (e.g., developing new drone components, AI algorithms) may be eligible. This can significantly reduce a startup’s or individual contractor’s tax burden.
- Education Credits: For those pursuing advanced degrees or specialized certifications to stay ahead in rapidly evolving tech fields.
- Clean Energy Credits: If your home office incorporates renewable energy solutions, these credits can apply.
Strategically timing the acquisition of new, high-cost tech equipment towards the end of a tax year can also be a savvy move, allowing for immediate depreciation deductions that lower current year taxable income. Consulting with a tax professional specializing in small businesses or high-net-worth individuals in tech is often invaluable for navigating these complex opportunities.
Planning for the Future: Capital Gains and Startup Exits
For tech founders and early employees, particularly in fast-growth sectors like drone AI or autonomous systems, understanding how capital gains factor into their tax picture is paramount. The sale of company stock, stock options, or other investments can result in capital gains or losses, which are taxed differently than ordinary income.
Short-Term vs. Long-Term Capital Gains:
- Short-Term Capital Gains: These result from selling an asset you’ve owned for one year or less. They are taxed at your ordinary income tax rate, meaning they could push you into a higher federal tax bracket. This is a crucial consideration for early startup employees who might see rapid appreciation in stock value.
- Long-Term Capital Gains: These result from selling an asset you’ve owned for more than one year. They are generally taxed at more favorable rates (0%, 15%, or 20% for most taxpayers), significantly lower than ordinary income tax rates. This favorable treatment encourages long-term investment, which is often the case for founders or employees holding onto equity for extended periods until an acquisition or IPO.
For a startup founder whose company focusing on advanced drone mapping solutions is acquired, a significant portion of their wealth might come from the sale of their equity. Understanding the distinction between short-term and long-term capital gains can lead to substantial tax savings. If possible, structuring an exit or the timing of an investment sale to qualify for long-term capital gains rates is a critical financial strategy.
Furthermore, sophisticated planning involving qualified small business stock (QSBS) exclusions can offer even greater tax benefits for founders and early investors in certain small businesses, potentially excluding a substantial portion of capital gains from federal tax. This provision is particularly relevant for innovative tech startups in their early growth phases.
In summary, for anyone navigating the financial landscape of tech and innovation, from developing the next generation of FPV racing drones to pioneering AI for autonomous delivery, knowing your federal tax bracket is merely the starting point. It’s the intricate dance between understanding income sources, leveraging deductions and credits, and strategic long-term planning for capital gains that truly empowers you to optimize your financial standing within this exciting and evolving industry.