
The Core Components of Adjusted Gross Income (AGI)
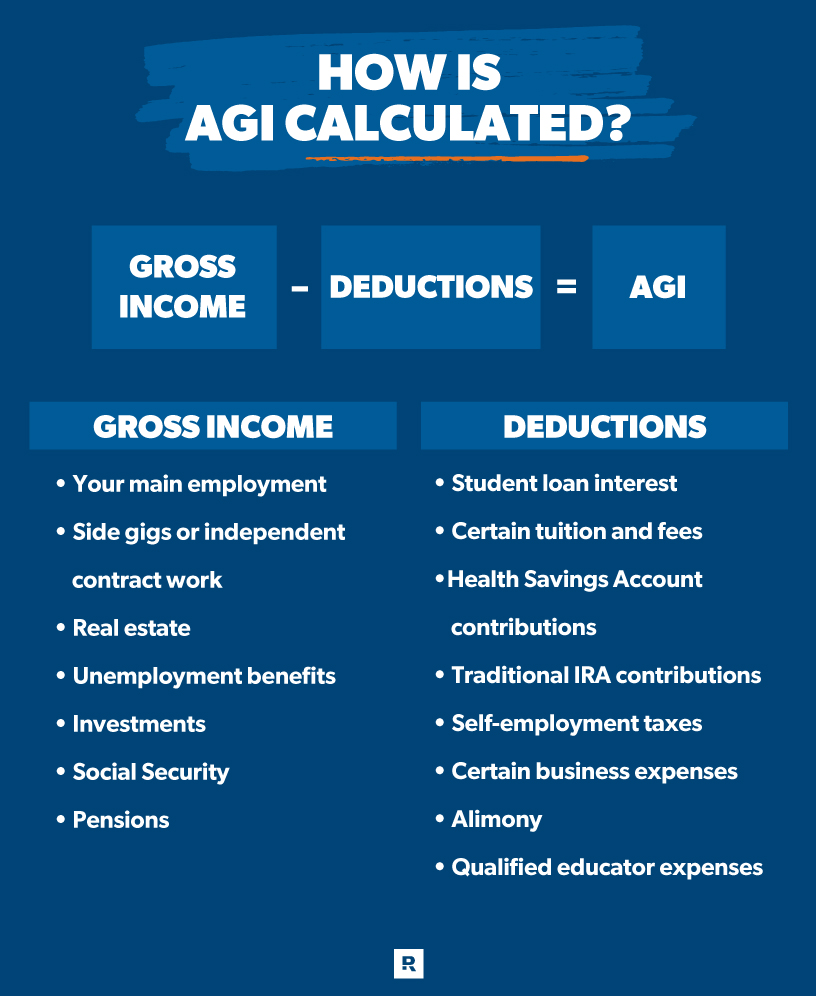
Understanding Modified Adjusted Gross Income (MAGI) begins with a firm grasp of its foundational element: Adjusted Gross Income (AGI). AGI serves as a critical midpoint in tax calculations, representing an individual’s gross income minus specific “above-the-line” deductions. For professionals and entrepreneurs in the dynamic tech and innovation sector, a precise understanding of AGI is paramount, influencing everything from tax liabilities to eligibility for various financial programs.
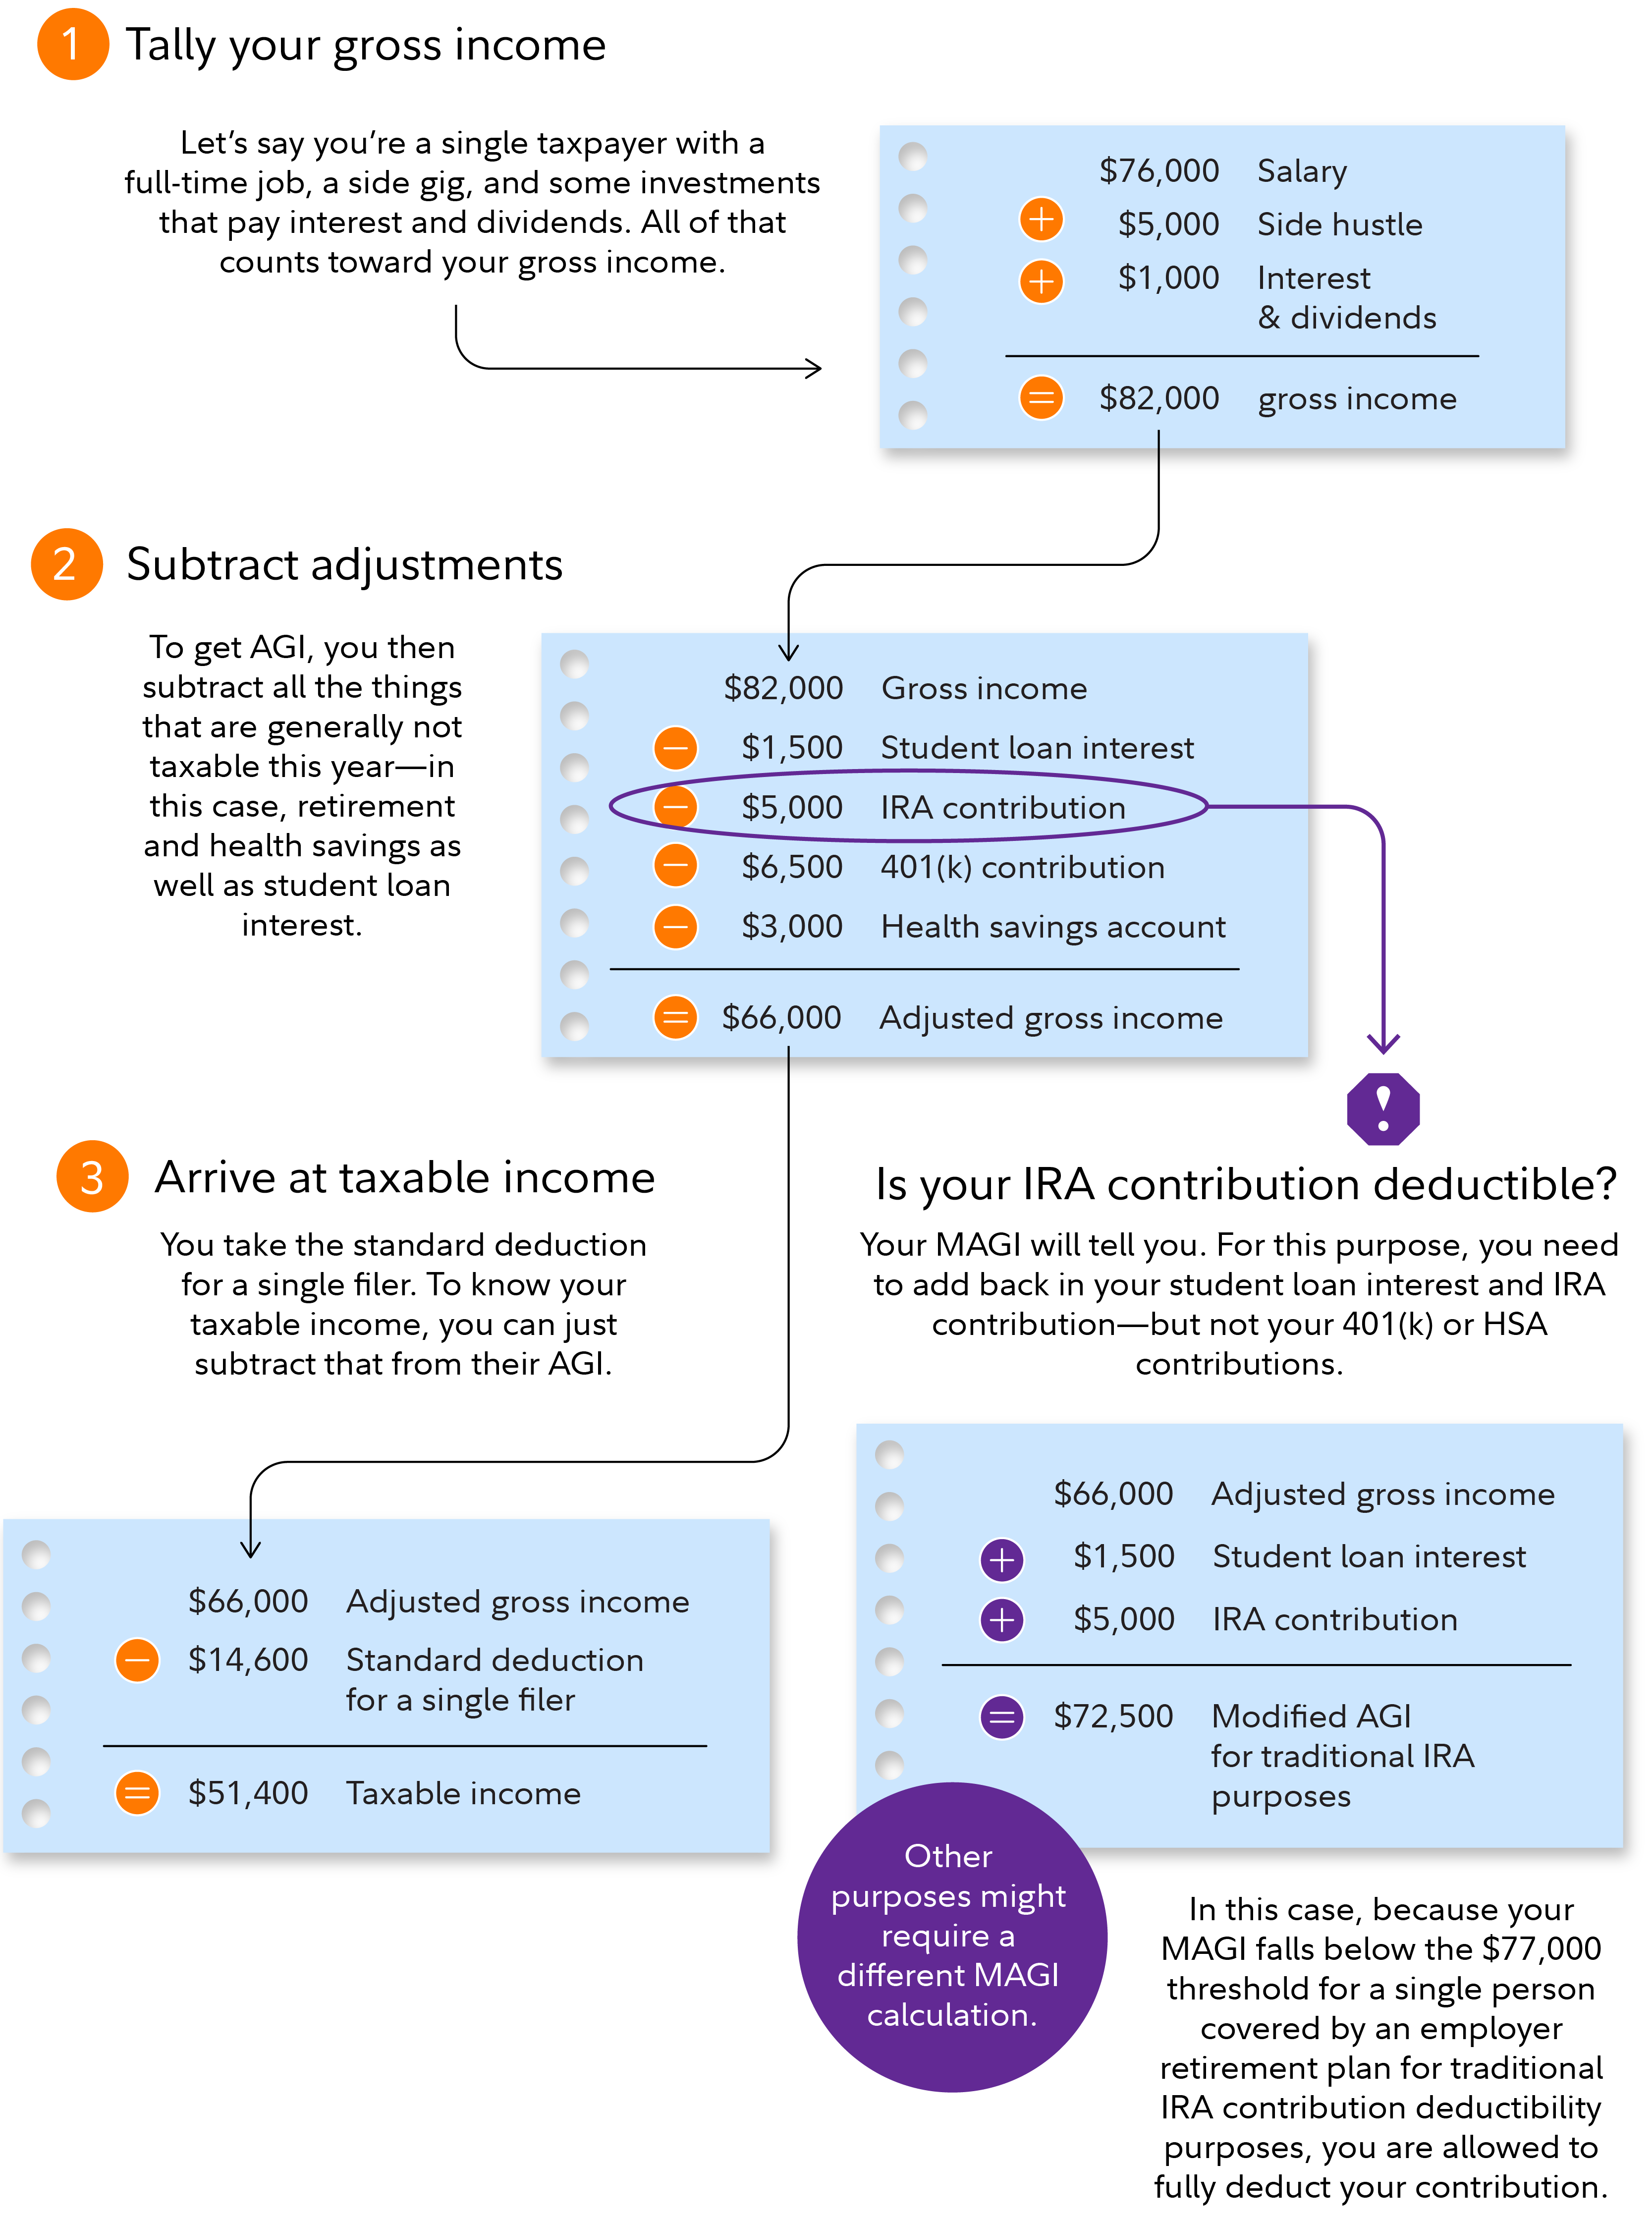
Gross income, the starting point, encompasses all taxable earnings, including salaries, wages, bonuses, capital gains from selling stock in tech companies, business profits from a startup, and income from intellectual property licensing. From this total, certain specific deductions are subtracted to arrive at AGI. These “above-the-line” deductions are available regardless of whether an individual itemizes or takes the standard deduction.
Standard Deductions and Above-the-Line Adjustments
Key above-the-line adjustments particularly relevant to those in the tech and innovation space might include:
- Educator Expenses: While often associated with teachers, this can sometimes apply to individuals who teach tech-related courses or workshops as part of their professional development.
- Health Savings Account (HSA) Deductions: Many tech companies offer high-deductible health plans, making HSAs a popular, tax-advantaged savings vehicle. Contributions to an HSA are deductible.
- Self-Employment Tax Deduction: For independent contractors, freelancers, or startup founders operating as sole proprietors, half of their self-employment taxes (Social Security and Medicare) are deductible. This is a common scenario in the flexible tech gig economy.
- IRA Contributions: Contributions to a traditional IRA can be deductible, depending on income levels and participation in employer-sponsored retirement plans. Many tech professionals, particularly those working for startups without robust 401(k) plans, leverage IRAs for retirement savings.
- Student Loan Interest Deduction: Given the high cost of education often associated with acquiring specialized tech skills, this deduction can be significant for many.
- Alimony Paid: For divorce decrees executed before 2019, alimony payments are deductible.
- Capital Loss Deduction: Losses from investments, including those in high-risk tech ventures, can be deducted against other income up to $3,000 per year, with carryovers for excess losses.
The resulting AGI is a crucial figure, acting as a baseline for numerous income-dependent calculations across the tax code. It’s often the first step in determining eligibility for various tax credits, deductions, and financial assistance programs. For innovators, understanding how their diverse income streams and eligible deductions shape their AGI is the groundwork for effective financial planning.
Relevance to Tech Professionals and Innovators
For those navigating the fast-paced world of tech and innovation, AGI is not just a number on a tax form; it’s a strategic indicator. High-earning tech executives may find their AGI impacts the deductibility of certain expenses or their ability to contribute to specific retirement accounts. Startup founders, often with variable income streams, need to monitor their AGI to optimize self-employment deductions and access potential small business tax credits. The ability to effectively manage and reduce AGI through legitimate deductions can free up capital for reinvestment into a venture or personal development, further fueling innovation.
Unpacking the “Modified” in MAGI
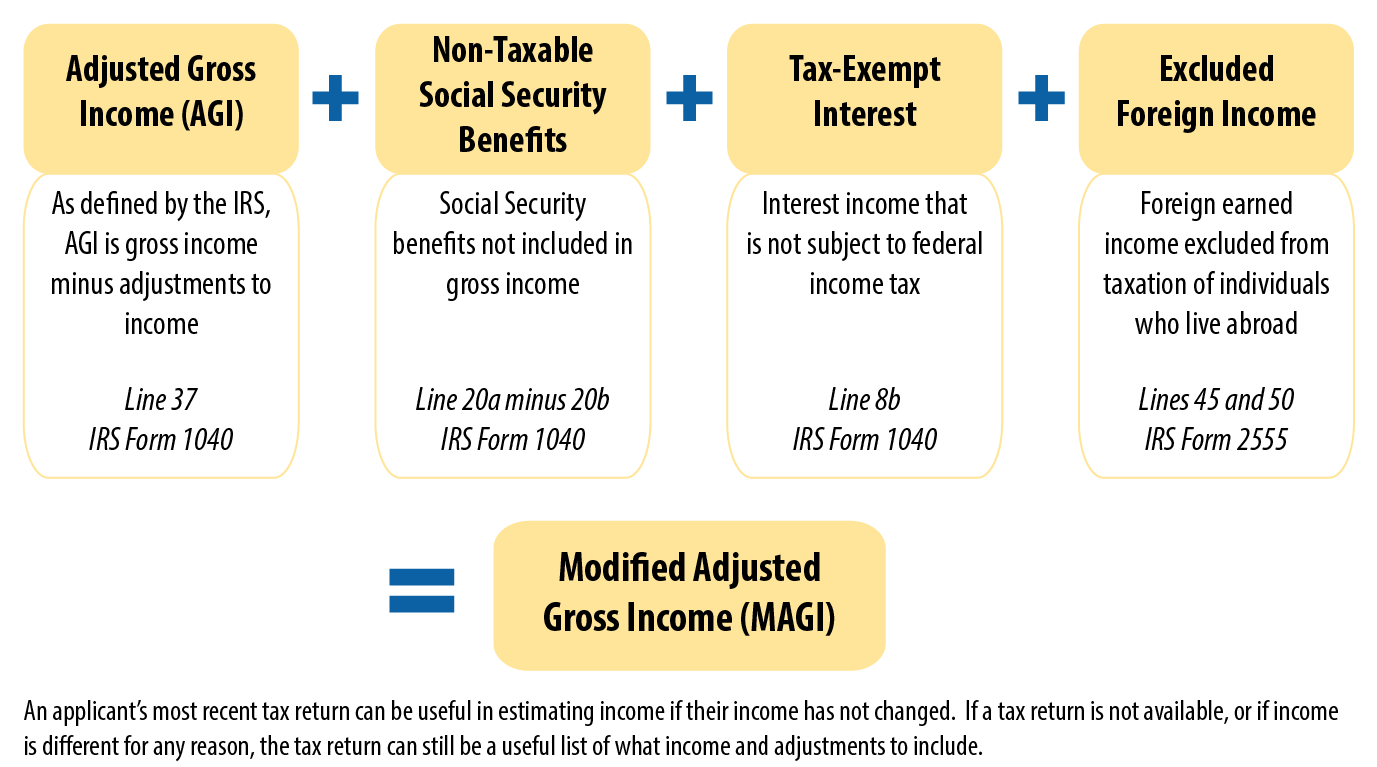
While AGI is a fundamental concept, Modified Adjusted Gross Income (MAGI) introduces an additional layer of complexity, specifically by “adding back” certain deductions or exclusions that were initially removed from gross income to calculate AGI. The “modified” aspect means that AGI is adjusted further by adding back specific types of income or deductions that are typically tax-exempt or previously deducted. This adjustment is not uniform; different programs and tax provisions have their own unique definitions of MAGI, meaning the “modified” list can vary depending on the context. However, several common add-backs are frequently seen.
Common Add-Backs: Beyond AGI
The general purpose of MAGI is to present a more comprehensive picture of an individual’s total income, particularly for determining eligibility for various income-dependent benefits and limitations. Common items often added back to AGI to arrive at MAGI include:
- Tax-Exempt Interest: Interest income from municipal bonds, which is typically excluded from gross income, is often added back for MAGI calculations. While less common for direct tech investments, some diversified portfolios held by tech professionals may include these.
- Excluded Foreign Earned Income: For tech professionals working abroad or digital nomads earning income in other countries, certain foreign earned income might be excluded from U.S. taxable income. This excluded amount is usually added back to AGI for MAGI purposes.
- Tax-Exempt Portions of Social Security Benefits: If a portion of Social Security benefits is not taxable for regular AGI, it’s often added back for MAGI calculations.
- Deduction for One-Half of Self-Employment Taxes: This is a crucial one for many self-employed tech consultants, contractors, or startup founders. While half of self-employment taxes are deductible in calculating AGI, this deduction is typically added back for MAGI.
- IRA Contributions (Deductible): While contributions to a traditional IRA might be deductible for AGI purposes, they are frequently added back when calculating MAGI for specific programs.
- Student Loan Interest Deduction: Similar to IRA contributions, the student loan interest deduction, though reducing AGI, is often added back for MAGI.
- Tuition and Fees Deduction: Any deduction taken for tuition and fees for higher education is commonly added back for MAGI.
- Passive Activity Losses: Certain losses from passive activities, which might be limited in their deductibility for AGI, can be added back for MAGI calculations.
It’s critical to note that the exact list of add-backs depends entirely on the specific purpose for which MAGI is being calculated. The IRS defines several versions of MAGI, each tailored to different tax provisions.
Specific Implications for Tech Founders and Investors
For tech founders navigating startup financing, or investors evaluating opportunities, understanding these add-backs is vital. For instance, a founder taking a small salary and relying on foreign earnings, or an investor with significant tax-exempt interest, might find their MAGI is higher than their AGI. This discrepancy can directly impact their eligibility for:
- Roth IRA Contributions: MAGI is the primary determinant for phase-out limits for contributing directly to a Roth IRA.
- Premium Tax Credits (ACA Subsidies): Self-employed tech workers or those employed by early-stage startups often rely on the Affordable Care Act (ACA) marketplace for health insurance. MAGI dictates eligibility and the amount of premium tax credits.
- Deductibility of Medical Expenses: For those with substantial medical costs, MAGI impacts the threshold for deducting these expenses.
- Net Investment Income Tax (NIIT): High-income individuals with significant investment income (e.g., from tech stock sales or venture capital returns) use MAGI to determine their liability for NIIT.
- Student Loan Interest Deduction Phase-Outs: As mentioned, the deductibility of student loan interest is phased out at higher MAGI levels.
In essence, MAGI provides a more expansive view of an individual’s financial capacity, designed to prevent those with substantial but otherwise tax-advantaged income from disproportionately benefiting from income-sensitive programs. For the tech community, where income streams can be complex and diverse, careful calculation of MAGI is not merely a compliance task but a critical element of strategic financial planning.
Why MAGI Matters in the Tech & Innovation Ecosystem
For individuals deeply entrenched in the tech and innovation ecosystem – from visionary startup founders and brilliant engineers to savvy angel investors and serial entrepreneurs – MAGI is far more than an obscure tax acronym. It’s a pivotal financial metric that can unlock or restrict access to crucial benefits, shape investment strategies, and dictate the affordability of essential services. Understanding how MAGI functions within various financial contexts is essential for optimizing personal and professional financial health.
Navigating Retirement Planning and Roth IRA Eligibility
Retirement planning is a cornerstone of financial security, even in high-growth, high-risk tech careers. Roth IRAs, with their tax-free withdrawals in retirement, are immensely popular, particularly among younger professionals expecting higher tax brackets in the future. However, direct contributions to a Roth IRA are subject to MAGI-based income phase-out limits.
- Contribution Limits: Each year, the IRS sets MAGI thresholds above which an individual’s ability to contribute directly to a Roth IRA is reduced or eliminated. For high-earning tech professionals, exceeding these limits is common.
- Backdoor Roth Strategies: When MAGI is too high for direct Roth contributions, a “backdoor Roth” strategy becomes relevant. This involves contributing to a non-deductible traditional IRA and then immediately converting it to a Roth IRA. Understanding MAGI helps determine when this strategy is necessary and ensures compliance with related tax rules, such as the pro-rata rule for pre-tax IRA balances.
Healthcare Subsidies and the Affordable Care Act (ACA)
For many in the tech sphere, particularly startup founders, freelancers, or those working for smaller companies without comprehensive benefits, the health insurance marketplace established under the Affordable Care Act (ACA) is a vital resource. Eligibility for Premium Tax Credits (PTC) and Cost-Sharing Reductions (CSR) – which make health insurance more affordable – is directly tied to MAGI.
- Premium Tax Credits: These credits help offset the cost of monthly health insurance premiums. The amount of the credit is determined on a sliding scale based on MAGI relative to the federal poverty level. A higher MAGI can significantly reduce or eliminate these crucial subsidies.
- Cost-Sharing Reductions: CSRs lower out-of-pocket costs like deductibles, copayments, and maximum out-of-pocket limits for those with MAGI below certain thresholds.
- Impact on Startup Founders: Founders often defer high salaries, but even modest income combined with other add-backs can push their MAGI above subsidy thresholds, making healthcare a substantial personal expense. Strategic income planning, factoring in MAGI, can ensure access to affordable health coverage.
Educational Pursuits and Student Loan Deductions
The tech landscape demands continuous learning and skill acquisition. Whether pursuing advanced degrees, coding bootcamps, or specialized certifications, education costs are a recurring factor. MAGI plays a role in the deductibility of student loan interest.
- Student Loan Interest Deduction Phase-Outs: The ability to deduct student loan interest for AGI purposes is phased out at higher MAGI levels. This means that while a tech professional might have significant student loan debt, their MAGI could prevent them from realizing the full tax benefit of the interest paid. This also extends to other education credits like the American Opportunity Tax Credit or Lifetime Learning Credit, which also have MAGI-based income limitations.
Investment Opportunities and Tax Credits
For angel investors, venture capitalists, or even individual tech employees holding substantial company stock, MAGI can influence the tax treatment of investment income and eligibility for certain credits.
- Net Investment Income Tax (NIIT): Individuals with MAGI above certain thresholds are subject to the Net Investment Income Tax (NIIT) of 3.8% on certain investment income, including capital gains, dividends, and passive business income. For successful tech investors or those with lucrative stock options, this can be a significant additional tax.
- Small Business & R&D Tax Credits: While often applied at the corporate level, individual investors or founders of pass-through entities (like S-corps or partnerships) might find their personal tax situation, influenced by MAGI, affects the ultimate benefit they derive from certain state or federal R&D tax credits designed to incentivize innovation.
Strategic Planning Around MAGI for Innovators
Given the pervasive influence of MAGI across various financial facets, strategic planning around this figure is not merely advantageous but essential for individuals in the tech and innovation sector. Proactive management of income and deductions can significantly impact eligibility for key benefits and overall financial well-being.
Proactive Income Management
Understanding how different income sources and deductions contribute to MAGI allows for proactive management throughout the year. For instance:
- Timing of Income/Deductions: Tech founders expecting a significant liquidity event (e.g., IPO, acquisition) can strategize the timing of income recognition or charitable contributions to manage their MAGI in specific years.
- Retirement Contributions: Maximizing deductible contributions to 401(k)s or traditional IRAs can lower AGI, which in turn impacts MAGI. For those above Roth IRA limits, consistent use of the backdoor Roth strategy becomes a routine part of financial planning.
- Business Expenses: Self-employed tech consultants should meticulously track and deduct all eligible business expenses to reduce their net self-employment income, thereby affecting both AGI and MAGI.
Consulting with Financial Experts
The intricacies of MAGI calculations, especially with varying definitions for different tax provisions, underscore the importance of professional guidance.
- Tax Professionals: A knowledgeable tax advisor specializing in high-net-worth individuals or entrepreneurs can provide tailored advice on optimizing MAGI, navigating complex investment income, and ensuring compliance.
- Financial Planners: A comprehensive financial planner can integrate MAGI considerations into broader financial goals, including retirement planning, investment strategy, and healthcare funding. They can help tech innovators make informed decisions that align with their short-term needs and long-term aspirations, ensuring that MAGI is an understood asset rather than a perplexing liability in their financial journey.
In the fast-evolving world of tech, where innovation drives progress, intelligent financial management, starting with a clear understanding of MAGI, empowers individuals to build and sustain their wealth effectively.