
The Foundation of Corporate Taxation in the Tech Sector
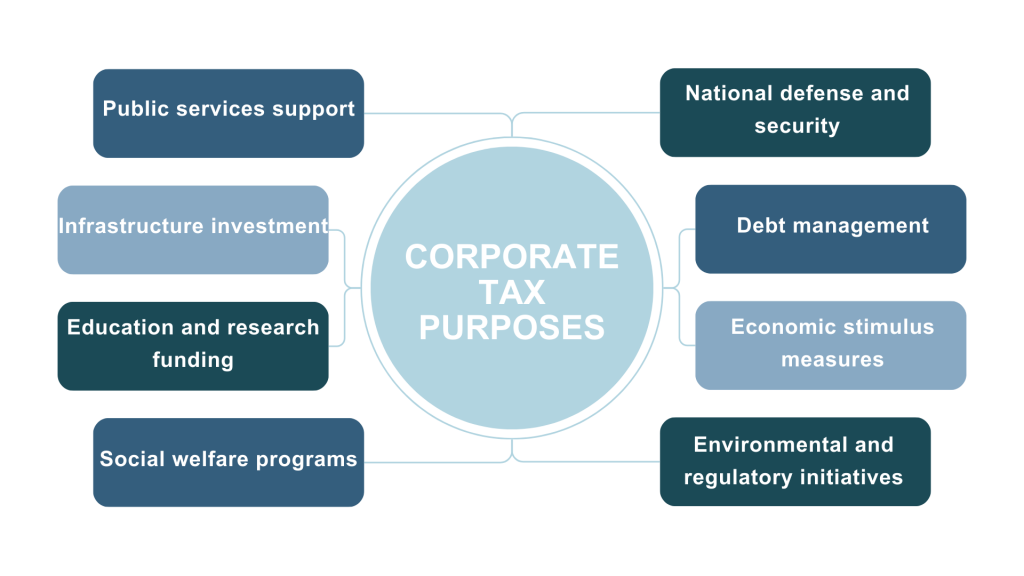
Corporate tax represents a levy imposed by governments on the profits of businesses. In essence, it’s a direct tax on a company’s net earnings, calculated after deducting operating expenses, cost of goods sold, and depreciation from its revenue. For companies entrenched in the “Tech & Innovation” landscape – those developing cutting-edge AI, advancing autonomous flight systems, pioneering new mapping solutions, or revolutionizing remote sensing technologies – understanding this fundamental concept is crucial. Unlike individual income tax, which applies to personal earnings, corporate tax targets the profitability of the enterprise itself. The revenue generated from corporate taxes often funds public services and infrastructure, which in turn can support the very ecosystem that tech companies rely upon, such as educational institutions producing skilled talent, regulatory bodies ensuring fair competition, and digital infrastructure facilitating global connectivity.
The complexity of corporate tax for tech and innovation firms is often magnified by several factors inherent to their operations. Many tech companies are asset-light but IP-heavy, with significant investments in research and development (R&D), software, patents, and data – all of which have unique tax treatments. Their rapid growth models, often involving venture capital and subsequent public offerings, introduce intricate financial structures that influence tax obligations. Furthermore, the inherently global nature of digital products and services means that many tech innovators operate across multiple jurisdictions, navigating a patchwork of international tax laws and treaties. This global footprint requires sophisticated tax planning to ensure compliance and optimize after-tax profits, a critical consideration for reinvestment in future innovation.
How Corporate Tax Impacts Innovation and Growth
The design and rates of corporate tax significantly influence the strategic decisions of tech and innovation companies, directly affecting their propensity for R&D, investment, and growth. High corporate tax rates, without corresponding incentives, can potentially disincentivize investment in new technologies, as a larger portion of potential profits is diverted to tax liabilities. Conversely, a favorable tax environment, characterized by lower rates or targeted incentives, can stimulate innovation by allowing companies to retain more capital for reinvestment.
R&D Tax Credits and Incentives
One of the most powerful mechanisms linking corporate tax to innovation is the R&D tax credit. Governments worldwide offer these credits to encourage companies to invest in research and experimental development activities. For a company focused on developing advanced AI algorithms for drone navigation or refining sensor technology for autonomous vehicles, R&D tax credits can significantly reduce their effective tax rate. These credits effectively lower the cost of innovation, making it more attractive for companies to allocate resources towards pioneering new solutions, hiring specialized talent, and engaging in risky but potentially transformative research. The application of these credits often involves complex documentation and justification of eligible R&D activities, requiring robust internal processes for tracking and reporting experimental efforts.
Startup vs. Established Tech Giants
The impact of corporate tax also varies significantly between nascent tech startups and established industry giants. Startups, often pre-profitability, may not immediately feel the burden of corporate income tax. Their primary tax considerations initially revolve around payroll taxes, sales taxes, and ensuring compliance for future growth. However, the potential for future corporate tax liabilities, coupled with the availability of R&D credits, influences their long-term financial modeling and investor attractiveness. For established tech giants, such as those dominating the cloud computing space or developing widely adopted autonomous systems, corporate tax is a perpetual and substantial consideration. These companies often have complex global structures, extensive intellectual property portfolios, and significant profitability, leading to substantial tax burdens and intense scrutiny from tax authorities worldwide. Their strategies frequently involve sophisticated tax planning, including the optimization of intellectual property location and intercompany transactions, to manage their global effective tax rates.
Global Corporate Tax Landscape for Tech Giants
The inherently borderless nature of digital products and services has placed tech and innovation companies at the forefront of global corporate tax reform discussions. When a company develops an AI-powered flight controller in one country, manufactures drones in another, and sells them globally, where should the profits be taxed? This question has led to significant international challenges and ongoing efforts to modernize tax rules.
Digital Services Taxes and BEPS Initiatives
The proliferation of digital services and the ability of tech companies to generate significant revenue in jurisdictions where they have little physical presence have prompted many countries to implement or propose Digital Services Taxes (DSTs). These taxes often target the revenue generated from services like online advertising, social media platforms, and data monetization, rather than net profits. While often controversial and subject to international trade disputes, DSTs reflect a growing global sentiment that digital giants should contribute more to the tax base of countries where their users or customers are located.
In parallel, initiatives like the OECD’s Base Erosion and Profit Shifting (BEPS) project aim to combat tax avoidance strategies used by multinational corporations. For tech companies, BEPS focuses on issues such as transfer pricing of intellectual property (IP), the attribution of profits to permanent establishments (even virtual ones), and hybrid mismatch arrangements. These reforms compel tech companies to re-evaluate their global operating models, ensuring that profits are taxed where economic substance and value creation occur. Compliance with BEPS principles means that companies developing new drone mapping software or advanced sensor arrays must carefully document the location of their R&D, the ownership of their IP, and the functions performed by their various subsidiaries to justify their profit allocations.
Intellectual Property (IP) and Tax Planning
Intellectual property is the lifeblood of innovation, and its tax treatment is paramount for tech companies. Patents, software copyrights, trademarks, and trade secrets represent immense value for firms in AI, autonomous flight, and remote sensing. The location of IP ownership within a multinational corporate structure can significantly influence global tax liabilities. Jurisdictions offering “patent box” regimes, for example, provide lower effective tax rates on income derived from qualifying intellectual property. This incentivizes tech companies to locate their IP development and ownership in these regions, fostering local innovation ecosystems. However, such strategies are under increasing scrutiny from international tax authorities, requiring companies to demonstrate a clear link between the IP’s development, management, and the economic activities conducted in the chosen jurisdiction. Strategic management of IP, from its creation through licensing and monetization, is a critical component of effective corporate tax planning for innovation-driven enterprises.
Tax Incentives and Challenges for Emerging Technologies
The intersection of corporate tax and emerging technologies presents both unique opportunities for incentivization and complex challenges for traditional tax frameworks. Governments frequently use the tax system to accelerate the adoption and development of groundbreaking innovations, while the novel characteristics of these technologies can strain existing tax definitions and regulations.
Stimulating Growth Through Targeted Deductions
Beyond general R&D tax credits, specific deductions and accelerated depreciation schedules can benefit companies investing heavily in physical assets central to emerging technologies. For instance, a firm building massive data centers to power its AI models for autonomous drone operations, or investing in advanced manufacturing facilities for next-generation flight hardware, might benefit from faster write-offs of these capital expenditures. This reduces their taxable income in the early years of an asset’s life, freeing up capital for further investment or operational expenses. Furthermore, some regions offer incentives for job creation in tech sectors or for companies locating in designated innovation hubs, indirectly impacting corporate tax burdens through payroll tax reductions or property tax abatements.
Valuation and Amortization of Intangible Assets
A significant challenge for tech and innovation companies lies in the valuation and amortization of intangible assets. Unlike a factory or piece of machinery, the value of a proprietary AI algorithm, a complex software suite for drone control, or a unique sensor calibration method is often difficult to quantify for tax purposes. Traditional accounting and tax rules are still catching up with the rapid pace of technological development, particularly concerning the useful life and depreciation schedules of software and other digital assets. The rapid obsolescence inherent in many tech products means that assets might lose their economic value much faster than prescribed amortization periods, creating a mismatch between actual economic life and tax treatment. Accurately assessing and deducting these costs is crucial for reflecting the true profitability of tech companies and avoiding overtaxation.

Cross-Border Collaboration and Talent Retention
The global nature of innovation means that tech companies frequently engage in cross-border collaborations, sharing resources, data, and intellectual property development. Corporate tax rules must facilitate, rather than hinder, these collaborative efforts. Considerations around withholding taxes on royalties for shared IP, or the tax treatment of shared R&D costs across international entities, become paramount. Moreover, corporate tax policies indirectly influence a company’s ability to attract and retain top talent. Competitive compensation packages, including stock options and other equity-based incentives, often have significant tax implications for both the company and the employees. A corporate tax environment that supports a highly skilled workforce, through advantageous personal income tax policies or favorable treatment of employee stock plans, can be a vital component of a nation’s ability to foster a thriving tech and innovation sector.