
Understanding the intricacies of business structures is paramount for entrepreneurs navigating the dynamic landscape of tech and innovation. For founders, particularly those pioneering advancements in areas like autonomous flight, advanced mapping, or remote sensing, the choice of a legal entity can significantly impact their operational flexibility, tax obligations, and potential for growth. Among the various structures available, the S Corporation (S Corp) stands out as a unique and often considered option. Far from being a mere acronym, an S Corporation represents a specific tax designation with profound implications for how a company, its profits, and its shareholders are treated by the IRS.
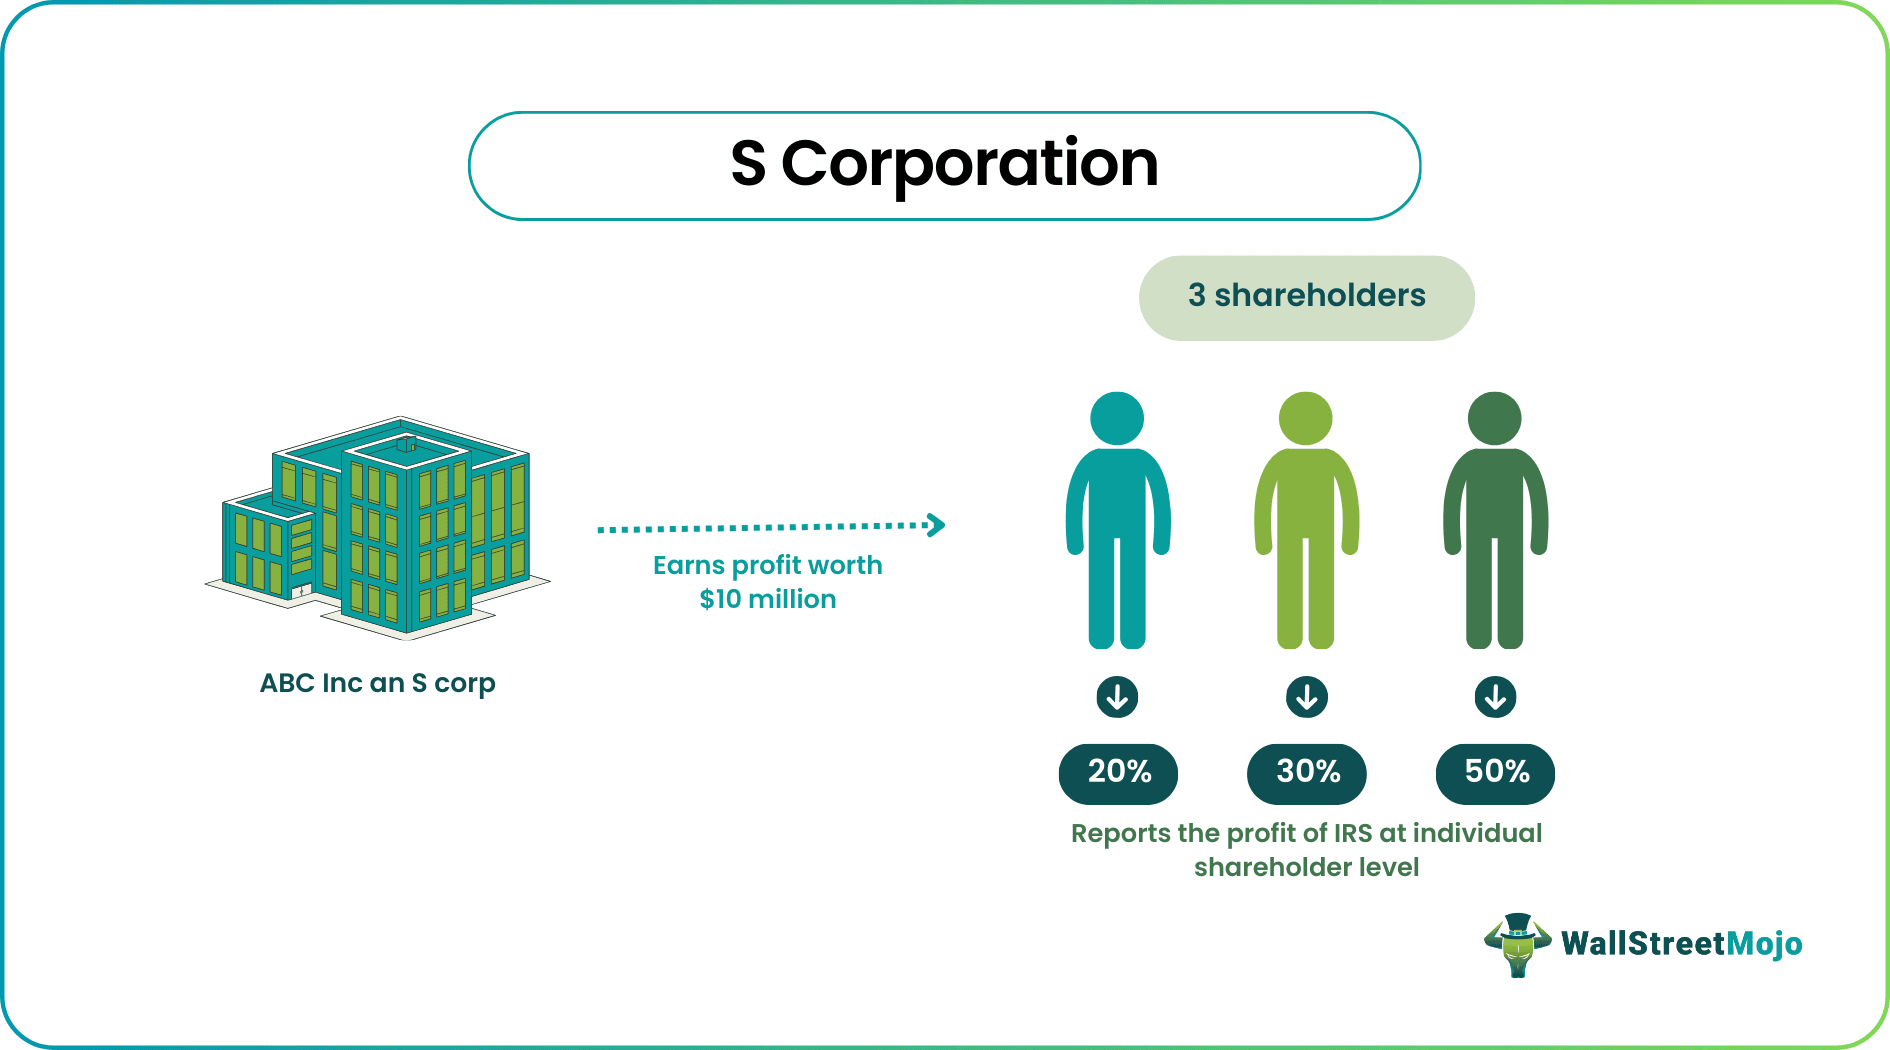
At its core, an S Corporation is not a separate legal entity like a C Corporation or an LLC. Instead, it’s a tax election made available to certain corporations and LLCs by the Internal Revenue Service (IRS). This election, governed by Subchapter S of Chapter 1 of the Internal Revenue Code, allows a business to avoid the double taxation inherent in traditional C Corporations. By choosing S Corp status, a company can pass its income, losses, deductions, and credits directly to its shareholders without being subject to corporate tax rates first. For innovative startups focused on rapid development and scaling, this pass-through taxation can offer significant strategic advantages.
Unpacking the S Corporation Structure for Tech Innovators
The decision to elect S Corporation status is a strategic one, often made after careful consideration of a company’s financial projections, growth trajectory, and ownership structure. For tech innovators, where initial capital expenditure can be high and profitability may not be immediate, understanding the nuances of an S Corp is critical.
The Basic Definition and Eligibility
An S Corporation is, in essence, a regular corporation (or an LLC that elects to be taxed as a corporation) that has made a specific election with the IRS to be taxed under Subchapter S. This means the entity itself is not subject to federal income tax; instead, the profits and losses are “passed through” to the owners’ personal income tax returns. Shareholders then pay taxes on their share of the profits at their individual income tax rates.
However, not all companies qualify for S Corp status. The IRS imposes specific eligibility requirements designed to keep the structure largely for smaller, domestically-focused businesses. Key criteria include:
- Domestic Corporation: The company must be a domestic corporation.
- Eligible Shareholders: It can have no more than 100 shareholders. All shareholders must be U.S. citizens or resident aliens, and cannot be partnerships, corporations, or certain trusts. This limitation is particularly relevant for tech startups seeking venture capital or institutional investment, as many VCs are structured as partnerships or corporations.
- One Class of Stock: The corporation can only have one class of stock. While it can have voting and non-voting differences, all shares must have identical rights to distribution and liquidation proceeds. This can be a significant constraint for startups that wish to offer different tiers of stock to founders, early employees, or various funding rounds.
- Specific Business Types: Certain financial institutions, insurance companies, and domestic international sales corporations are ineligible.
Key Characteristics and Taxation Mechanics
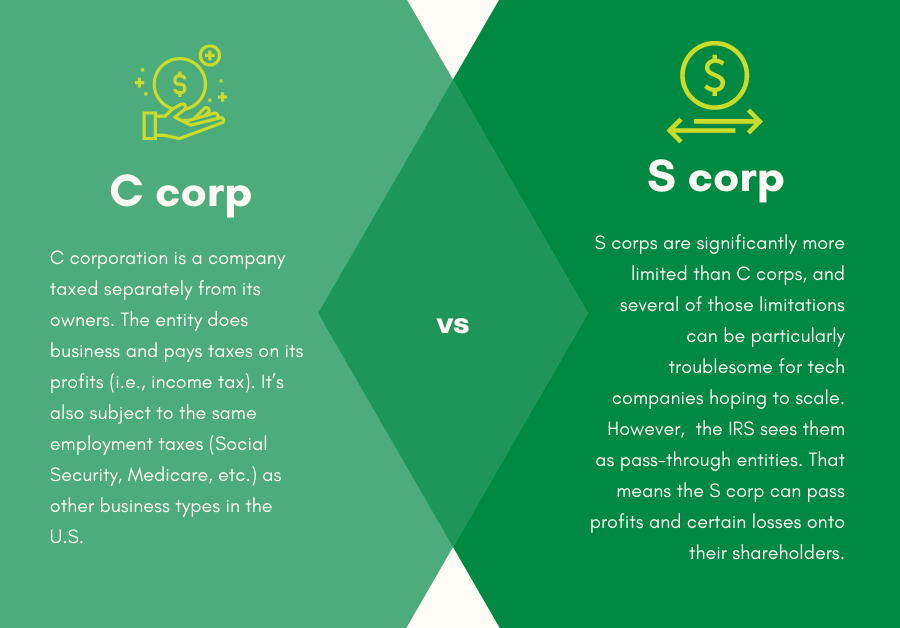
The defining characteristic of an S Corporation is its pass-through taxation. This mechanism directly contrasts with a C Corporation, which is taxed on its profits at the corporate level, and then shareholders are taxed again on dividends received (double taxation). In an S Corp, the profit or loss is allocated to shareholders based on their ownership percentage, and reported on their individual tax returns (Form 1040) via a Schedule K-1 received from the corporation.
An important element of S Corp taxation for founders is the requirement to pay themselves a “reasonable salary.” As an owner-employee, a portion of the distribution they receive from the S Corp must be designated as wages, subject to payroll taxes (Social Security and Medicare). The remaining profits can then be taken as distributions, which are not subject to these self-employment taxes. This distinction is often a primary driver for tech entrepreneurs to elect S Corp status, as it can lead to substantial savings on self-employment taxes compared to operating as a sole proprietorship or partnership.
Advantages for Tech Startups and Small Businesses
For innovative ventures, particularly those in nascent stages or with a lean operational model, the S Corporation offers compelling benefits that align with common startup needs.
Tax Savings on Self-Employment Tax
Perhaps the most significant financial draw for many tech founders and small business owners considering an S Corp is the potential for self-employment tax savings. In a sole proprietorship or partnership, all business profits are subject to self-employment taxes (currently 15.3% for Social Security and Medicare up to a certain income threshold, and then 2.9% for Medicare beyond it). With an S Corp, only the “reasonable salary” paid to an owner-employee is subject to these taxes. Any additional profits distributed to the owner are treated as non-wage income and are not subject to self-employment taxes, only income tax. For a profitable drone mapping service or an AI software developer, this can result in thousands of dollars in annual savings that can be reinvested into research and development or team expansion.

Credibility and Attracting Talent
While an S Corp is primarily a tax election, operating as a corporation (even one electing S status) can lend an air of professionalism and credibility that a sole proprietorship or general partnership might lack. This can be beneficial when dealing with clients, partners, or even attempting to secure initial funding. Furthermore, S Corps, being corporations, can issue stock, which is crucial for attracting top talent in the competitive tech space. Founders can offer equity stakes, stock options, or restricted stock units to key employees, aligning their interests with the company’s long-term success. This is a common practice in innovative tech companies, providing a powerful incentive for engineers, developers, and specialists in flight technology or sensor development.
Pass-Through Income and Loss
The pass-through nature of the S Corp is not only beneficial for profits but also for losses. In the early stages of a tech startup, it’s common to incur significant losses due to R&D, product development, and market entry costs. These losses can be passed through to the shareholders’ personal tax returns, where they can be used to offset other personal income, potentially reducing individual tax liabilities. This can be a crucial lifeline for founders bootstrapping a new drone manufacturing process or developing groundbreaking AI navigation systems.
Potential Drawbacks and Complexities in Innovation
While attractive, the S Corp structure is not without its limitations and complexities, especially for rapidly evolving tech businesses.
Eligibility Requirements and Restrictions
The strict eligibility criteria can be a major hurdle for tech companies with ambitious growth plans. The 100-shareholder limit can become problematic if a company seeks multiple rounds of venture capital funding, as institutional investors are often entities themselves (partnerships or corporations) and would invalidate S Corp status. Similarly, the one-class-of-stock rule can hinder the creation of sophisticated equity structures often used to reward different investor classes or employee groups with varying rights and preferences. Founders looking to scale aggressively or attract diverse investment might find these restrictions too limiting, eventually necessitating a conversion to a C Corporation.
Increased Administrative Burden
Operating as an S Corporation generally entails a higher administrative burden compared to a sole proprietorship or an LLC taxed as a partnership. Corporations are required to adhere to more stringent corporate formalities, such as maintaining corporate minutes, holding regular shareholder and director meetings, and meticulous record-keeping. Additionally, the process of payroll for owner-employees, issuing W-2s, and filing separate corporate tax returns (Form 1120-S) adds layers of complexity. For a small team focused on developing cutting-edge drone technology, these administrative overheads can divert valuable time and resources.
Navigating Equity and Growth
The S Corp structure, with its single class of stock and shareholder limitations, can complicate the equity management for high-growth tech firms. If a company plans to go public or attract large institutional investors, converting from an S Corp to a C Corp is often a necessary step. This conversion process, while manageable, involves legal and tax considerations that need careful planning. For drone companies eyeing global markets or significant venture funding, the S Corp may serve well in initial phases but could become a bottleneck later.
Deciding If an S Corp is Right for Your Drone Tech Venture
The decision to elect S Corporation status is a nuanced one that should align with a tech company’s specific stage of development, financial outlook, and long-term strategic goals. For individual founders or small teams of innovators who are just starting out, projecting moderate profitability, and seeking to minimize self-employment taxes while maintaining flexibility, an S Corp can be an excellent choice. This is particularly true for service-based drone businesses like aerial inspection or mapping, or small-scale specialized drone component manufacturers.
However, if a tech startup anticipates rapid scaling, significant external investment from venture capitalists, or plans for a future IPO, the C Corporation structure or an LLC (retaining partnership taxation) might be more suitable from the outset or become necessary down the line. The ability to issue multiple classes of stock, raise capital from diverse investor types, and offer more flexible equity incentives can outweigh the initial double-taxation concern for companies with high growth potential.
Ultimately, “what does S Corporation mean” for a tech innovator boils down to understanding its tax advantages in managing operational profits against a backdrop of specific structural limitations. Consulting with legal and financial professionals is crucial to determine if this unique tax election is the optimal foundation for building and scaling the next generation of flight technology, imaging solutions, or AI-powered drone systems.