
While the direct query regarding the precise average age of retirement in the U.S. might seem like a straightforward demographic statistic, a deeper, more insightful understanding of this evolving metric is increasingly forged within the crucible of Tech & Innovation. Modern technological advancements are not merely providing new ways to measure this age, but are actively shaping the factors that influence when individuals choose, or are able, to leave the workforce. From advanced data analytics that distill complex societal trends to health tech that extends working lives, and from automation that reshapes career paths to fintech tools empowering new retirement strategies, technology is an undeniable force in the evolving narrative of American retirement.
Unpacking the Demographic Realities Through Data-Driven Innovation
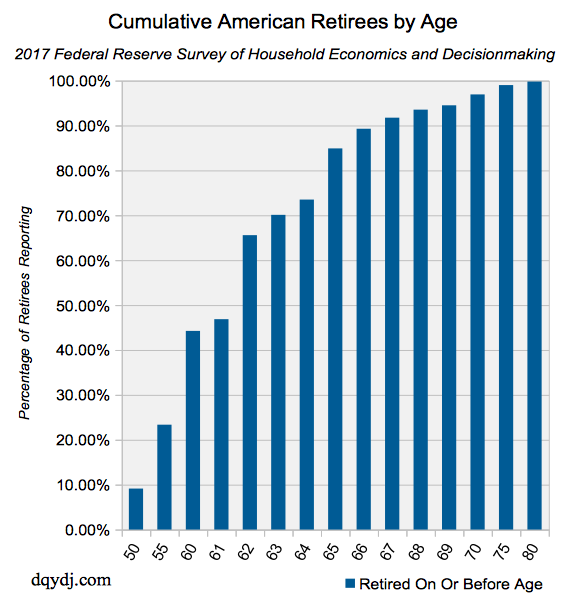
Determining the average age of retirement is a complex endeavor, historically relying on surveys and aggregated statistical reports. However, the contemporary landscape leverages sophisticated technological tools to extract richer, more granular insights. The traditional approach provides a snapshot, but Tech & Innovation offers a dynamic, predictive model, enabling a nuanced comprehension of the ‘why’ and ‘how’ behind retirement trends.
The Role of Advanced Analytics and AI in Trend Identification
Big data analytics and artificial intelligence (AI) are revolutionizing our capacity to understand and forecast demographic shifts, including the critical metric of retirement age. Governments, research institutions, and financial services companies are deploying AI-powered platforms to process vast datasets—encompassing everything from labor force participation rates and economic indicators to health statistics and consumer spending habits. Machine learning algorithms can identify subtle patterns and correlations that human analysis might miss, allowing for more accurate predictions of future retirement ages based on current trajectories and emerging societal shifts.
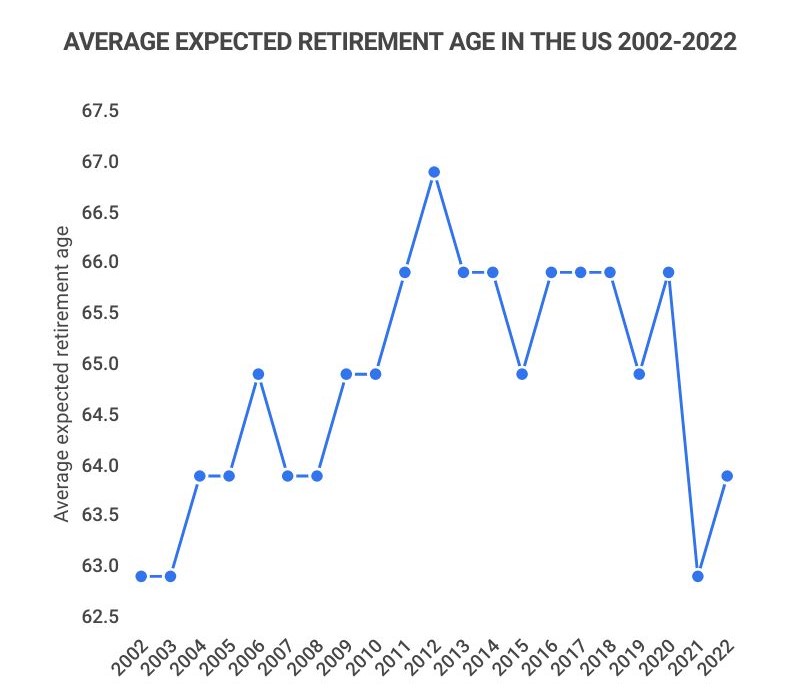
For instance, predictive models can analyze the impact of various policy changes, economic downturns, or technological disruptions on retirement decisions. Natural Language Processing (NLP) tools can even sift through qualitative data from social media, news articles, and public forums to gauge sentiment and prevailing attitudes towards work and retirement, offering insights into generational differences and cultural influences. This isn’t just about crunching numbers; it’s about leveraging computational power to map the intricate web of socio-economic factors that collectively determine when Americans step away from full-time employment. The average retirement age, therefore, becomes less of a static figure and more of a dynamic output of complex, technologically-analyzed systems.
Technological Influences on Longevity and Workforce Participation
Beyond merely analyzing data, Tech & Innovation directly impacts the average age of retirement by influencing individual health, capabilities, and the nature of work itself. These advancements are both enabling longer working lives and, in some cases, necessitating earlier exits, creating a multifaceted impact on the national average.
Health Tech and Extended Working Lives
One of the most profound ways technology influences retirement age is through advancements in healthcare and personal well-being. Wearable devices, powered by sophisticated sensors and AI, offer continuous health monitoring, tracking everything from heart rate variability to sleep patterns. This proactive approach to health management allows individuals to identify potential issues earlier, engage in preventive care, and manage chronic conditions more effectively. The result is a healthier, more active aging population, capable of remaining productive in the workforce for longer periods.
Furthermore, medical innovations, including personalized medicine, advanced diagnostics, and minimally invasive surgical techniques, are extending lifespans and improving quality of life significantly. These breakthroughs allow many individuals to maintain the physical and mental acuity required for demanding careers well into their 60s and 70s, fundamentally shifting the traditional perceptions of “retirement age.” Biometric data analysis, often integrated with wellness programs, can also provide employers with insights into workforce health trends, informing strategies to support older employees and retain their valuable experience.
Automation, AI, and Shifting Job Landscapes
The rise of automation and artificial intelligence is reshaping industries and job roles across the U.S., presenting a dual impact on retirement age. On one hand, AI and robotics are taking over repetitive, physically demanding, or dangerous tasks, making certain jobs less strenuous and potentially extending the careers of workers in those fields. For example, in manufacturing, advanced robotics can assist human operators, reducing physical strain and injury risk. In data-intensive fields, AI augments human analysis, allowing professionals to focus on higher-level strategic thinking rather than manual data processing.
On the other hand, rapid technological obsolescence and the displacement of certain job functions by AI can force some older workers into early retirement if they lack the skills for new, tech-driven roles. The need for continuous learning and reskilling has become paramount. Innovative online learning platforms, often AI-curated for personalized learning paths, are critical in helping individuals adapt to these evolving demands, potentially delaying retirement by equipping them with the competencies needed for the jobs of tomorrow. This technological pressure creates a dynamic where adaptability, supported by innovative educational tech, becomes key to determining individual retirement timelines.
Innovation in Financial Planning and Remote Work
Technology’s influence extends deeply into the financial aspects of retirement planning and the very structure of work. Innovations in fintech and the widespread adoption of remote work are offering new pathways and considerations for individuals approaching their golden years.
Fintech Solutions for Retirement Security
Fintech, or financial technology, is democratizing and personalizing retirement planning, empowering individuals with tools previously available only to high-net-worth clients. AI-driven robo-advisors can craft and manage diversified investment portfolios tailored to individual risk tolerance and retirement timelines, often at a fraction of the cost of traditional human advisors. These platforms continuously monitor market conditions and rebalance portfolios, utilizing complex algorithms to optimize returns and mitigate risks.
Beyond investment management, fintech apps provide sophisticated budgeting tools, expenditure tracking, and retirement calculators that project future financial needs based on current savings and lifestyle choices. Many integrate with other financial accounts, offering a holistic view of one’s financial health and identifying areas for improvement. Cryptocurrencies and blockchain technology are also emerging as new avenues for wealth storage and transfer, albeit with higher volatility, offering innovative alternatives for some forward-thinking individuals planning for long-term financial security. These technological advancements enable greater transparency, control, and efficiency in accumulating and managing retirement assets, allowing more people to plan proactively for their desired retirement age.
The Remote Work Revolution and Flexible Retirement
The pervasive adoption of remote work technologies, accelerated by global events, has fundamentally altered the paradigm of employment and retirement. Video conferencing platforms, cloud-based collaboration tools, and secure VPNs have made it possible for millions to work effectively from anywhere. This flexibility is a significant factor in shaping retirement decisions.
For many, remote work offers a “glide path” into retirement, allowing them to transition from full-time, in-office roles to part-time, remote consulting, or project-based work. This flexibility provides a crucial bridge, allowing individuals to maintain income, intellectual engagement, and a sense of purpose without the full demands of a traditional career. The ability to work from a different city, state, or even country also opens up lifestyle options that were previously incompatible with career longevity. This technological enablement of geographical and schedule flexibility empowers individuals to define their “retirement” on their own terms, often extending their working lives beyond what was traditionally possible or desirable. The average age of full cessation of work is therefore being pushed further, replaced by more gradual, semi-retired phases enabled by digital connectivity.
The Future of Retirement: A Tech-Driven Evolution
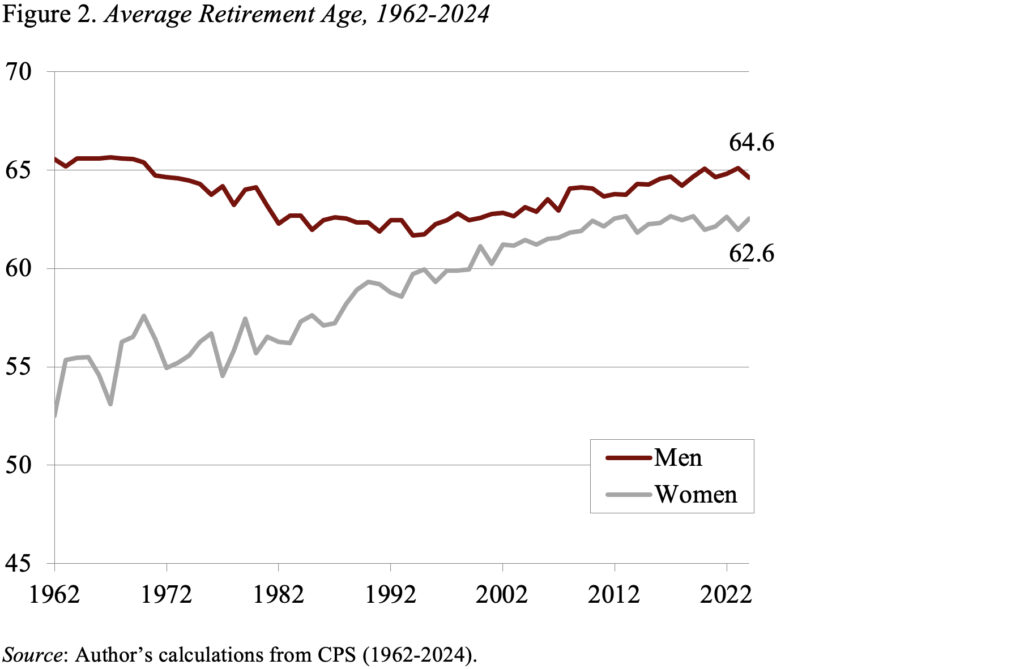
The question “what is the average age of retirement in us” is increasingly intertwined with the relentless pace of Tech & Innovation. It’s not a static number to be observed, but a dynamic outcome influenced by a confluence of technological forces. As health tech extends human potential, as AI redefines work, and as fintech empowers personal finance, the concept of retirement itself is undergoing a profound evolution. The future will likely see a more individualized and flexible approach to retirement, where an “average age” becomes a less significant metric than the ability of individuals, supported by technology, to craft their own unique transitions from active careers to fulfilling later life phases. Understanding this evolving landscape demands an ongoing embrace of the innovative tools and insights that technology provides.