
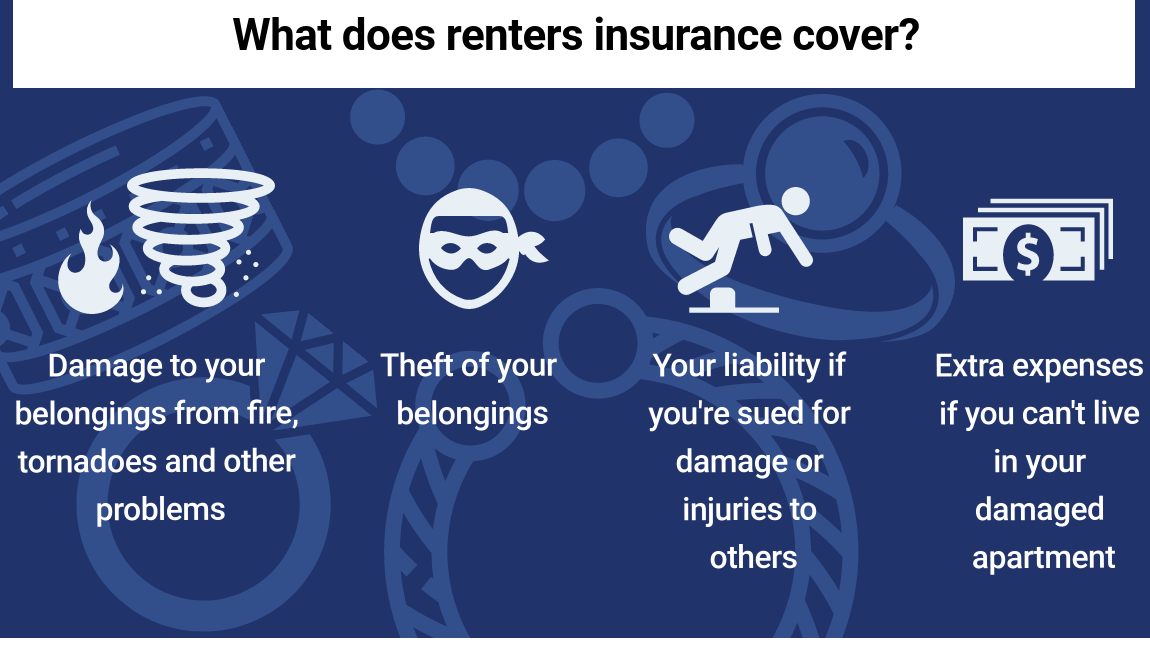
Personal liability coverage within a renters insurance policy is a crucial, often underestimated, safeguard designed to protect tenants from financial ruin in the event they are found legally responsible for certain incidents. In its essence, this coverage steps in when you, a member of your household, or even your pet, accidentally cause bodily injury to another person or damage to someone else’s property, typically occurring either within your rented dwelling or anywhere else in the world. As technology continues its rapid advancement, introducing innovative devices like consumer drones with sophisticated capabilities such as AI follow mode, autonomous flight, mapping, and remote sensing, the scope and necessity of understanding this coverage become even more pronounced for the modern renter who embraces such innovations.

This critical component of renters insurance generally covers the legal costs, medical bills, and property repair or replacement expenses that can arise from a covered incident. Imagine a scenario where a visitor slips and falls inside your apartment, sustaining an injury, or where your child accidentally breaks a neighbor’s expensive antique. Without personal liability coverage, the financial burden of these events would fall squarely on your shoulders, potentially leading to significant out-of-pocket costs, legal fees, and even devastating lawsuits. For renters who are early adopters of cutting-edge technology, the nuances of this coverage become particularly relevant, as the operation of advanced devices introduces a new layer of potential liabilities that traditional insurance might not fully anticipate or explicitly address.
The Evolving Landscape of Personal Liability for Tech-Savvy Renters
The rise of consumer drones and other smart home technologies has introduced unprecedented capabilities for individuals, transforming hobbies, creativity, and even professional pursuits. However, with this power comes an increased potential for liability. For a renter who owns and operates a drone equipped with AI-driven navigation, high-resolution cameras, or sophisticated mapping sensors, understanding the precise boundaries of their personal liability coverage is paramount. The very innovations that make these devices so appealing – autonomous flight, remote sensing for personal projects, or cinematic aerial capture – also present unique risks that can trigger claims against your personal liability.
Consider a drone operating autonomously near your rented property. While designed for precision, even the most advanced systems can encounter unforeseen glitches or environmental factors. If your drone, perhaps while utilizing an AI follow mode, veers off course and causes damage to a neighbor’s roof or, worse, leads to a minor injury to a bystander, your personal liability coverage is the primary line of defense. This extends beyond just physical damage; the advanced imaging capabilities of drones, particularly those used for mapping or remote sensing, can inadvertently infringe on privacy rights, potentially leading to legal claims that personal liability coverage may also help mitigate.
Accidental Damage to Property from Drone Operation
One of the most common concerns for drone owners, especially those living in multi-unit dwellings or dense neighborhoods, is the risk of accidental property damage. Even a small drone, when operating autonomously or under manual control, can cause significant harm if it crashes into a window, a parked car, or a sensitive piece of property. Renters insurance personal liability is typically designed to cover these types of accidents, paying for the repairs or replacement costs for damaged property belonging to others.
For example, if your drone, while experimenting with a new autonomous flight path feature, unexpectedly collides with your landlord’s shed or a neighbor’s elaborate garden trellis, your liability coverage would likely step in. This can save you thousands of dollars in out-of-pocket expenses. However, the exact extent of coverage and any potential exclusions related to “aircraft” (which some policies might categorize drones as) or “motorized vehicles” would need careful review. The innovative nature of modern drones, capable of significant power and altitude, means the potential for damage is higher than with simpler remote-controlled toys of the past, making this coverage increasingly vital.
Bodily Injury Caused by Drone Operation
Beyond property damage, the risk of bodily injury is another serious consideration. A drone, particularly larger models or those with exposed propellers, can cause injury if it collides with a person. This risk is amplified when drones are flown in public spaces or near crowds, or if an autonomous feature malfunctions. Should your drone, perhaps during a mapping exercise or an aerial filmmaking attempt, accidentally strike a passerby, causing injury, your personal liability coverage would be triggered.
This coverage would help pay for the injured party’s medical expenses, lost wages, and potentially even pain and suffering, as well as any legal defense costs if a lawsuit arises. The sophisticated sensors and navigation systems found in many modern drones are designed to prevent such incidents, but no technology is infallible. Renters engaging with drone innovation must recognize that while they harness cutting-edge capabilities, they also assume a degree of responsibility for the drone’s operation and any harm it might inadvertently cause.
Privacy Concerns and Legal Ramifications for Remote Sensing
Modern drones equipped with high-definition cameras and remote sensing capabilities open up new avenues for potential legal issues, specifically related to privacy. While using your drone for personal aerial photography or mapping your own property, it’s possible to inadvertently capture images or data of neighboring properties or individuals without their consent. This can lead to allegations of invasion of privacy, trespass, or harassment.
In such instances, your personal liability coverage might offer defense costs and potential settlement funds, depending on the specific policy language and the nature of the claim. This area is still evolving legally, but as drones become more ubiquitous and their imaging capabilities more advanced (e.g., thermal imaging, sophisticated optical zoom), the potential for privacy-related litigation grows. Renters who utilize these innovative features for mapping, remote sensing, or even just casual recording must be acutely aware of local laws and societal expectations regarding privacy, as their renters insurance might be their first and only defense in a privacy dispute.
Navigating Exclusions and Policy Limits for Tech Owners
While personal liability coverage is robust, it’s not without its limitations and specific exclusions. For renters deeply invested in innovative technologies like drones, understanding these caveats is crucial. Standard renters insurance policies are designed for typical household risks, and the rapid evolution of tech means that some policies may not have explicitly updated language to cover every new scenario involving advanced devices.
Specific Exclusions for Aircraft or Business Use
One of the most critical areas to investigate is how your policy defines “aircraft.” Some older policies or standard templates might categorize drones as miniature aircraft, potentially leading to an exclusion for any damage or injury caused by them. If your policy has an “aircraft exclusion,” any incident involving your drone, regardless of its size or sophistication, might not be covered. It’s imperative for drone-owning renters to clarify this with their insurance provider or agent.
Furthermore, if you use your drone for any commercial purpose – even a small side hustle like aerial photography for local real estate agents or mapping services – your personal renters insurance policy will almost certainly exclude coverage for incidents arising from such business activities. Personal liability coverage is designed for personal risks, not professional ones. Renters engaging in commercial drone operations would need a separate commercial liability policy specifically tailored for drone businesses. This distinction is vital for those leveraging drone innovation for entrepreneurial ventures.
Adequate Coverage for High-Value Tech Assets
Beyond liability, consider the value of your drone and related accessories. While personal liability protects you from claims by others, your renters insurance policy also typically includes personal property coverage for your own belongings. High-end drones, FPV systems, gimbal cameras, and other sophisticated tech can represent a significant investment. Ensuring your policy limits for personal property are sufficient to cover the replacement cost of these items in case of theft, fire, or other covered perils is essential. This protects your investment in these innovative tools, allowing you to continue exploring the frontiers of aerial technology without undue financial risk.
Proactive Measures for Responsible Drone Renters
For the renter embracing tech innovation, especially drone technology, a proactive approach to risk management is the best defense. This goes beyond just having renters insurance; it involves responsible operation, continuous education, and clear communication with your insurer.
Firstly, adhere to all local, state, and federal regulations regarding drone operation. This includes respecting no-fly zones, maintaining visual line of sight, and obtaining any necessary permits or registrations. Responsible operation significantly reduces the likelihood of incidents that would trigger a liability claim. Secondly, regularly update yourself on drone safety best practices and new technological advancements that might influence safe operation, such as improved obstacle avoidance systems or geo-fencing features.
Finally, engage in an open dialogue with your insurance provider. Explicitly discuss your drone ownership and any unique functionalities (e.g., autonomous flight, remote sensing capabilities) to understand how they are treated under your personal liability coverage. If standard renters insurance proves insufficient, your insurer might offer endorsements or specialized policies that provide more comprehensive protection for your innovative tech activities. Investing in drone-specific liability insurance, even if your renters policy offers some coverage, can provide an additional layer of security, especially for more advanced or higher-risk operations. By taking these proactive steps, renters can enjoy the benefits of cutting-edge technology while effectively managing the associated liabilities.