
CD laddering is a sophisticated yet accessible financial strategy designed to optimize the returns on Certificates of Deposit (CDs) while simultaneously managing liquidity and mitigating interest rate risk. In an era where individuals seek smarter, more efficient ways to manage their personal finances, CD laddering stands out as a pragmatic application of financial innovation, providing a structured approach to leveraging these often-overlooked savings instruments. It’s a testament to how established financial products can be reimagined through strategic planning to serve modern financial goals, making it a key technique within personal finance and investment management.
The Core Concept of CD Laddering
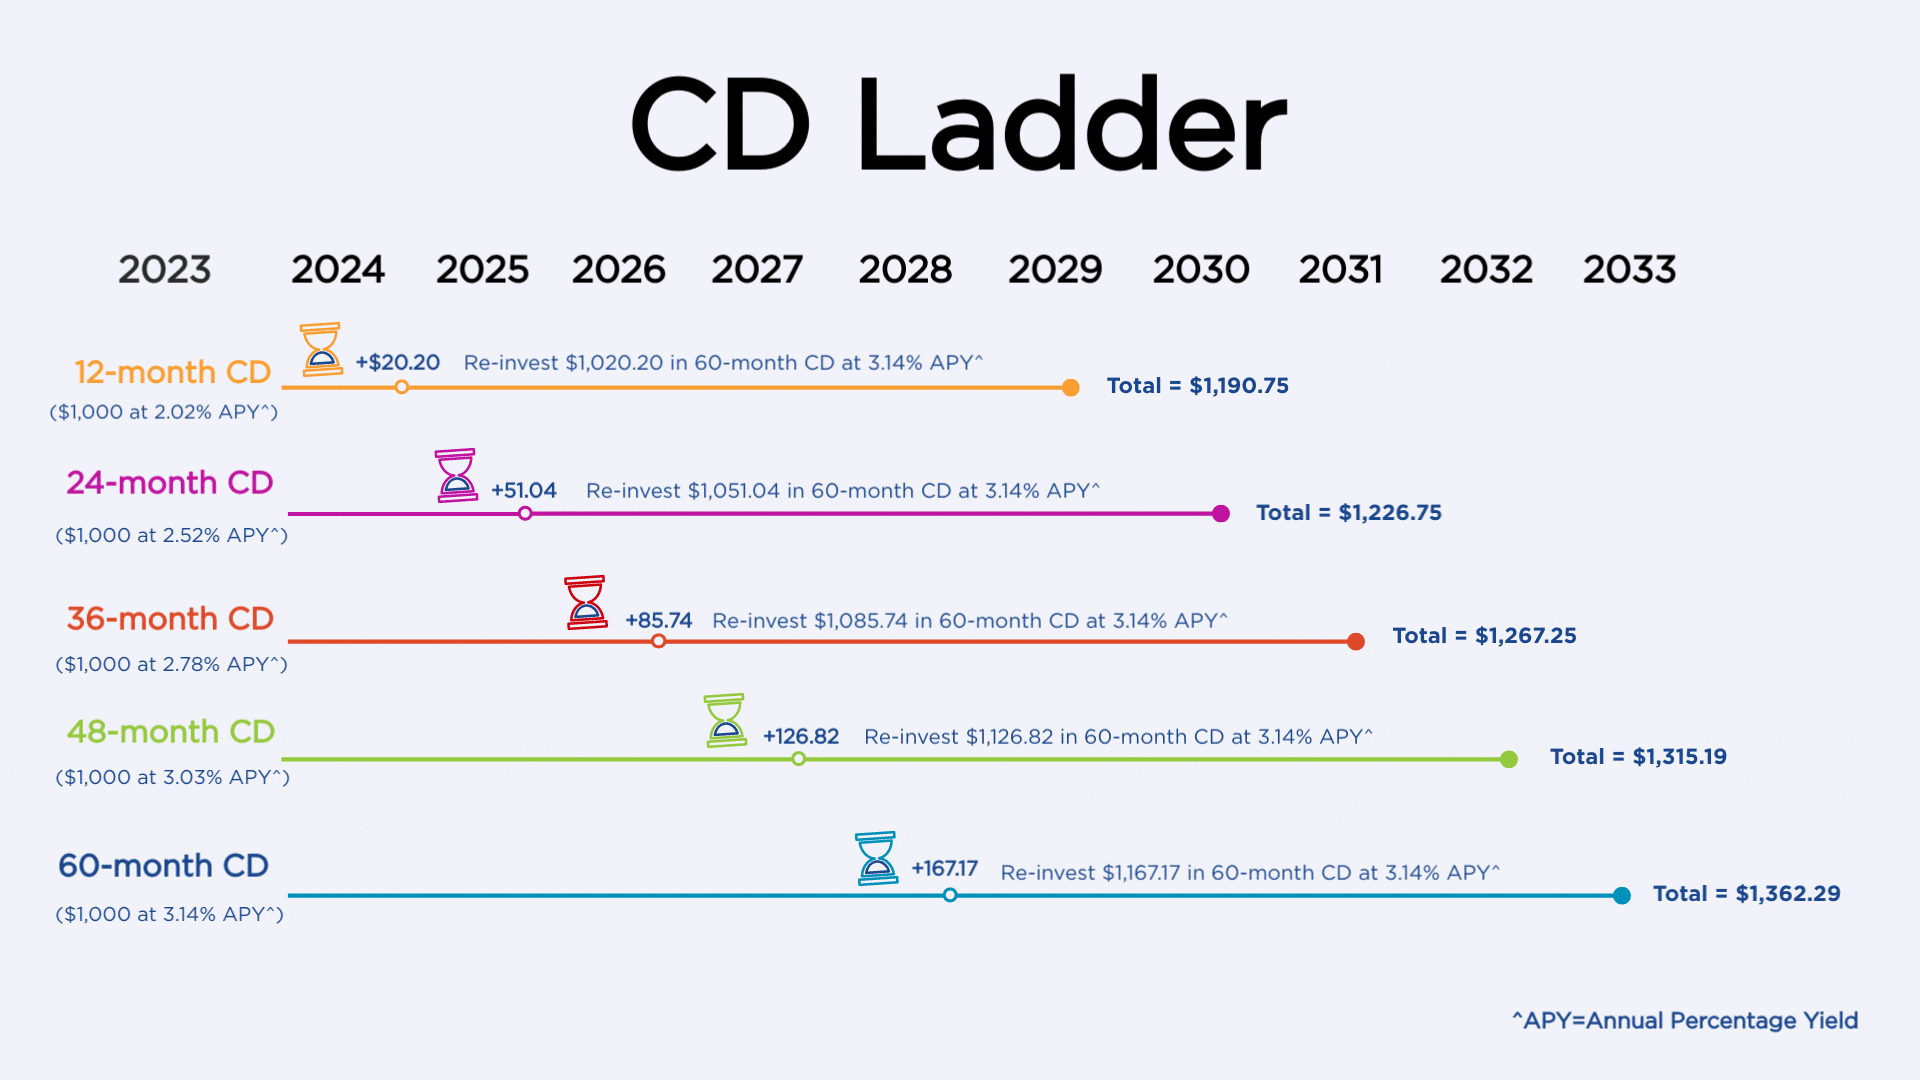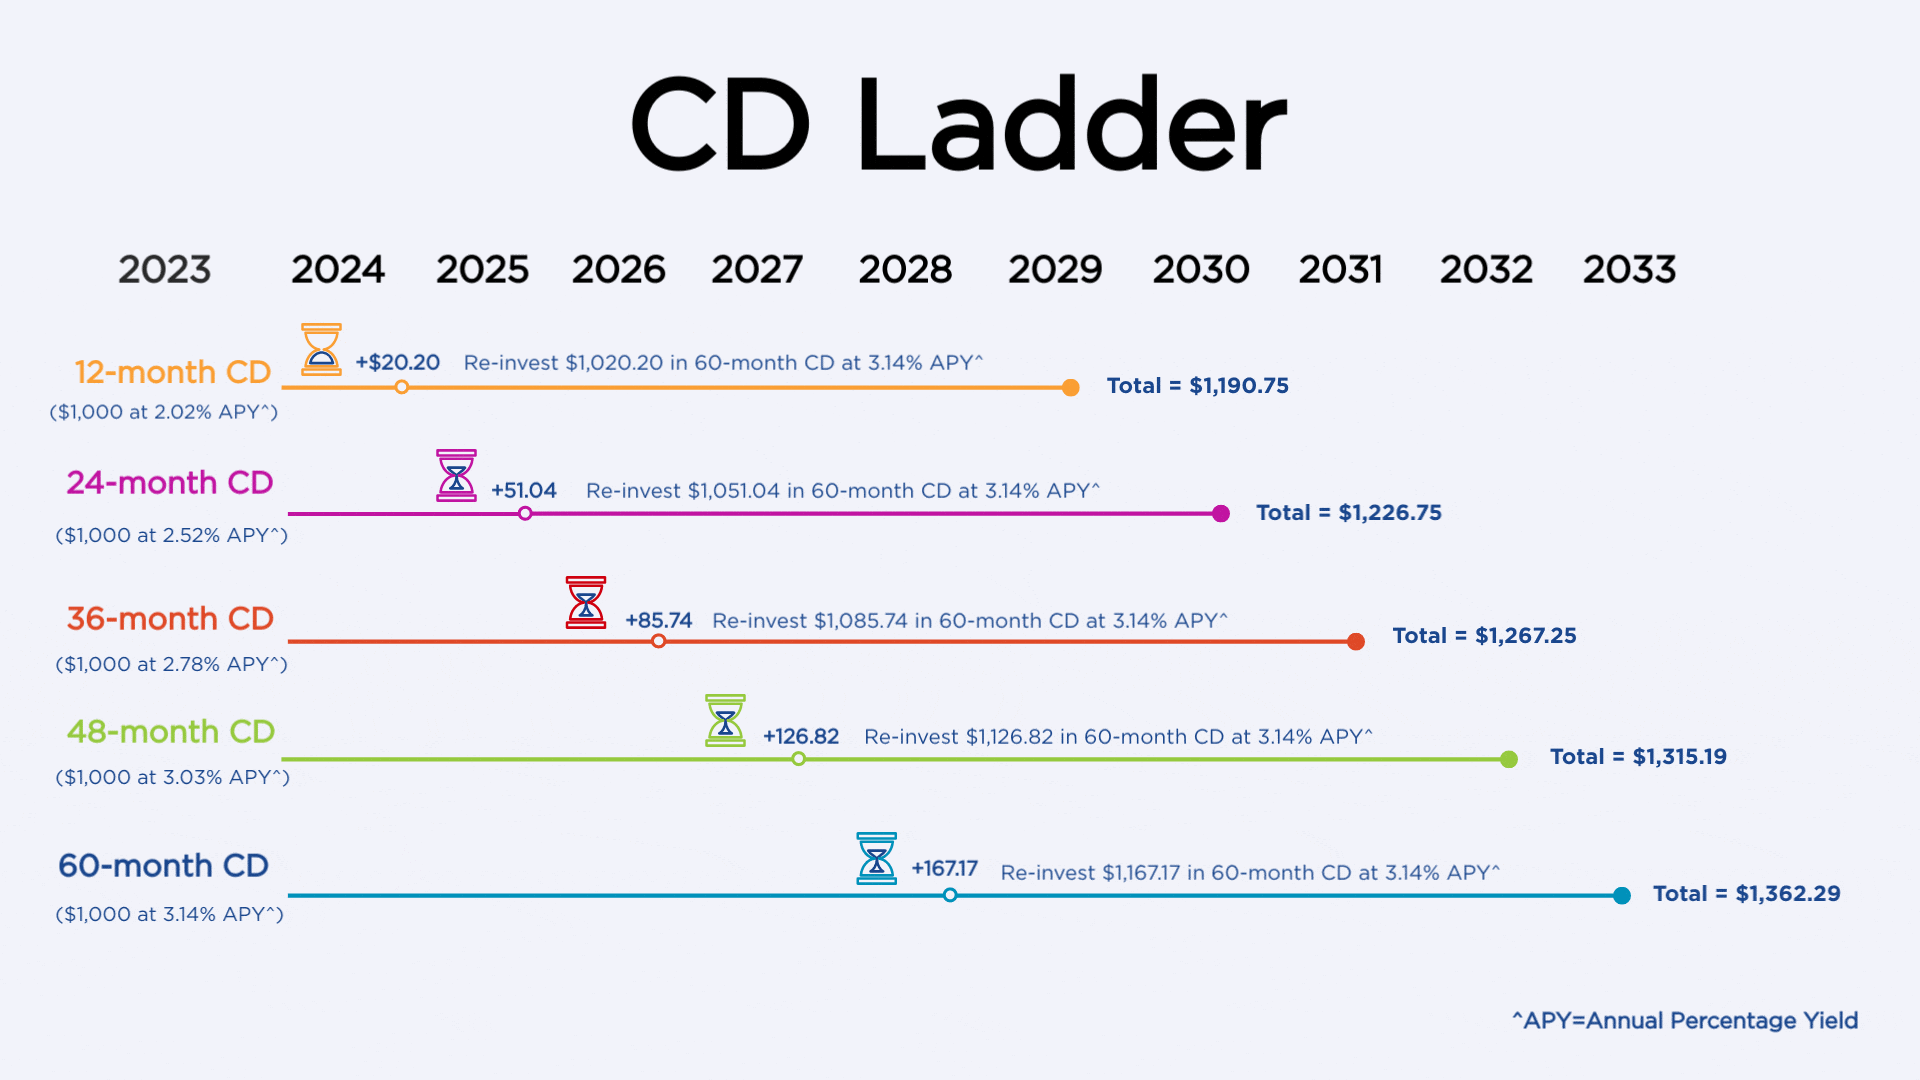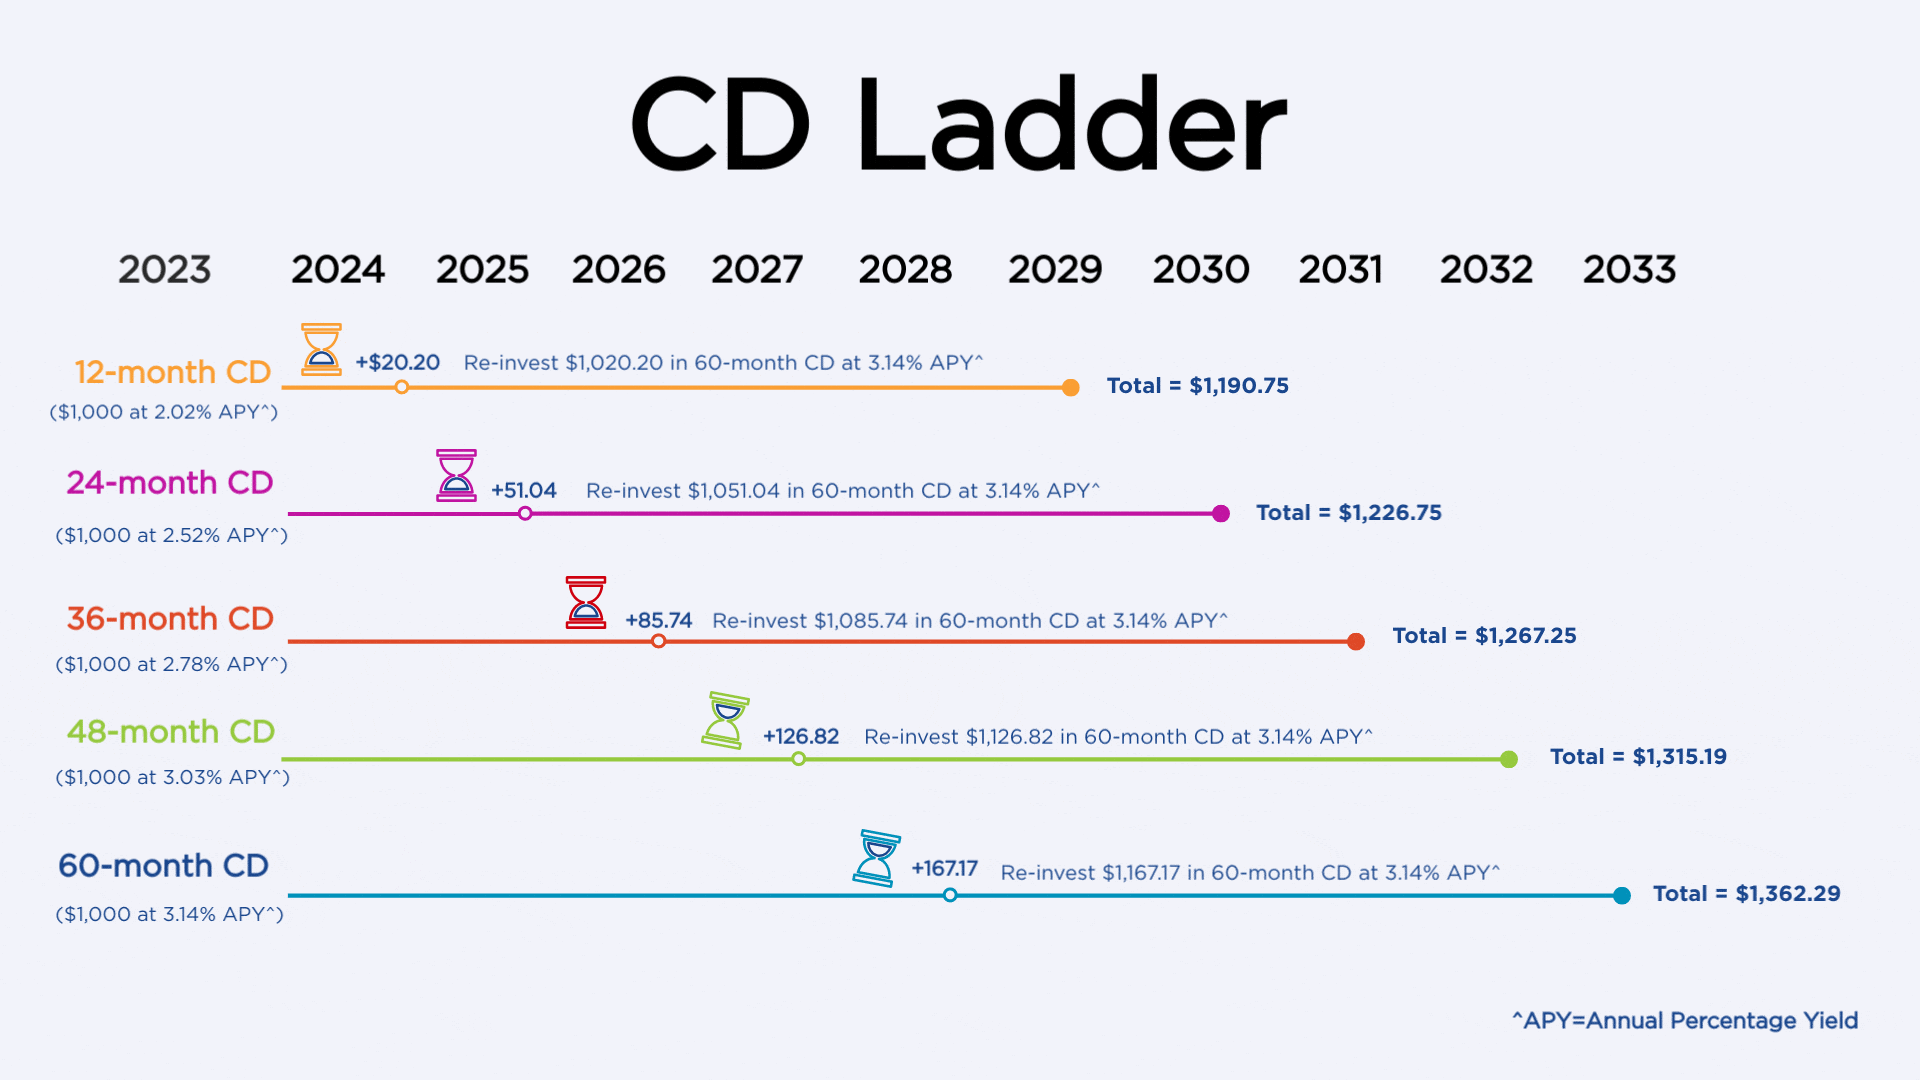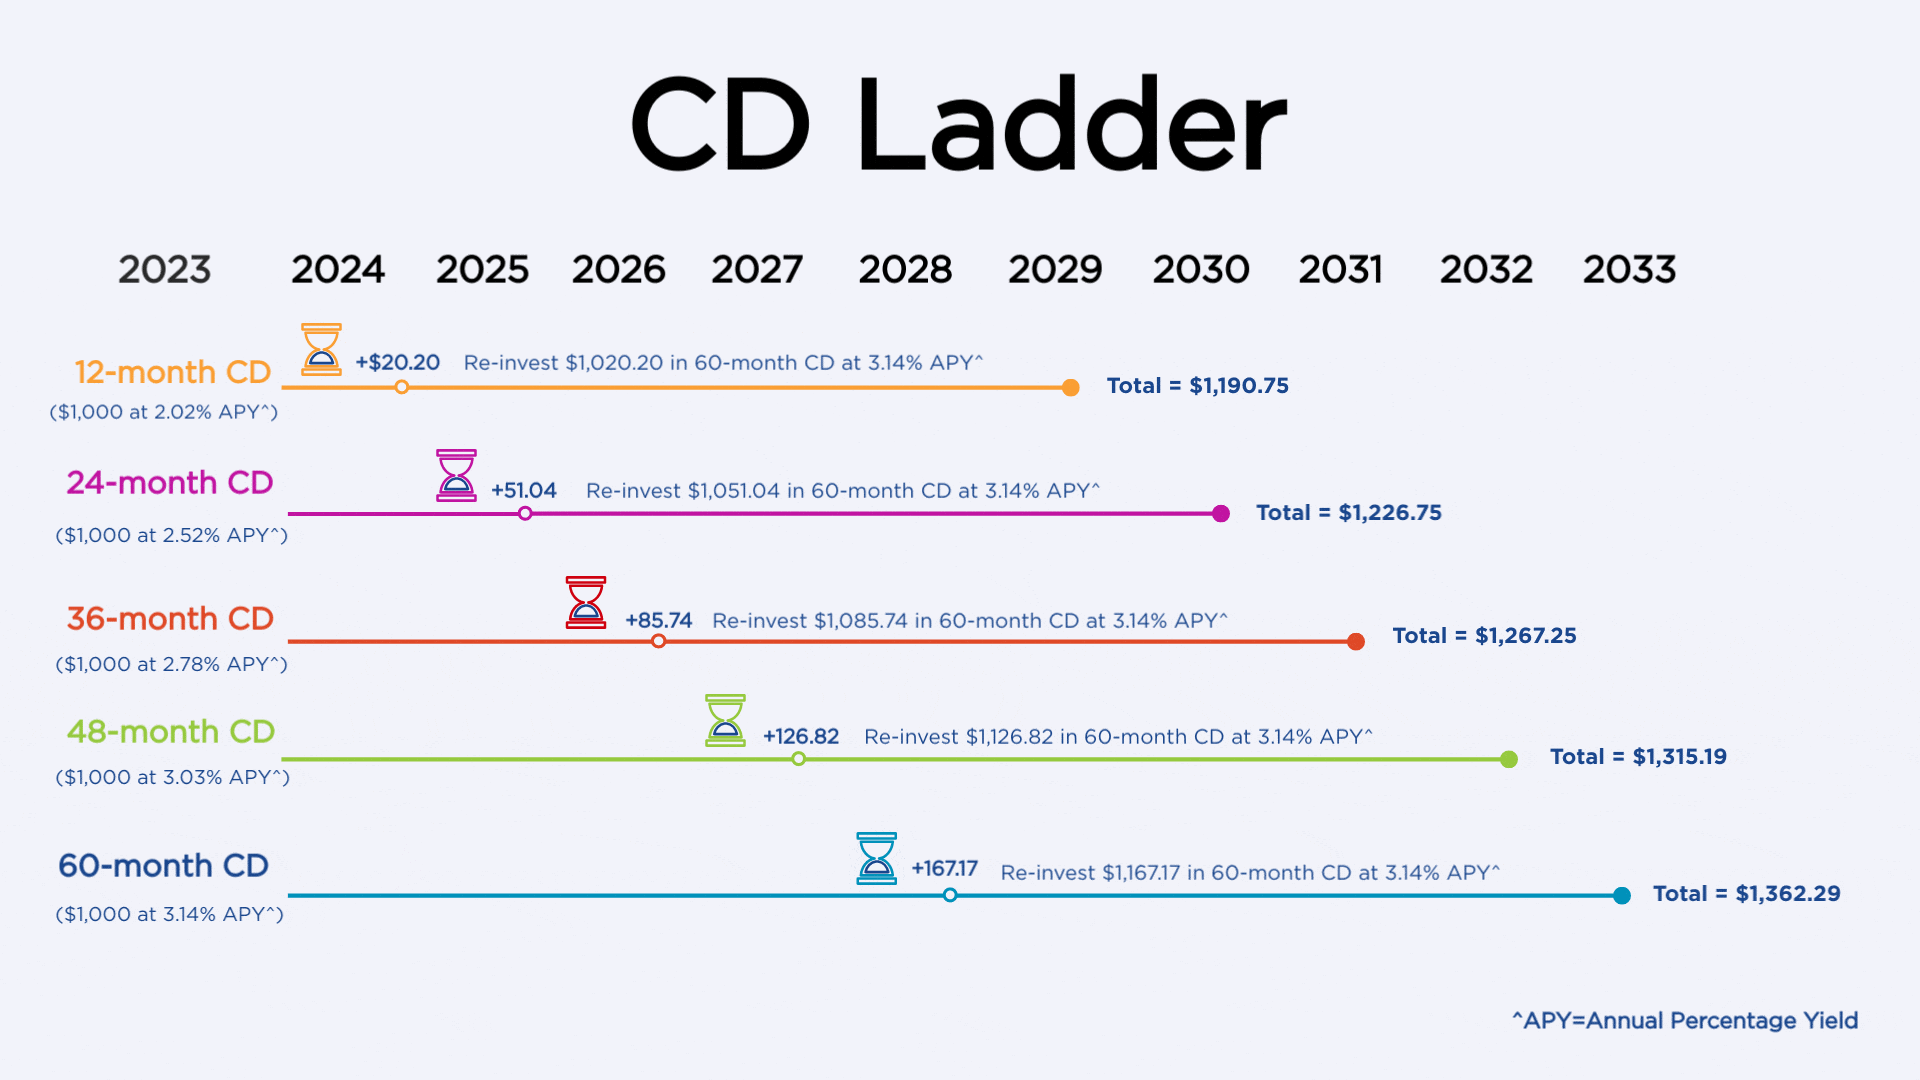
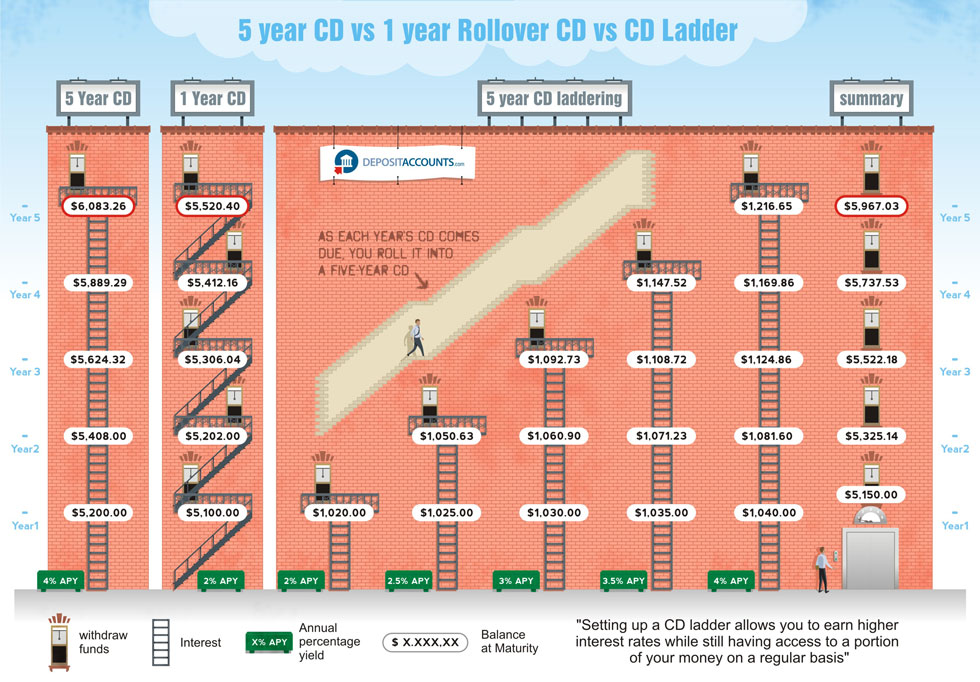
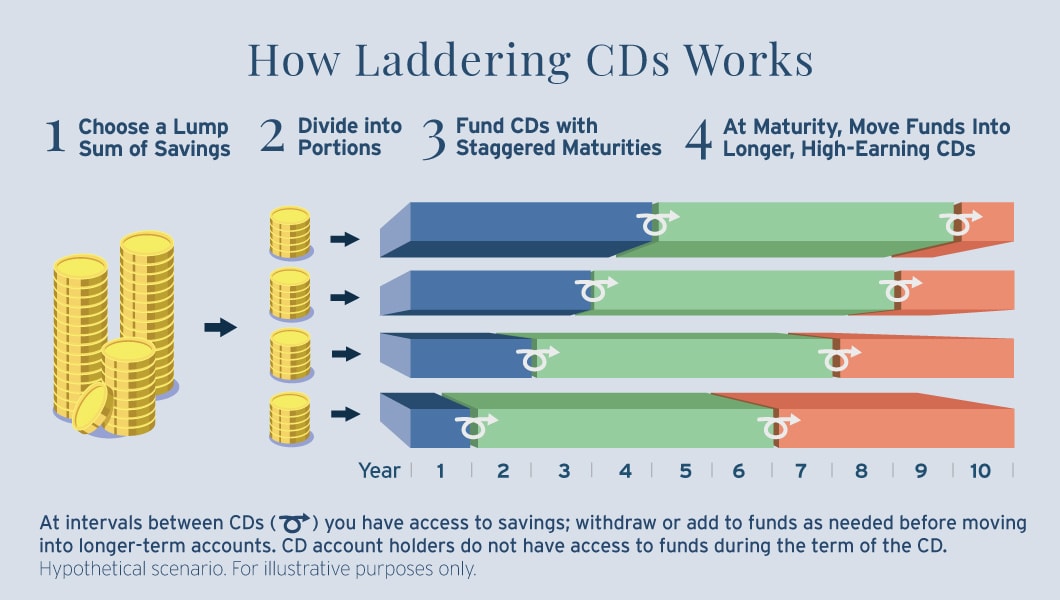
At its heart, CD laddering involves dividing a lump sum of money into several smaller portions and investing each portion in a CD with a different maturity date. Instead of putting all funds into a single CD for a fixed term, a ladder creates a staggered series of maturities. As each shorter-term CD matures, the funds are reinvested into a new, longer-term CD at the end of the ladder. This cyclical process ensures that a portion of the investment becomes available periodically, offering both liquidity and the opportunity to consistently capture potentially higher interest rates typically offered by longer-term CDs. It’s a methodical approach to balancing yield and accessibility, providing a structured framework for capital preservation and growth.
How a CD Ladder Works
To illustrate, consider an individual with $50,000 to invest in CDs. Instead of purchasing one five-year CD, a laddering strategy might involve:
- Year 1: Invest $10,000 in a 1-year CD.
- Year 2: Invest $10,000 in a 2-year CD.
- Year 3: Invest $10,000 in a 3-year CD.
- Year 4: Invest $10,000 in a 4-year CD.
- Year 5: Invest $10,000 in a 5-year CD.
After one year, the 1-year CD matures. The $10,000 principal, plus earned interest, is then reinvested into a new 5-year CD. This effectively shifts the entire ladder forward by one year. The following year, the original 2-year CD matures, and those funds are also reinvested into a new 5-year CD. This continuous rolling process means that every year, a portion of the investor’s funds becomes liquid, and they can then take advantage of prevailing interest rates by reinvesting in a new long-term CD. The ladder is effectively “extended” at the long end each time a short-term CD matures. This systematic reinvestment ensures that the investor is always benefiting from the higher rates of longer-term CDs while retaining regular access to a portion of their capital.
Advantages of Implementing a CD Ladder
The appeal of CD laddering stems from its ability to address several common challenges faced by investors in fixed-income markets. It’s a proactive strategy that offers significant benefits, transforming simple CDs into a dynamic component of a broader financial plan.
Balancing Liquidity and Returns
One of the primary advantages of a CD ladder is its capacity to provide periodic access to funds without sacrificing the higher interest rates typically associated with longer-term investments. Traditional CDs lock up capital for their entire term, potentially leading to penalties for early withdrawals. With a ladder, a segment of the investment matures regularly, making those funds available for reinvestment, spending, or transfer, while the remaining, longer-term CDs continue to earn at potentially higher rates. This inherent design provides a superior balance compared to investing in a single long-term CD, which offers higher rates but less liquidity, or a single short-term CD, which offers high liquidity but lower rates. The staggered maturities act as a built-in liquidity mechanism, allowing investors to meet potential short-to-medium-term financial needs without disrupting their entire investment strategy.
Mitigating Interest Rate Risk
Interest rate fluctuations are a constant concern for fixed-income investors. If rates rise after an investor locks into a long-term CD, they miss out on the opportunity to earn more interest. Conversely, if rates fall, locking into a long-term CD at a higher rate can be beneficial. A CD ladder provides a clever hedge against this uncertainty. By having CDs mature at regular intervals, investors are continuously exposed to current interest rates. When a CD matures, the funds are reinvested at the prevailing market rate, whether higher or lower. This prevents the investor from being entirely locked into an unfavorable rate environment for their entire investment. Over time, this strategy helps to average out the return on investment, providing a more stable and predictable income stream in an unpredictable market. It’s an innovative approach to managing the inherent volatility of interest rate cycles.
Simplicity and Predictability
For many investors, the complexity of managing a diverse portfolio can be daunting. CD laddering offers a relatively straightforward and predictable investment approach. Once established, the system largely runs itself, requiring attention primarily when a CD matures. The rules are clear, the returns are fixed (for the term of each CD), and the process of reinvestment is repetitive and easy to understand. This simplicity makes it an attractive option for conservative investors, retirees seeking stable income, or anyone looking for a low-maintenance way to enhance their savings without delving into more volatile investment vehicles. The clear maturity schedule allows for better financial planning and budgeting, as investors know exactly when certain funds will become available.
Building Your CD Ladder
Constructing an effective CD ladder requires thoughtful planning and consideration of individual financial circumstances. It’s not a one-size-fits-all solution, but rather a flexible framework that can be tailored to specific needs and goals.
Determining Your Initial Investment
The first step is to decide the total amount of money you wish to allocate to your CD ladder. This sum should be money you don’t anticipate needing for immediate expenses, as it’s intended for medium to long-term savings. The total amount will then be divided into equal segments, corresponding to the number of rungs in your ladder. For instance, a $100,000 investment for a five-rung ladder (1-year, 2-year, 3-year, 4-year, 5-year CDs) would mean allocating $20,000 to each CD. The initial investment decision sets the scale for the entire ladder.
Choosing Your Ladder Structure
The structure of your ladder refers to the number of CDs and the length of their terms. Common ladder structures include:
- Annual Ladder: CDs maturing every year (e.g., 1-year, 2-year, 3-year, 4-year, 5-year CDs). This is the most popular choice, offering frequent liquidity and consistent rate adjustments.
- Biennial Ladder: CDs maturing every two years (e.g., 2-year, 4-year, 6-year, 8-year, 10-year CDs). This offers less frequent liquidity but potentially higher overall rates due to longer terms.
- Short-Term Ladder: Focusing on shorter maturities (e.g., 3-month, 6-month, 9-month, 1-year CDs) for greater liquidity and quick responses to rising rates, though typically at lower yields.
The choice depends on your liquidity needs, interest rate outlook, and investment horizon. A longer-term ladder provides greater interest rate capture, while a shorter-term ladder offers more frequent access to funds and quicker adaptation to rising rates.
Selecting CD Terms and Rates
When selecting specific CDs, compare rates from various financial institutions. Online banks often offer more competitive rates than traditional brick-and-mortar banks due to lower overheads. Pay close attention to the Annual Percentage Yield (APY), which accounts for compounding interest. Also, consider the minimum deposit requirements for each CD and any early withdrawal penalties. While the laddering strategy aims to avoid early withdrawals, understanding these penalties is crucial for unforeseen circumstances. It’s also wise to check if the CDs are FDIC-insured (or NCUA-insured for credit unions) up to the maximum legal limit to protect your principal.
Potential Considerations and Drawbacks
While CD laddering is a robust strategy, it’s important to acknowledge its limitations and potential drawbacks. Understanding these helps investors make informed decisions and manage expectations.
Early Withdrawal Penalties
Despite the periodic liquidity offered by a CD ladder, individual CDs within the ladder are still subject to early withdrawal penalties if funds are needed before their scheduled maturity. While the strategy aims to provide regular access to a portion of your funds, a sudden, unforeseen need for a larger sum might require breaking a CD that isn’t yet mature, incurring a penalty that could erode some of the earned interest. This underscores the importance of only allocating funds to the ladder that are not required for immediate or emergency expenses.
Interest Rate Environment
CD laddering performs exceptionally well in environments where interest rates are stable or rising. In such scenarios, as shorter-term CDs mature, they can be reinvested into new longer-term CDs at increasingly higher rates, enhancing overall returns. However, in a persistently falling interest rate environment, the strategy’s benefits are diminished. As each CD matures, the reinvestment will occur at a lower rate, potentially leading to a gradual decrease in overall portfolio yield. While it still offers liquidity protection, the rate mitigation aspect works less favorably in a declining rate market. Investors must weigh the current and projected interest rate landscape when evaluating the optimal time to implement or adjust a CD ladder.
Advanced Strategies and Variations
Beyond the basic setup, innovators in financial planning have developed variations and advanced applications of CD laddering to suit specific risk profiles and market outlooks. These demonstrate the adaptability of the core concept.
The Barbell Strategy
A barbell strategy in CD investing is a variation of laddering that focuses on extreme maturities rather than a sequential distribution. Instead of having CDs mature evenly across the spectrum (e.g., 1-5 years), an investor might put a significant portion of their funds into very short-term CDs (e.g., 3-6 months) and another significant portion into very long-term CDs (e.g., 5-10 years), with little or no investment in mid-range maturities. The short-term CDs provide frequent liquidity and the ability to quickly capitalize on rising rates, while the long-term CDs lock in higher rates for an extended period. This strategy is particularly useful for investors with a strong conviction about future interest rate movements or those who prioritize both maximum flexibility and long-term yield.
Callable CDs and Their Role
Callable CDs introduce another layer of complexity and potential reward. A callable CD gives the issuing bank the option to “call” or redeem the CD before its maturity date. In exchange for this call option, callable CDs typically offer a slightly higher interest rate than non-callable CDs of comparable terms. While this higher rate is attractive, the call feature means that if interest rates fall significantly, the bank might call the CD, forcing the investor to reinvest their funds at a lower prevailing rate. Conversely, if rates rise, the bank is unlikely to call the CD, meaning the investor remains locked into the original, lower rate. Integrating callable CDs into a ladder requires careful consideration of the interest rate outlook and the investor’s willingness to accept the risk of early redemption. They represent a more aggressive, yet potentially rewarding, component for experienced CD ladder practitioners.
CD laddering, whether in its basic form or through advanced variations, remains a robust and innovative technique for managing fixed-income investments. By thoughtfully structuring CD maturities, investors can achieve a desirable blend of liquidity, yield, and risk mitigation, making it an indispensable tool for strategic financial planning.